Student Loan Interest Rates Plan 1

So, there I was, fresh out of college, diploma in hand, and a student loan statement that looked like it had been written in ancient Greek. I mean, who knew that 'interest' co...
So, there I was, fresh out of college, diploma in hand, and a student loan statement that looked like it had been written in ancient Greek. I mean, who knew that 'interest' could have so many different meanings? But hey, that's life, right? We all graduate with a shiny new degree and a not-so-shiny pile of debt.
Now, I know what you're thinking, "Here we go again, another sob story about student loans." But hold your horses, folks! Today, we're not here to cry over spilled milk (or in my case, spilled student loan payments). We're here to talk about something way more interesting - Student Loan Interest Rates Plan 1.
What's this Plan 1 thing all about?
Alright, so you're probably wondering what makes Plan 1 so special. Well, let me tell you, it's not because it's the most exciting thing to talk about at a party. No, Plan 1 is special because it's one of the two main plans the UK government uses to calculate student loan interest.
Must Read
Now, I know what you're thinking, "Interest rates? Boring! I just want to know how much I owe and how to pay it off." Well, hold on to your hats, because understanding interest rates is actually pretty important. It's like understanding the rules of a game before you start playing. You might not enjoy learning them, but trust me, it'll make the game (or in this case, paying off your loan) a whole lot easier.
So, what's the deal with Plan 1?
Plan 1 is the oldie but goodie of the student loan world. It's been around since 1990, and it's designed for students who started their course before September 2012. Here's the basic gist:
- Interest is charged at RPI (Retail Price Index) plus 3%.
- You start repaying your loan once you earn over the threshold (currently £27,295 a year).
- Any outstanding balance is written off after 25 years (or 30 years for Scotland).
Now, I know that might sound like a lot to take in, but don't worry, we'll break it down even further. First things first, let's talk about that RPI thing.
RPI, what's that?
Alright, so RPI stands for Retail Price Index. It's basically a measure of inflation, which is just a fancy way of saying how much prices have gone up over time. It's used to make sure your loan interest keeps up with the cost of living. Now, I know what you're thinking, "Why not just use the Consumer Price Index (CPI) like everyone else?" Well, that's a great question!
You see, the UK government decided to use RPI instead of CPI because it includes housing costs. This means that if the cost of housing goes up, your loan interest will too. Now, I'm not saying it's fair, but that's just the way it is. So, if you're planning on becoming a property tycoon, you might want to think twice about it.
Anyway, back to the point. So, RPI plus 3% is the interest rate for Plan 1 loans. Now, I know what you're thinking, "That sounds like a lot of math. Can't I just skip to the part where I throw money at my loan and it goes away?" Well, I wish it were that simple, but unfortunately, it's not. So, let's dive a little deeper into how this interest rate works.
How does the interest work?
Alright, so here's the deal. Your loan interest is calculated monthly, based on the outstanding balance of your loan. This means that the more you owe, the more interest you'll pay. It's like a never-ending cycle of debt and despair... I mean, it's just how it works.
Now, I know what you're thinking, "This is all well and good, but what does it actually mean for me?" Well, let me tell you, it means that your loan could grow at a pretty impressive rate. In fact, according to the Student Loans Company, if you took out a loan in 2012 and you're earning the repayment threshold, your loan could double in size by the time you're 50. Now, that's what I call a 'growth opportunity'!
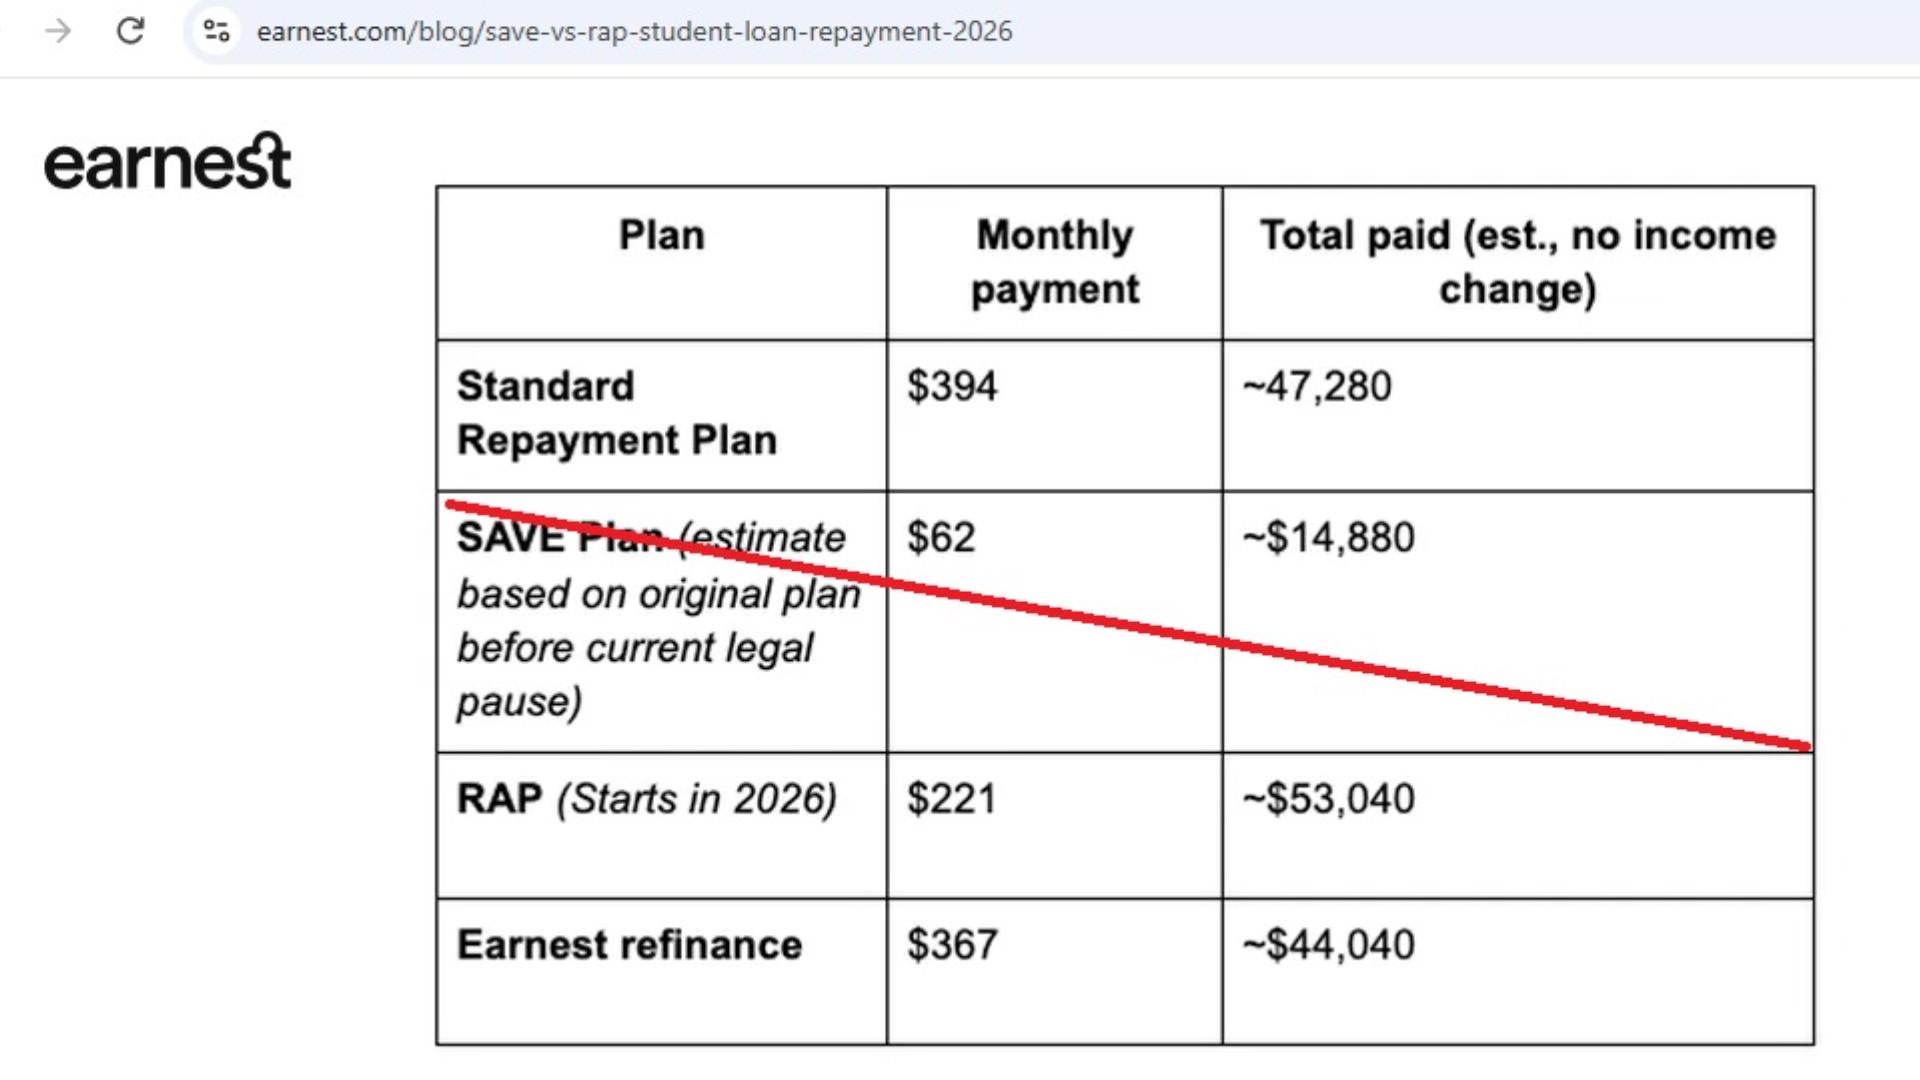 Save on your student loans! Get a 1% interest rate reduction if you
But don't worry, all is not lost. There are a few things you can do to make sure your loan doesn't become a monster that eats your future. First, you could try to pay off your loan as quickly as possible. I know, I know, it's easier said than done, but every little bit helps. Plus, the faster you pay off your loan, the less interest you'll have to pay.
Another thing you could do is keep an eye on your RPI. If it goes down, your interest rate will too. Now, I know that might not sound like much, but every little bit helps, right? Plus, it's always good to know what's going on with your loan. Knowledge is power, after all.
But what about Plan 2?
Alright, so you might be wondering, "What about Plan 2? What makes it so different from Plan 1?" Well, I'm glad you asked! Plan 2 is the newer, shinier version of student loan interest rates. It was introduced in 2012 for students starting their course after that date, and it's a little bit different from Plan 1.
Here's the basic breakdown:
- Interest is charged at RPI (Retail Price Index) plus up to 3%.
- You start repaying your loan once you earn over the threshold (currently £27,295 a year).
- Any outstanding balance is written off after 30 years (or 40 years for Scotland).
Now, I know what you're thinking, "That doesn't sound so different from Plan 1." And you're right, it's not. But there are a few key differences that make Plan 2 a bit more... well, let's just say 'interesting'.
First of all, the interest rate for Plan 2 can go up to 3%. That might not sound like much, but it means that your loan could grow even faster than it would under Plan 1. Plus, the repayment threshold is lower for Plan 2 loans, which means you'll start repaying your loan as soon as you earn over £27,295 a year. Now, I don't know about you, but I think that's a bit steep!
But wait, there's more! Plan 2 loans also have a higher repayment rate. Instead of repaying 9% of your income over the threshold, you'll repay 9% of everything you earn over £27,295 a year. That means that if you're earning £30,000 a year, you'll be repaying 9% of the whole £30,000, not just the £2,705 over the threshold. Ouch!
Now, I know what you're thinking, "This is all well and good, but what does it actually mean for me?" Well, let me tell you, it means that if you're on Plan 2, you could be paying back your loan for a lot longer than someone on Plan 1. In fact, according to the Institute for Fiscal Studies, graduates on Plan 2 could be paying back their loans for up to 50 years. Now, that's what I call a 'long-term investment'!
 Save on your student loans! Get a 1% interest rate reduction if you
But don't worry, all is not lost. There are still a few things you can do to make sure your loan doesn't become a monster that eats your future. First, you could try to pay off your loan as quickly as possible. I know, I know, it's easier said than done, but every little bit helps. Plus, the faster you pay off your loan, the less interest you'll have to pay.
Another thing you could do is keep an eye on your RPI. If it goes down, your interest rate will too. Now, I know that might not sound like much, but every little bit helps, right? Plus, it's always good to know what's going on with your loan. Knowledge is power, after all.
So, what's the verdict?
Alright, so we've talked about Plan 1 and Plan 2, and I know what you're thinking, "This is all well and good, but which one is better?" Well, I'm glad you asked! The truth is, neither plan is really 'better' than the other. It all depends on when you started your course and how much you earn.
If you started your course before September 2012, you're probably on Plan 1. That means you'll be repaying your loan at RPI plus 3%, and it'll be written off after 25 years (or 30 years for Scotland). If you started your course after that date, you're probably on Plan 2. That means you'll be repaying your loan at RPI plus up to 3%, and it'll be written off after 30 years (or 40 years for Scotland).
Now, I know what you're thinking, "That's all well and good, but what does it actually mean for me?" Well, let me tell you, it means that if you're on Plan 1, you might be able to pay off your loan a bit quicker than someone on Plan 2. But if you're on Plan 2, you might be able to earn a bit more before you start repaying your loan. It's all about finding the balance that works best for you.
But remember, no matter which plan you're on, the most important thing is to keep an eye on your loan and make sure you're paying it off as quickly as you can. The faster you pay off your loan, the less interest you'll have to pay, and the sooner you'll be able to start living your life without the shadow of student debt hanging over you.
So, there you have it, folks. That's the lowdown on Student Loan Interest Rates Plan 1. I know it might not be the most exciting thing in the world, but it's important to understand how it works if you want to make the most of your student loan and start building a future for yourself.
And who knows, maybe one day we'll look back on all this and laugh. But until then, let's just try to make the best of it and keep moving forward. After all, that's what life's all about, right?
