How Do You Improve Credit Score

Credit Score: The Elusive Number That's Always Watching So, there I was, minding my own business, applying for a new credit card. I mean, who doesn't love a good points syste...
Credit Score: The Elusive Number That's Always Watching
So, there I was, minding my own business, applying for a new credit card. I mean, who doesn't love a good points system, right? But then, the dreaded question popped up: "What's your credit score?" I felt like a kid caught with their hand in the cookie jar. I knew I should've checked it before, but you know how it is, life gets busy, and suddenly, you're standing there, clueless.
That's when it hit me. I needed to get serious about this credit score thing. It's not just some random number that banks pull out of a hat. It's like your financial report card, following you around, influencing everything from your loan rates to your chances of renting that swanky apartment.
What's This Magic Number All About?
Your credit score is a three-digit number, usually ranging from 300 to 850, that summarizes your credit history. It's calculated based on factors like your payment history, amounts owed, length of credit history, new credit, and types of credit used. The higher your score, the more financially responsible you seem to lenders.
Must Read
Now, you might be thinking, "That's great, but how do I actually improve this mystical number?" Well, grab a cup of coffee, because we're about to dive into the nitty-gritty.
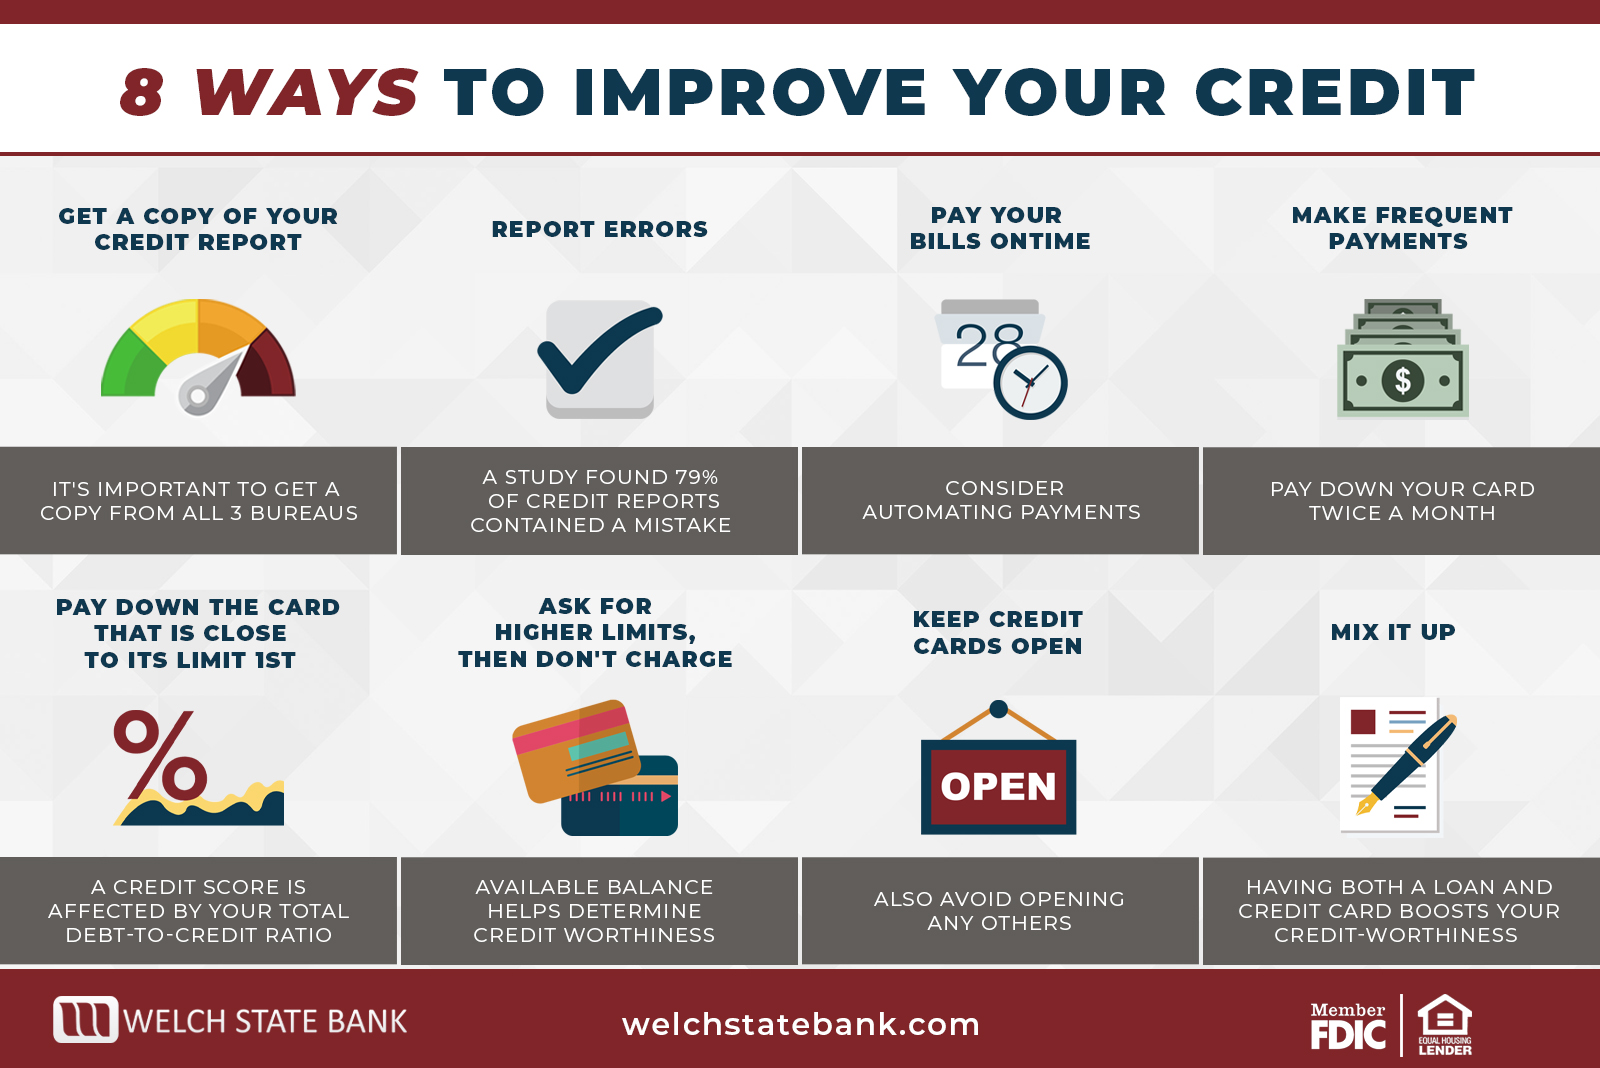
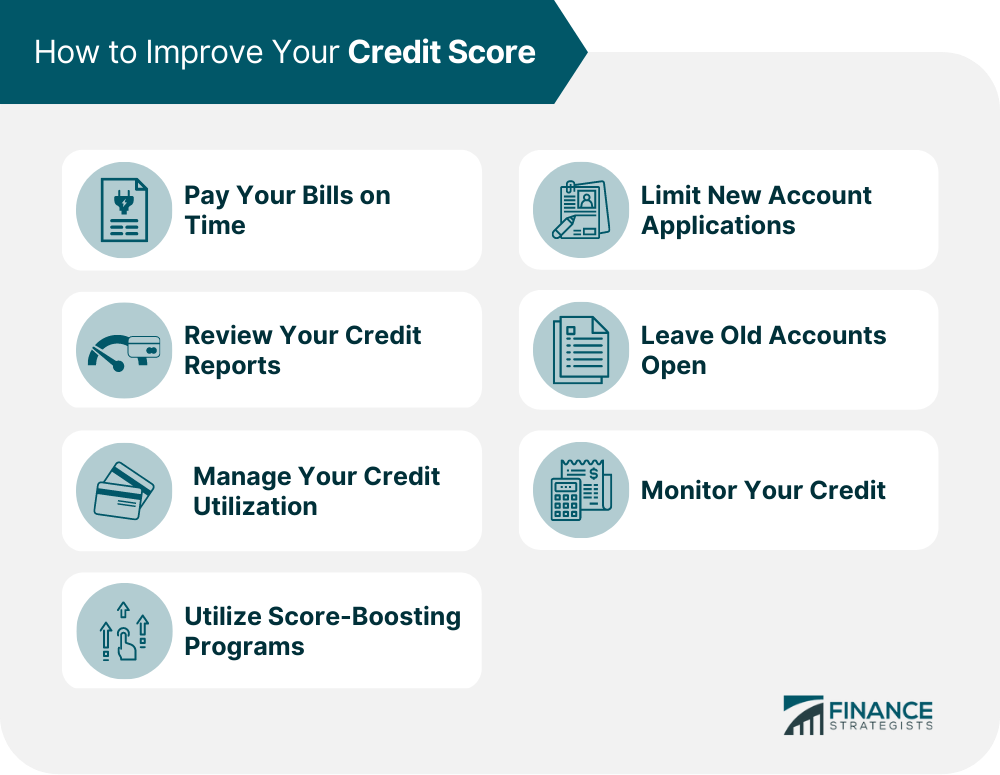
Pay Your Bills on Time, Every Time
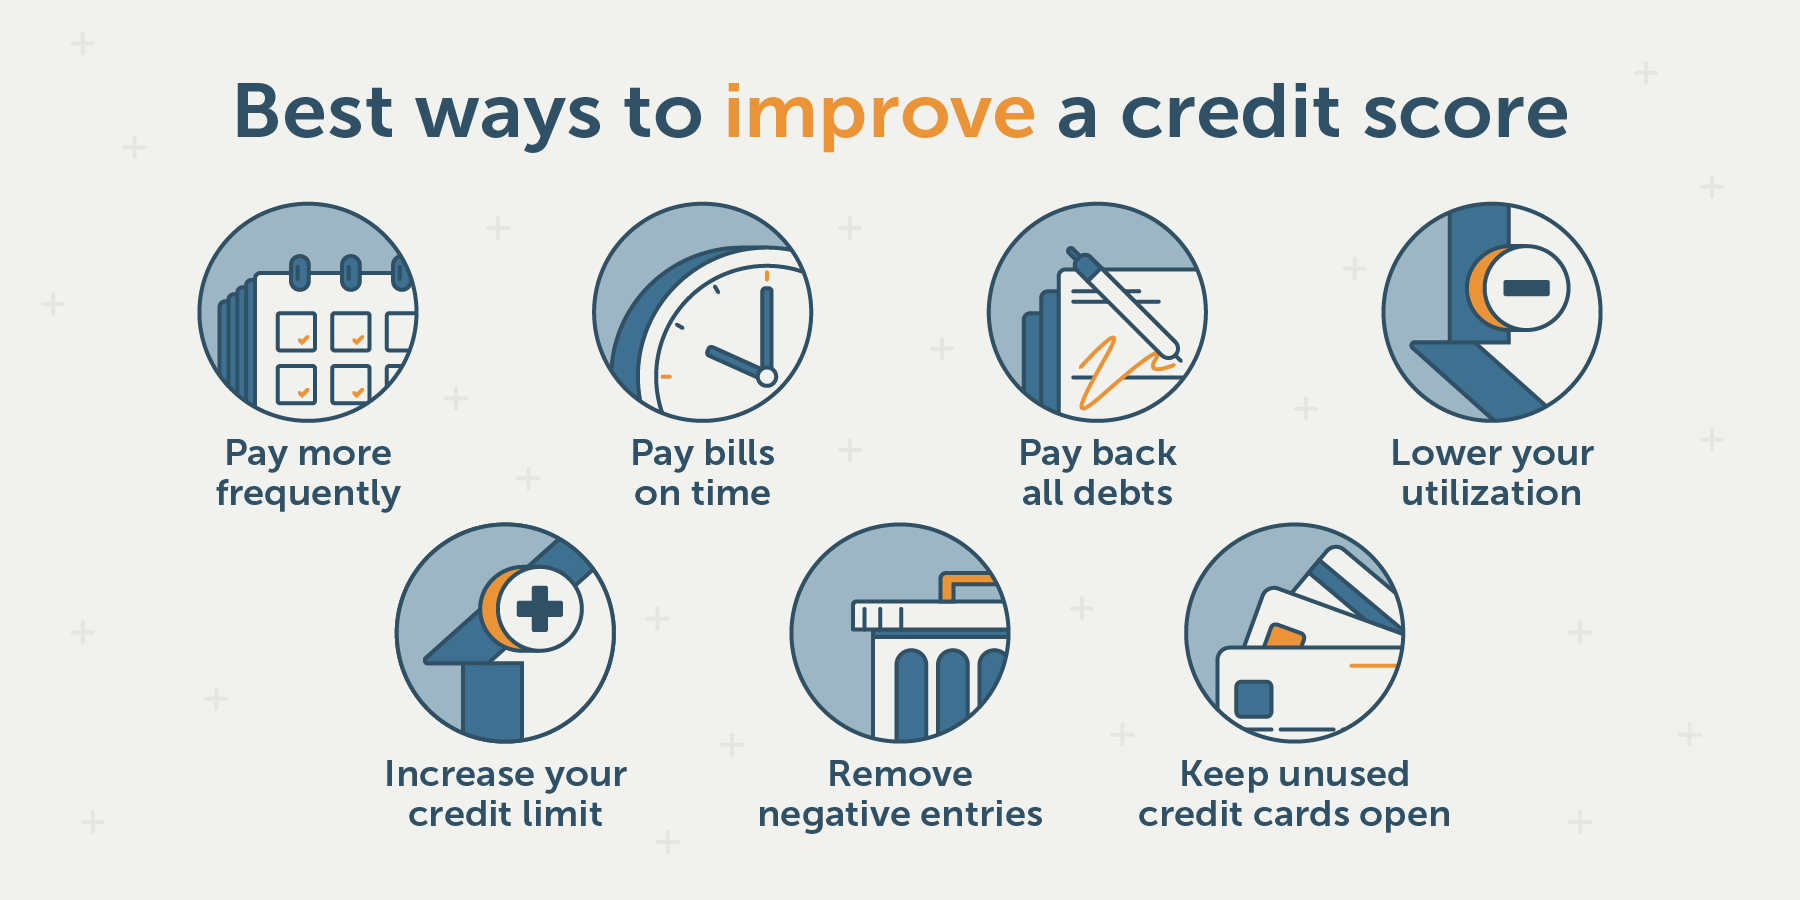
Your payment history makes up 35% of your credit score, making it the most important factor. So, set reminders, automate payments, do whatever it takes to ensure you're paying your bills on time. Even one late payment can ding your score, so don't let that happen.
Keep Your Balances Low
Your credit utilization, or the amount of credit you're currently using compared to your total available credit, accounts for 30% of your score. The lower your utilization, the better. Aim to keep it below 30%. For example, if your credit limit is $10,000, try not to use more than $3,000.
 How to Improve Your Credit Score & Why It Is Important
Pro tip: If you've got a big purchase coming up, consider making multiple smaller payments instead of waiting until the end of the billing cycle. This can help keep your utilization down.
Be Patient, Grasshopper
The length of your credit history makes up 15% of your score. The longer your history, the better. So, if you're new to credit, don't worry. With time and responsible credit use, your score will improve.
Now, I know what you're thinking: "But I don't have any credit history! How do I build it?" Start small. Get a secured credit card, use it for minor purchases, and pay it off in full each month. Before you know it, you'll have a history, and you'll be well on your way to a better score.
 How to Build Credit
Don't Go Credit Card Crazy
Opening too many new accounts at once can hurt your score. Each new account results in a hard inquiry, which can temporarily lower your score. Plus, opening multiple accounts can increase your overall credit utilization. So, be selective about when and why you open new accounts.
Check Your Credit Report Regularly
You're entitled to one free credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) once a year. Use this to your advantage. Check for any errors or inaccuracies, and dispute them if necessary. Keeping an eye on your report can also help you spot any potential fraudulent activity.
Patience, Persistence, and a Little Bit of Math
Improving your credit score takes time, effort, and a bit of financial savvy. But with patience, persistence, and a little bit of math (hello, credit utilization!), you can watch that elusive number climb. And the next time you're applying for a credit card, or a loan, or that dream apartment, you'll be ready. You'll know your score, and you'll know you've earned it.
So, here's to the power of good credit. May your scores be high, and your financial future bright!
