Would I Qualify For A Mortgage Loan

So, you're thinking about taking the plunge into homeownership, huh? You've been binge-watching Fixer Upper and suddenly you're convinced you're the next Chip and Joanna Gaine...
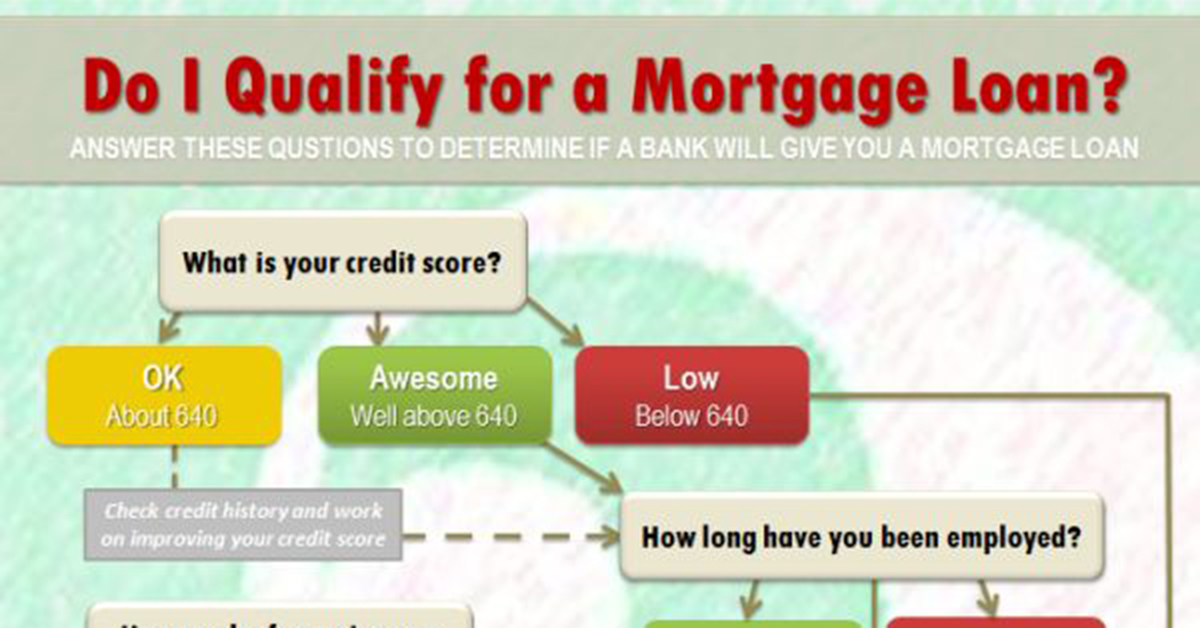
So, you're thinking about taking the plunge into homeownership, huh? You've been binge-watching Fixer Upper and suddenly you're convinced you're the next Chip and Joanna Gaines. But before you start picking out shiplap and farmhouse sinks, there's a little something called a mortgage you need to consider. Let's dive into the wild world of mortgage loans and find out if you're the cat's pajamas when it comes to qualifying.
First Things First: What's Your Credit Score?
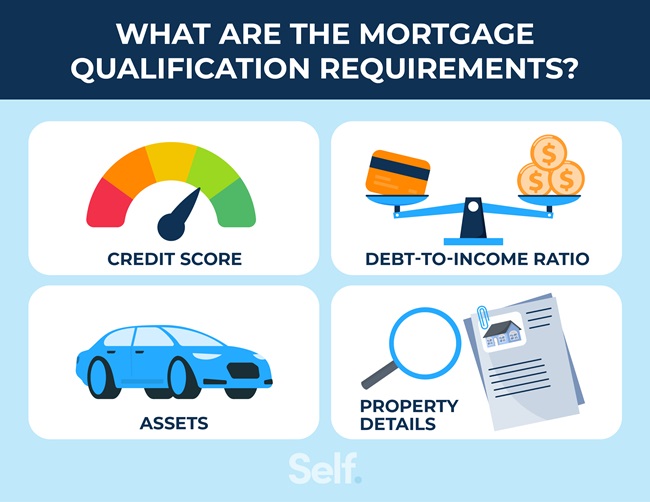
Imagine your credit score is like your high school GPA. It's a number that follows you around, influencing your future prospects. In the mortgage world, the higher your score, the better the deals you'll get. Now, don't go panicking if you're not a perfect 850. There are loans out there for folks with scores as low as 580. But remember, the lower your score, the more you'll pay in interest. It's like getting detention for not studying – it's gonna cost ya.
Debt-to-Income Ratio: The Party Crasher
Now, let's talk about your debt-to-income ratio, or DTI. This is the percentage of your monthly income that goes towards paying off your debts. Lenders want to see a DTI of 43% or less. So, if you're making $5,000 a month, your total debt payments (including your new mortgage) should be $2,150 or less. It's like having a friend who always brings down the vibe at parties – you gotta keep 'em in check.
Must Read
Down Payment: The Magic Number
You've probably heard that you need to put down 20% to buy a house. But who has that kind of cash lying around? Fret not, dear homebuyer. There are loans out there that require as little as 3% down. But here's the catch: if you put down less than 20%, you'll have to pay private mortgage insurance (PMI). It's like having to buy a fancy dress for a party you didn't even want to go to.
Income: The Breadwinner
Lenders want to see a stable income. They're not looking for the next American Idol, they want the accountant who's been crunching numbers for the past decade. Typically, lenders want to see two years of steady employment in the same field. So, if you're planning on switching careers to a professional mermaid, you might want to hold off on that mortgage application.
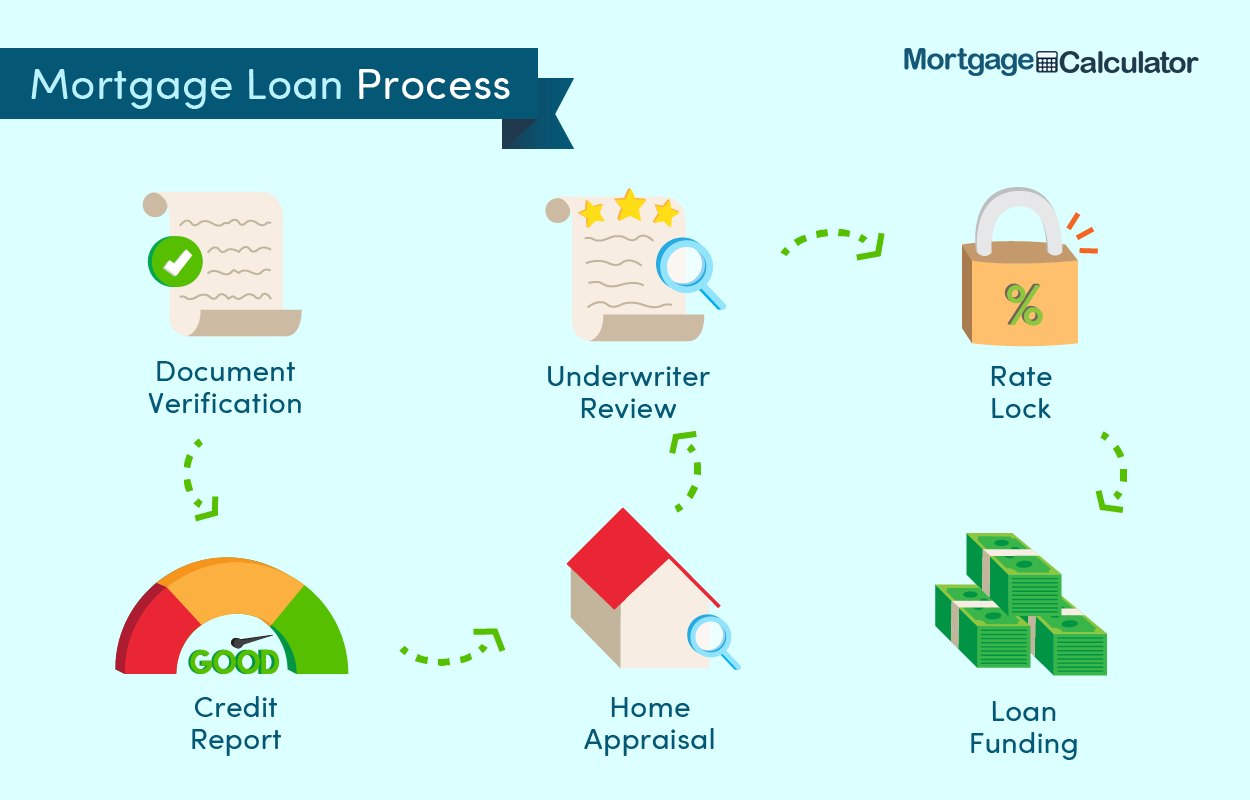 Mortgage Pre Approval
Documentation: The Paper Trail
Get ready to become best friends with your printer. Lenders are gonna want to see a whole slew of documents, including pay stubs, tax returns, and bank statements. It's like they're asking you to relive every financial decision you've ever made. But remember, the more organized you are, the smoother the process will be. It's like cleaning your room before your mom comes over – it's worth it in the end.
Surprise! There's More
You thought we were done, didn't you? Sorry, folks, there's more. Lenders will also look at your savings, your assets, and even your employment history. They're like those overprotective parents who want to know every detail about your prom date. But don't let it deter you. The more prepared you are, the better off you'll be.
 7 Questions to Ask a Mortgage Lender - Self. Credit Builder.
So, Do You Qualify?
Alright, alright, you've been patient. Let's get down to brass tacks. Do you qualify for a mortgage loan? Well, that depends. If you've got a solid credit score, a steady income, a manageable debt-to-income ratio, and some cash saved up, you're off to a good start. But remember, everyone's situation is different. What's a slam dunk for one person might be a bust for another.
Here's the thing: qualifying for a mortgage loan is like trying to fit a square peg into a round hole. It's not always easy, and it's not always pretty. But with a little bit of knowledge, a lot of preparation, and a healthy dose of humor, you can make it work. So, go forth, dear homebuyer, and conquer the mortgage world. And remember, if all else fails, there's always the treehouse you built in your backyard.
