Will I Get A Mortgage If I Have A Loan

So, you've got a loan, huh? You're like the modern-day Robin Hood, taking from the lenders to... well, probably not give to the poor. More like, buying that fancy coffee maker...
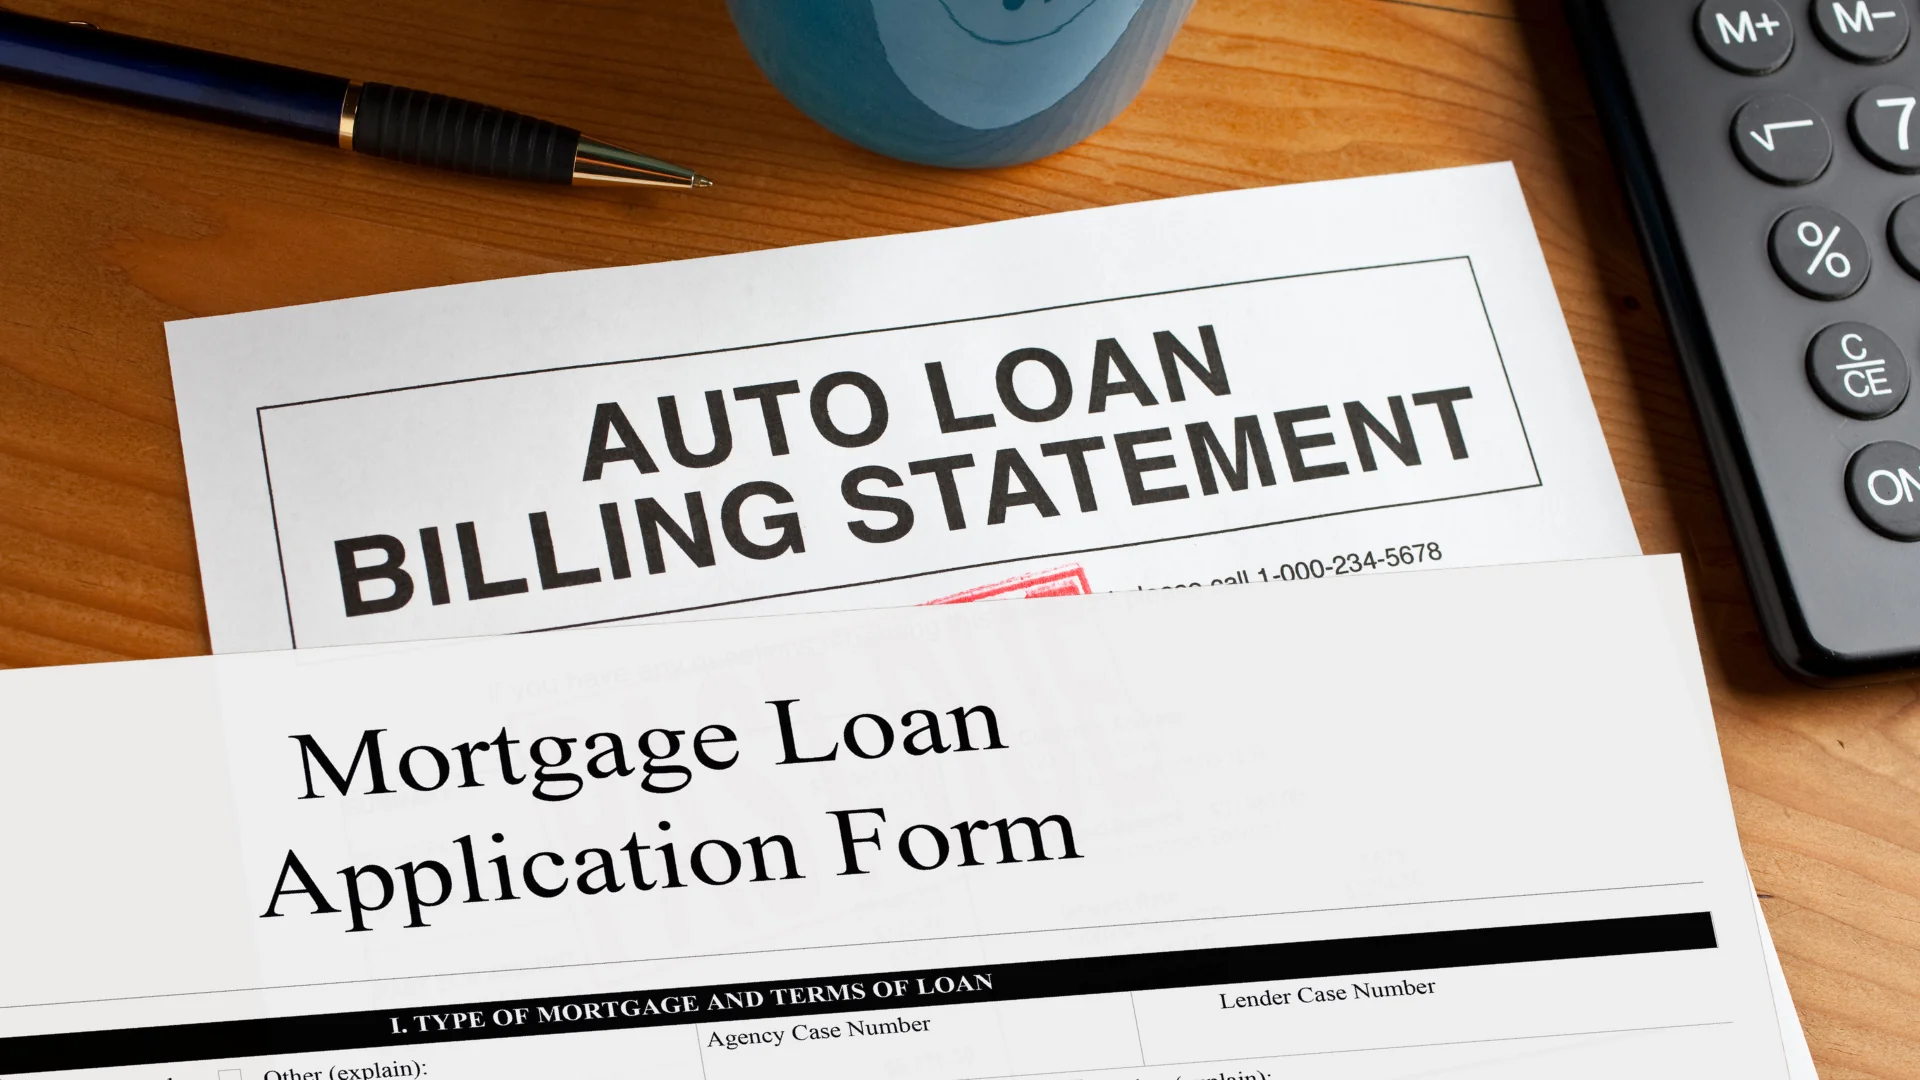
So, you've got a loan, huh? You're like the modern-day Robin Hood, taking from the lenders to... well, probably not give to the poor. More like, buying that fancy coffee maker you've been eyeing. But now, you're wondering, "Will I get a mortgage with this loan hanging over my head?" Let's dive in, shall we?
First things first: What's the big deal with loans and mortgages?
Imagine you're at a fancy restaurant. You've just ordered the most expensive thing on the menu - the "Golden Caviar Surprise." But when the waiter comes back, he says, "Sorry, buddy, you've already ordered the 'Silver Soup' earlier. We can't serve you the 'Golden Caviar' until you've finished that." That's kind of what lenders do. They want to see you handle one debt before they'll let you take on another.
But what if I'm a super responsible borrower?
Alright, let's say you're not your average Joe. You're a debt-handling ninja. You've been paying off your loan like a pro, and you've got the credit score to prove it. Great! Lenders love responsible borrowers. It's like they're your own personal cheerleading squad, chanting, "Go, borrower, go!"
Must Read
Now, let's talk about debt-to-income ratio. It's not as scary as it sounds, I promise.
Think of your income as a big, delicious pizza. Now, you've got to divide that pizza into slices for all your expenses - rent, utilities, groceries, and of course, your loan payment. Lenders want to see that you've got enough pizza left over for a mortgage payment. The general rule of thumb is that your total debt payments (including your new mortgage) shouldn't be more than 43% of your income. So, if your income is like a large pizza, you've got to make sure you're not ordering too many toppings.
But what if I'm living paycheck to paycheck?
Alright, let's say you're not exactly rolling in dough. You're more of a 'Ramen Noodle' kind of person. That's okay! There are still mortgage options out there for you. You might just need to shop around a bit more. It's like going to a buffet and finding the hidden gem of a dish that's not on the menu - it's out there, you just have to look for it.
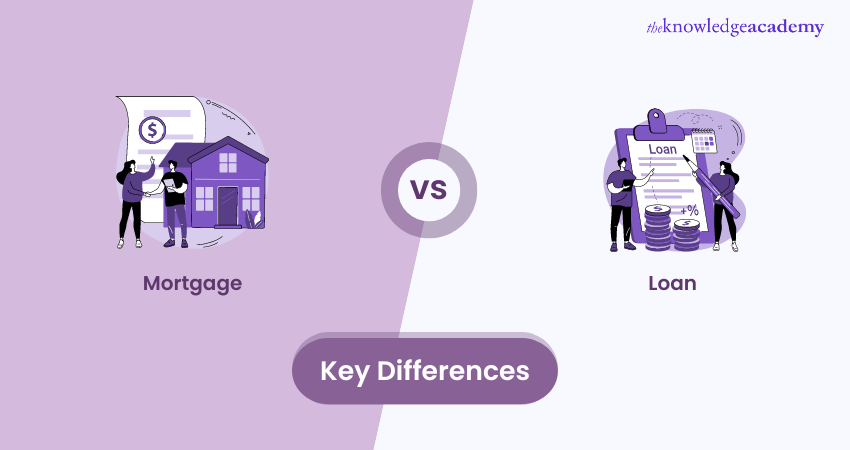 Mortgage vs. Loan: What is the Difference?
What about my credit score? Can I still get a mortgage with a loan?
Your credit score is like your financial report card. Lenders want to see that you're getting good grades. If you've been paying off your loan like a champ, your score should be looking pretty good. But if you've been slacking off, it might be time to hit the books and start studying (aka paying your bills on time).
But what if my credit score is less than stellar?
Okay, so maybe your credit score is more 'D' than 'A'. Don't panic! There are still mortgage options out there for you. You might just have to pay a higher interest rate. It's like ordering a fancy drink at the bar - if you want the good stuff, you've got to pay a little extra. But remember, the more you can improve your score before applying, the better deal you'll get.
 » Home Loan Subsidy by Government in 2026 – Eligibility and Rules
So, will I get a mortgage with a loan? The final word.
Here's the thing, folks. Getting a mortgage with a loan is like trying to fit into last year's jeans. It's possible, but it might be a tight squeeze. The key is to show lenders that you're responsible, you've got a good debt-to-income ratio, and your credit score is in tip-top shape. And hey, if all else fails, you can always try the 'mom jeans' approach - they might not be the most fashionable, but they'll get the job done.
So, go forth, brave borrower! With a little bit of financial finesse and a whole lot of responsibility, you too can join the ranks of homeowners. And who knows? Maybe one day, you'll be the one ordering the 'Golden Caviar Surprise' and the 'Silver Soup' all in one night. But for now, let's take it one debt at a time, shall we?
