When Do You Pay Capital Gains Tax

Alright, folks, let's talk about something that's not as scary as it sounds - capital gains tax. I promise, by the end of this, you'll be nodding along like a pro, and maybe e...
Alright, folks, let's talk about something that's not as scary as it sounds - capital gains tax. I promise, by the end of this, you'll be nodding along like a pro, and maybe even chuckling at how simple it is. So, grab a cuppa, get comfy, and let's dive in!
What's the Big Deal?
First things first, why should you care about capital gains tax? Well, imagine you're selling your old car. You bought it for $10,000, and now you're selling it for $15,000. That's a $5,000 gain, or as the tax folks call it, a capital gain. Now, you might be thinking, "That's just a car, it's not like I'm selling a mansion!" But the principle is the same, and that's why capital gains tax matters, even for everyday folks like you and me.
When Does the Taxman Come Knocking?
Now, you're probably wondering, "When do I actually have to pay this capital gains tax?" Great question! The answer is, it depends on how long you've held onto your asset. Here's a simple breakdown:
Must Read
Short-Term Gains
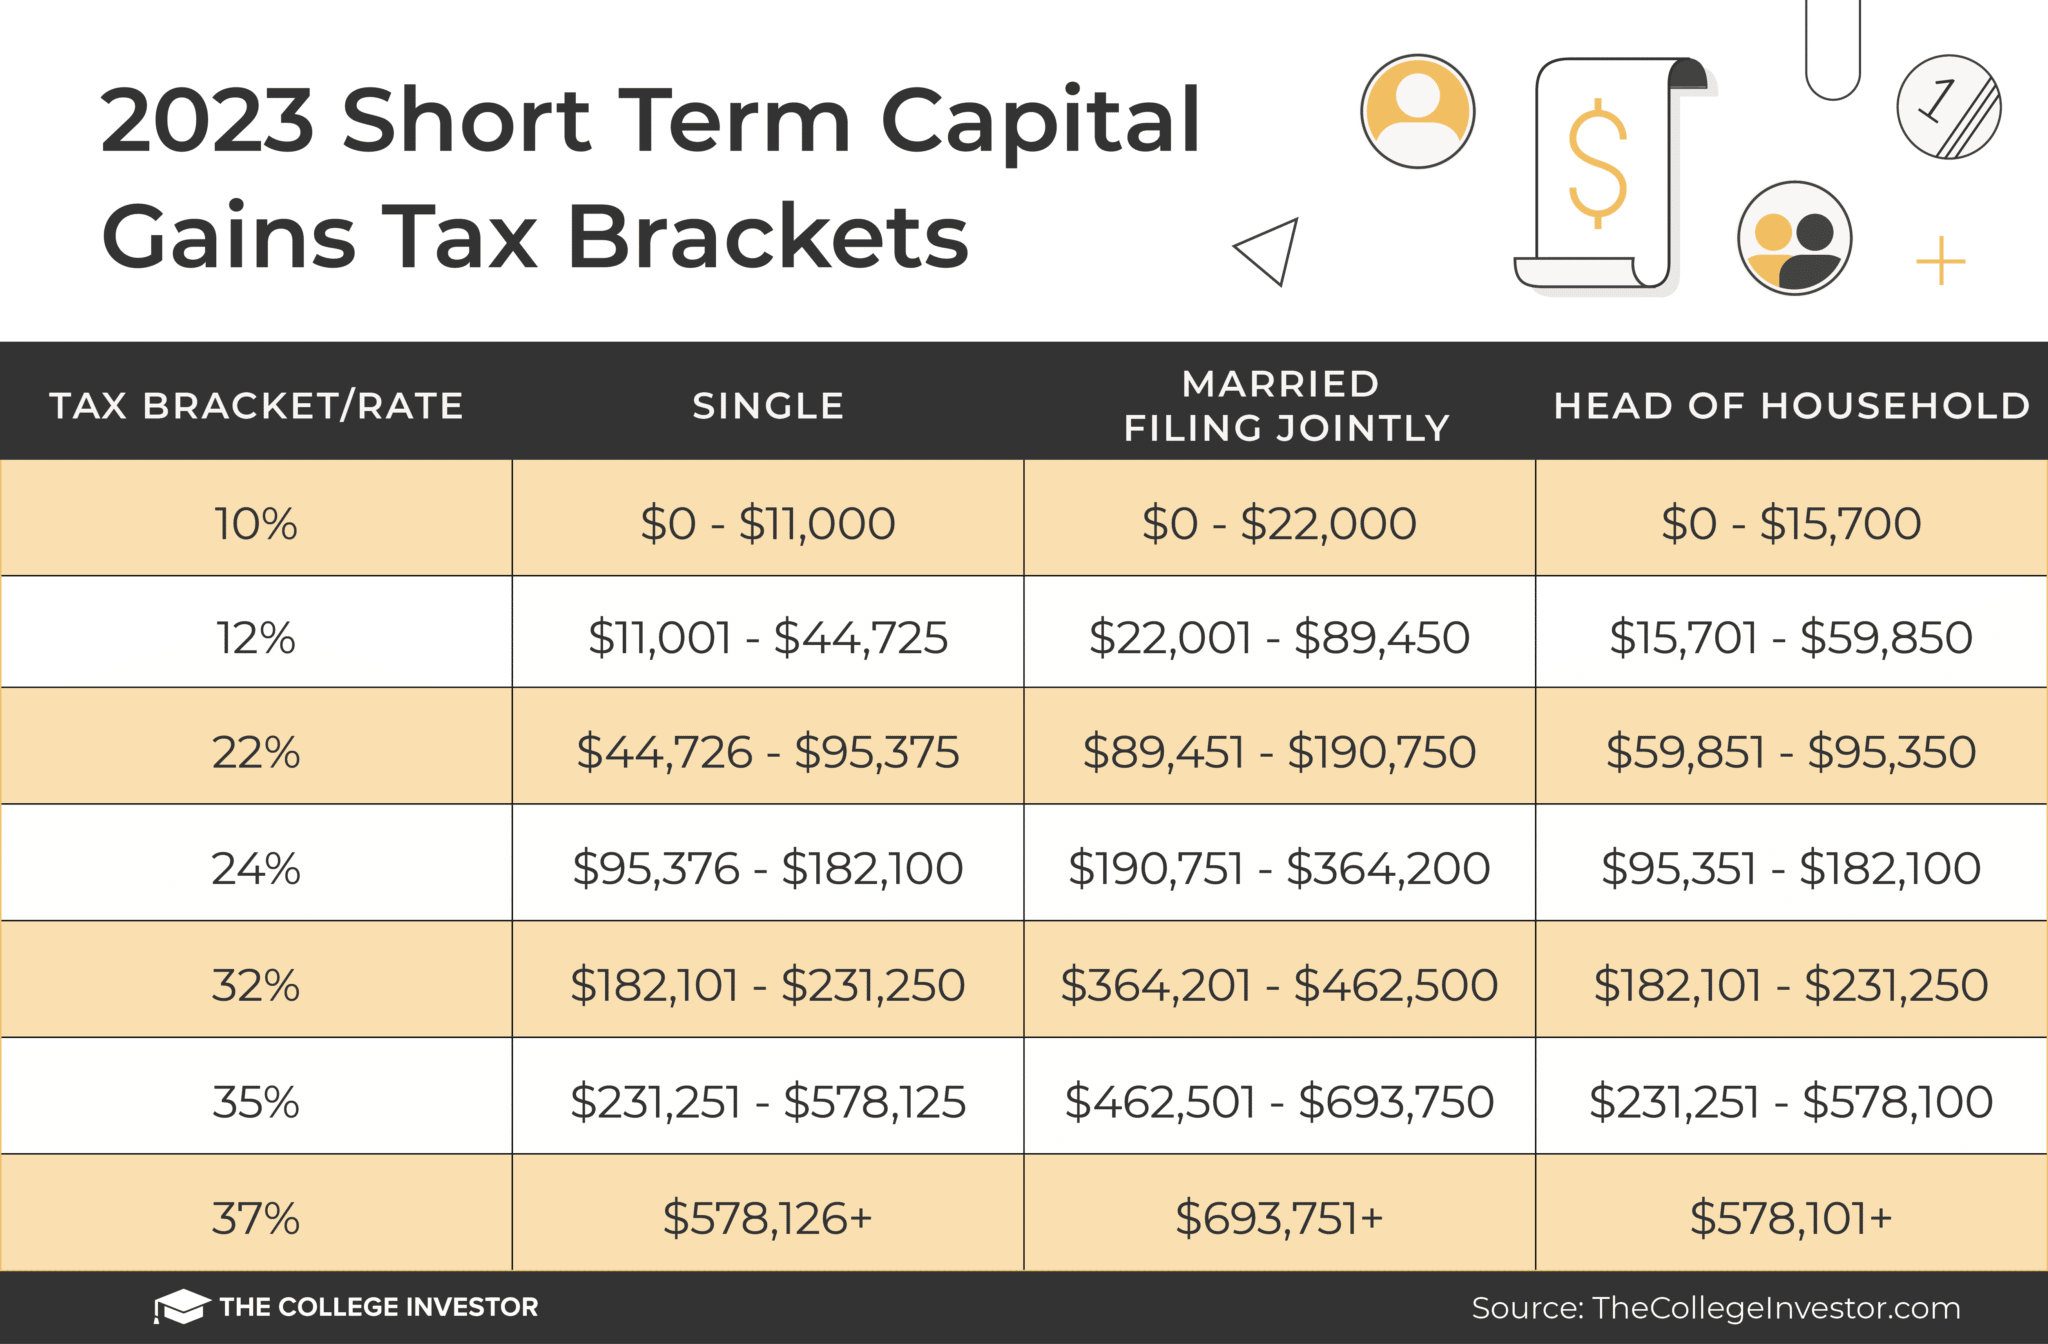
If you sell something within a year of buying it, any profits you make are considered short-term gains. These are taxed just like your regular income. So, if you're in the 22% tax bracket, that's how much you'll pay on your gains. Not too bad, right?
Long-Term Gains
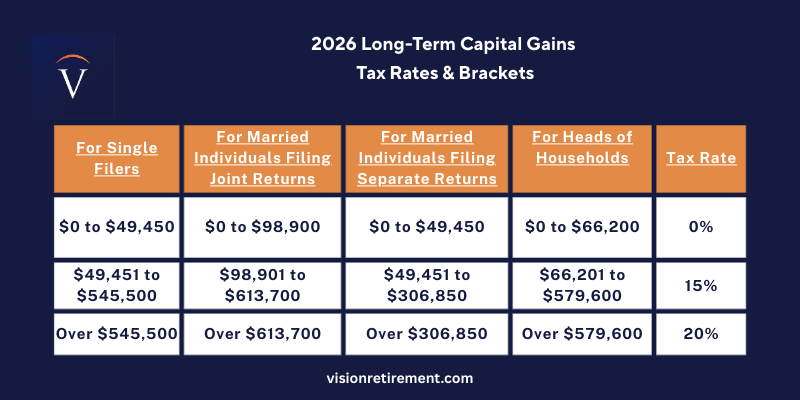
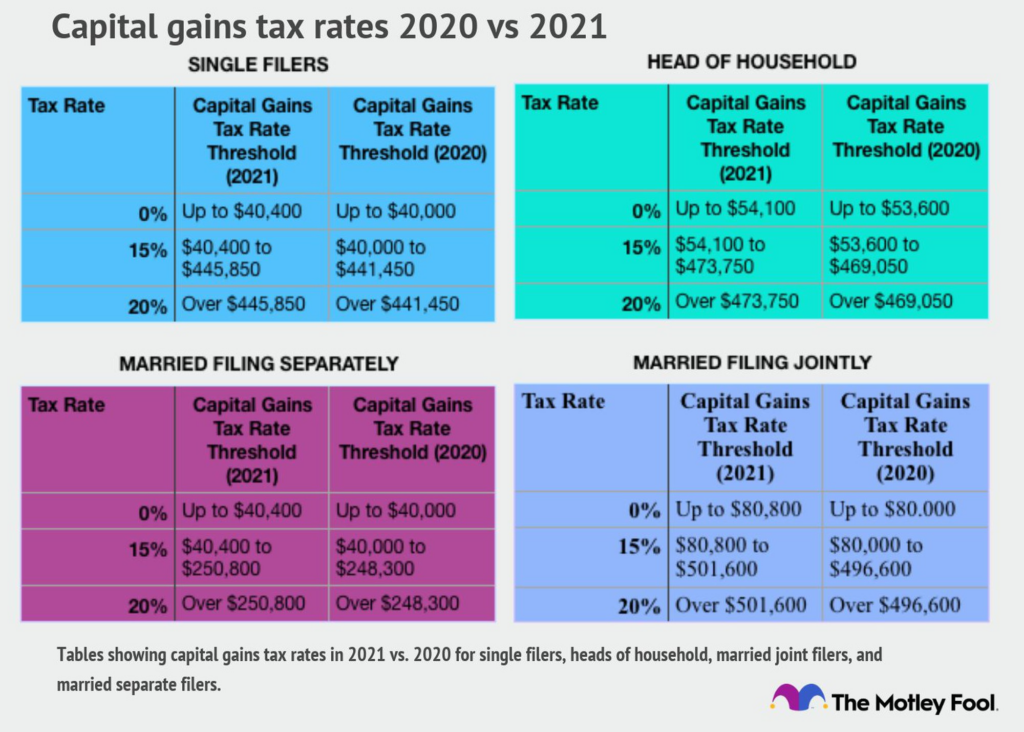
But here's where it gets interesting. If you hold onto an asset for more than a year before selling it, any profits you make are considered long-term gains. And guess what? These are taxed at a much lower rate than regular income. The highest long-term capital gains tax rate is only 20%, even for those in the highest income bracket. That's like getting a little tax discount for being patient!
 Do you pay taxes on an inheritance?
Let me put it another way. Imagine you're a farmer selling your crops. If you sell them the day after planting, you'll pay the same tax rate as if you were selling apples from your backyard tree. But if you wait a year, you'll pay less tax. It's like the taxman saying, "Thanks for being patient, here's a little reward!"
But Wait, There's More!
Now, you might be thinking, "That's all well and good, but I don't want to pay any tax at all!" Well, hold onto your hats, because there's a way to avoid capital gains tax altogether. It's called the primary residence exclusion. In the U.S., if you sell your home and make a profit, you can exclude up to $250,000 of that gain from your taxes if you're single, or up to $500,000 if you're married filing jointly. That's like the taxman giving you a high-five and saying, "Well done on your new home!"
But here's the catch - you have to have lived in your home for at least two of the past five years to qualify. So, it's not just about selling, it's about staying put too. Think of it like a little game of musical chairs, but with tax breaks instead of music.
 Capital Gains Tax: A (Mostly) Unavoidable Reality - Physician on FIRE
So, What's the Takeaway?
Alright, folks, here's what you need to remember. Capital gains tax is just a fancy way of saying, "You made some money on that thing you sold." It's not as scary as it sounds, and it's not something that'll affect you every day. But when it does, it's nice to know you've got a little tax discount waiting for you if you're patient. And who knows, maybe one day you'll sell your home and get a nice tax-free pat on the back from Uncle Sam.
And remember, this is just a quick chat about capital gains tax. The rules can get a bit more complicated, so if you've got a big sale coming up, it's always a good idea to chat with a tax pro or financial advisor. They can help you navigate the ins and outs, and make sure you're getting the best deal possible.
Until next time, folks! Keep selling, keep smiling, and remember, the taxman's not always out to get you. Sometimes, he's just there to give you a high-five.
