What Is The Suffix On A Bank Account

So, there I was, standing in line at the bank, waiting for my number to be called. You know the drill - the fluorescent lights, the faint smell of old paper, and the ever-pres...
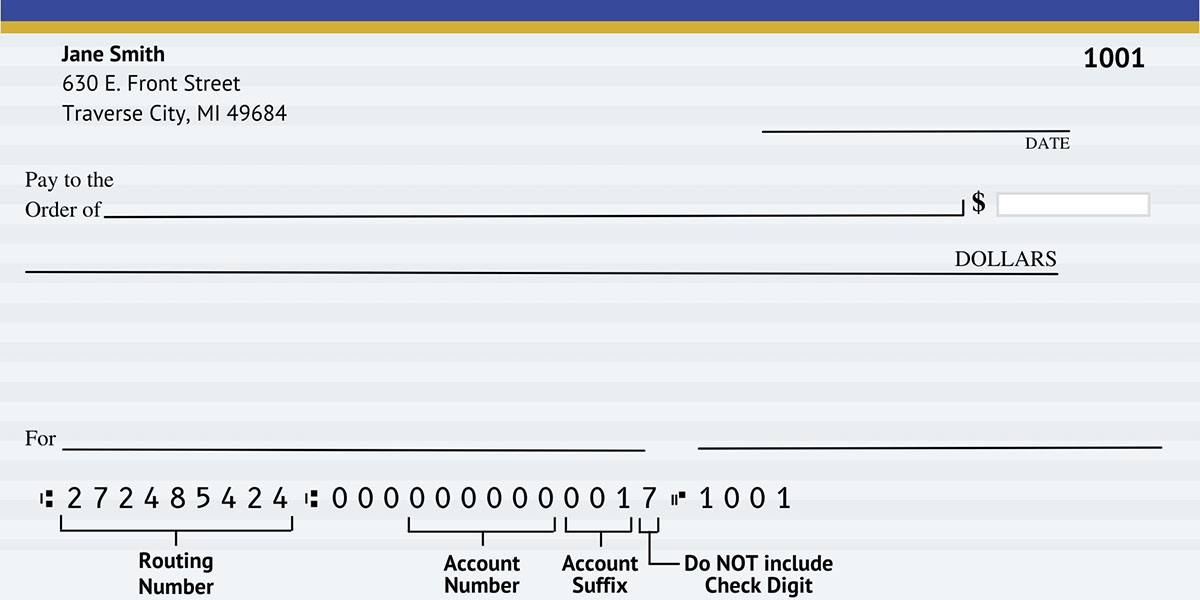
So, there I was, standing in line at the bank, waiting for my number to be called. You know the drill - the fluorescent lights, the faint smell of old paper, and the ever-present hum of the air conditioner. I was there to open my first ever joint account, and I was a bit nervous. I mean, I knew the basics, but I wanted to make sure I didn't sound like a total newbie when the teller asked me what kind of account I wanted to open.
As I was waiting, I overheard the teller helping the person in front of me. She was explaining something about a suffix on their account. I was intrigued. I mean, I knew about prefixes and suffixes from my high school English class, but on a bank account? I was curious, and I knew I had to ask when it was my turn.
What's in a Suffix?
Alright, so let's rewind a bit. You're probably here because you've heard about this mysterious suffix on a bank account and you're wondering what it's all about. Well, buckle up, because we're about to dive into the world of banking jargon. Don't worry, I'll keep it simple and fun, just like a chat with an old friend.
Must Read
You see, when you open a bank account, you're not just giving them your hard-earned money to keep safe (well, you are, but that's not the point). You're also telling them a bit about yourself - your name, your address, your ID number, and so on. This is all part of the account opening process, and it helps the bank know who they're dealing with.
Now, here's where the suffix comes in. When you open an account, the bank needs to know who else, if anyone, has access to that account. This is where the suffix comes into play. It's a way of telling the bank, and the world, what kind of account you have and who's involved.
Let's Talk About Names
When you open a bank account, you're usually asked to provide your full name. This is your first name, middle name (if you have one), and last name. But what if you want to open a joint account with your partner, or a business account with your colleagues? That's where the suffix comes in.
You might be thinking, "But I thought suffixes were for grammar, not banking!" Well, you're not wrong. In grammar, a suffix is a letter or group of letters added to the end of a word to change its meaning or part of speech. In banking, a suffix is a letter or group of letters added to the end of a name to indicate the type of account or the relationship between the account holders.
For example, let's say you're opening a joint account with your partner. You might see something like this on your account application:
Account Holder 1: John Doe I
Intra-Institution Transfers
Account Holder 2: Jane Doe II
In this case, the suffixes "I" and "II" are telling the bank that these two people are joint account holders. It's a simple way of indicating that they're both responsible for the account and have equal access to it.
And Then There's Business
Now, let's talk about business accounts. When you open a business account, you're not just opening it in your own name. You're opening it in the name of your business. This is where suffixes like "Inc.", "LLC", "LLP", and "Corp." come into play.
These suffixes are telling the bank, and anyone who looks at your account information, that this account belongs to a specific type of business entity. For example, "Inc." stands for "Incorporated", which is a type of business structure that provides limited liability protection to its owners. "LLC" stands for "Limited Liability Company", which is another type of business entity that offers limited liability protection.
Using these suffixes on your business account helps to keep your business and personal finances separate. It also makes it clear to anyone who looks at your account information that this account is for business purposes only.
So, What's the Big Deal?
You might be wondering, "Why does any of this matter? I just want to open a bank account and be done with it." Well, here's the thing - understanding the suffix on your bank account can help you make sure that your account is set up the way you want it to be.
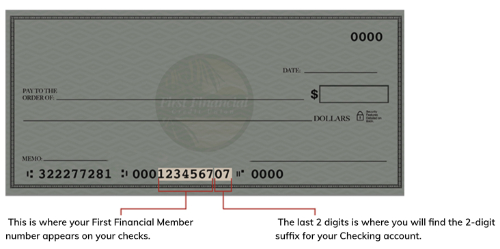 First Financial Credit Union | Routing and Account Numbers
For example, let's say you're opening a joint account with your partner. If you don't specify that you want a joint account with equal access for both of you, the bank might set it up as a single account with you as the primary account holder and your partner as an authorized user. This means that your partner wouldn't have equal access to the account, and they wouldn't be able to make decisions about the account without your permission.
Similarly, if you're opening a business account, using the correct suffix can help you avoid any legal or tax issues down the line. For example, if you're a sole proprietor, you might be tempted to use "Inc." or "LLC" as your suffix to make your business sound more legitimate. However, this can actually be illegal and can cause problems with the IRS.
Talk to Your Bank
So, what's the moral of the story? Well, when you're opening a bank account, it's important to understand what kind of account you're opening and who's involved. This means knowing what suffix to use and making sure that the bank understands what you want.
Don't be afraid to ask questions if you're not sure. The teller or bank representative is there to help you, and they want to make sure that your account is set up correctly. After all, it's your money, and you deserve to have it handled the way you want.
And remember, understanding the suffix on your bank account isn't just about filling out a form. It's about understanding your rights and responsibilities as an account holder. It's about making sure that your money is safe and that you have the access you need.
So, the next time you're at the bank, don't be afraid to ask about that mysterious suffix. You might just learn something new, and you'll definitely be one step closer to understanding your bank account.
