What Is The Penalty For Not Taking An Rmd

Ever found yourself at a party, munching on some delicious snacks, and someone asks, "Hey, have you taken your RMD yet?" You're probably thinking, "RMD? Isn't that some kind o...

Ever found yourself at a party, munching on some delicious snacks, and someone asks, "Hey, have you taken your RMD yet?" You're probably thinking, "RMD? Isn't that some kind of weird dance move?" Nope, it's not a dance, and it's definitely not something you want to ignore. Let's dive into the world of RMDs, why they matter, and what happens if you don't take one.
What's an RMD, you ask?
Alright, imagine you're at a buffet. You've got a big plate, and you're piling it high with all your favorites. Now, think of your retirement account as that plate. An RMD, or Required Minimum Distribution, is like the server coming by and saying, "Hey, you can't take all that with you. You have to leave some for later." In simple terms, it's the smallest amount you have to withdraw from your retirement account each year after you reach a certain age.
Why do RMDs matter?
RMDs are like your retirement account's way of saying, "Hey, you've saved enough. Now it's time to enjoy it!" They're there to ensure you don't hoard all your retirement savings and leave nothing for your golden years. Plus, the IRS wants their cut, and RMDs help them do that. It's like when you order a large pizza, and your friend says, "Hey, you've got to share some with me, or the pizza police will come after you!"
Must Read
Now, you might be thinking, "But I don't want to take out my money. I want it to keep growing!" That's a valid concern, but remember, RMDs are calculated to minimize the impact on your account's growth. It's like when you're at the buffet, and you realize that eating just a little bit less will help you feel better in the long run.
What happens if you don't take your RMD?
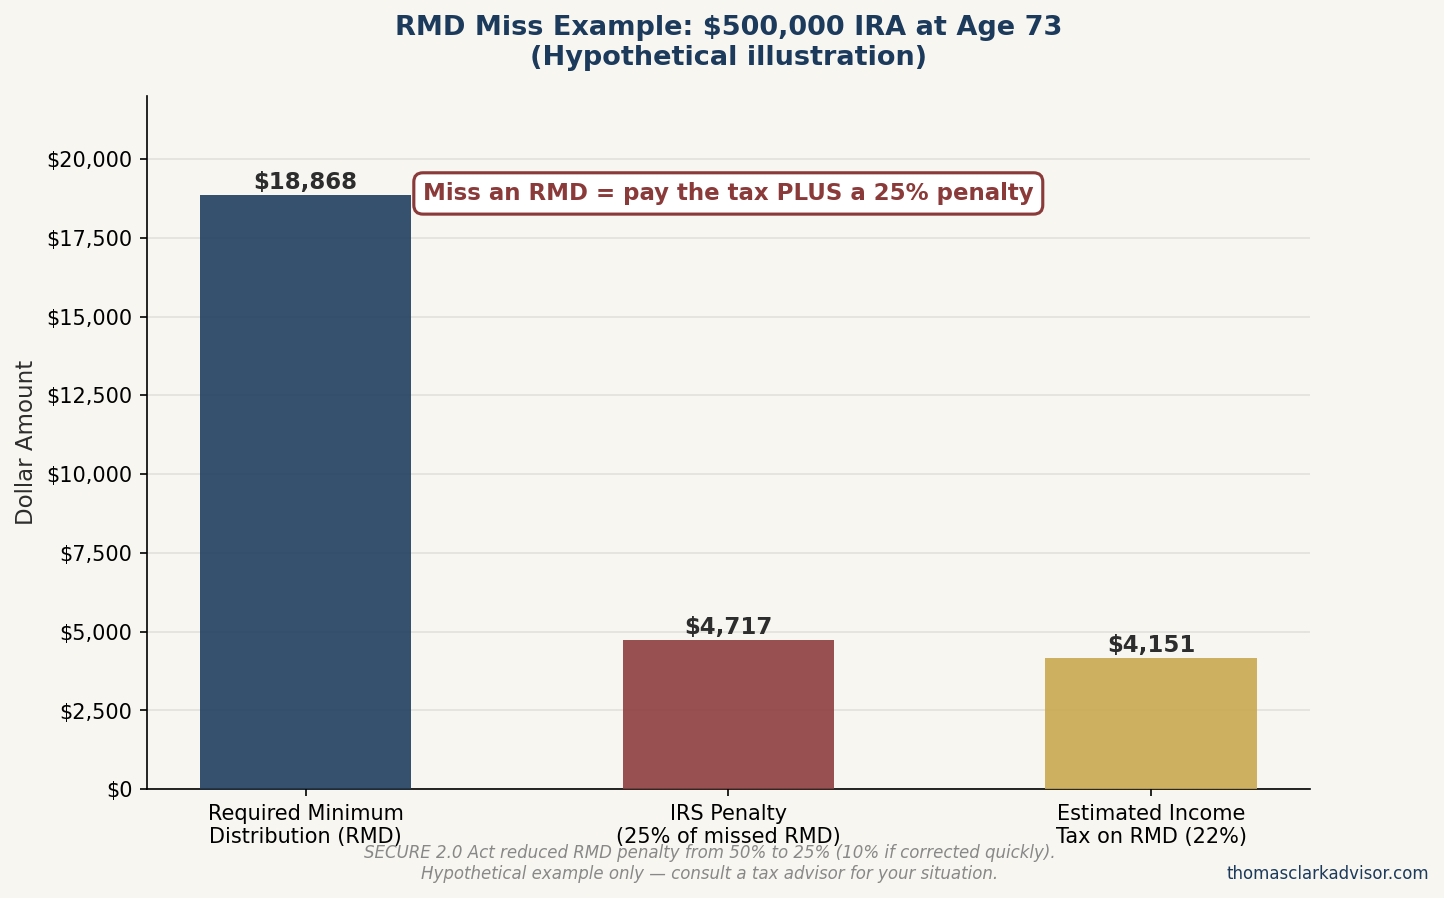
Alright, so you've ignored the server at the buffet, and you've tried to walk out with a plate full of food. What happens next? Well, the "pizza police" in this case are the IRS, and they're not too happy. If you don't take your RMD, the IRS will impose a hefty penalty - 50% of the amount you should have withdrawn but didn't. That's like the pizza place charging you double for trying to sneak out with a whole pie!
 5 Retirement Withdrawal Mistakes That Cost Thousands
Let's put that into numbers. Say you're 72, and you have a retirement account worth $1 million. Your RMD for the year is $37,700. If you don't take that out, the IRS will hit you with a $18,850 penalty. That's a pretty steep price for ignoring a simple rule.
But what if I forget?
We've all been there - you meant to do something, but it slipped your mind. The IRS understands that, to an extent. If you realize you've missed your RMD, you can ask for a waiver. But don't make a habit of it! The IRS will only grant a waiver if you can prove you had "reasonably believed" you were complying with the RMD rules. So, it's best to keep track of your RMDs and take them on time.
How to calculate your RMD
Calculating your RMD might seem daunting, but it's actually pretty simple. The IRS provides a worksheet that walks you through the process. You'll need to know your account's value on December 31 of the previous year and choose a life expectancy factor from an IRS-provided table. It's like following a recipe - you gather your ingredients (account value and life expectancy factor), follow the steps (use the IRS worksheet), and voila! You've got your RMD.
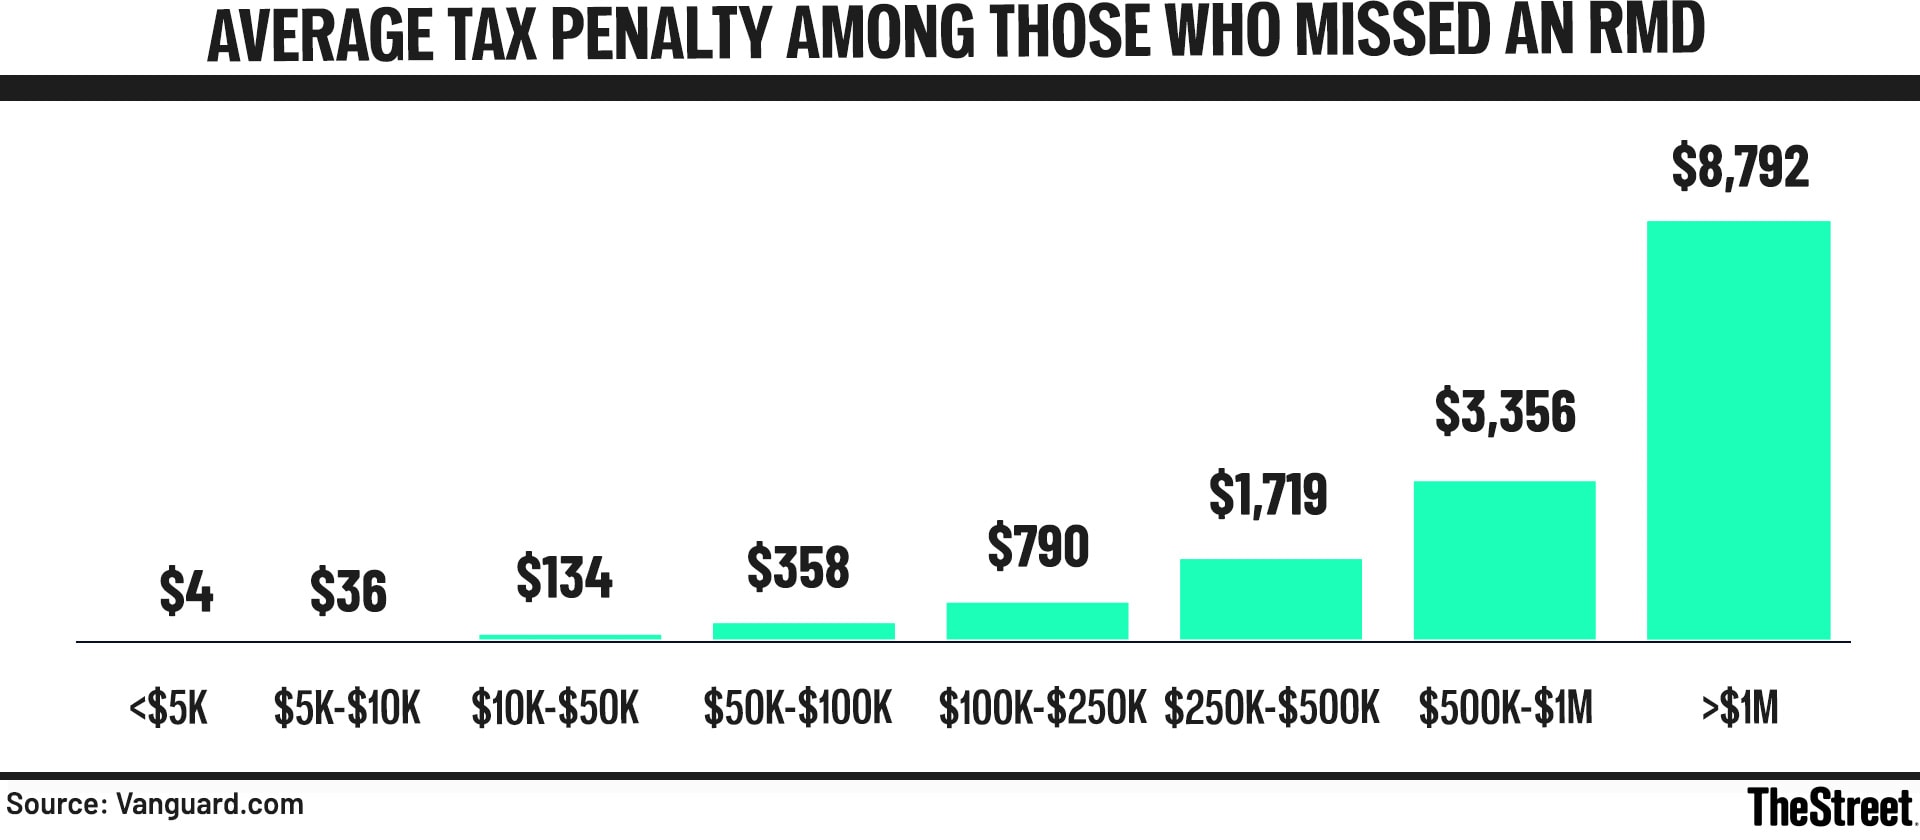 Retirees: Miss the Dec. 31 RMD deadline and face a 25% penalty - TheStreet
If you're not a fan of math or you just want to be extra sure, you can always ask a financial advisor for help. They're like the buffet's server, guiding you through the process and making sure you're taking what you need.
So, should you take your RMD?
Absolutely! RMDs are there to help you manage your retirement savings and ensure you're not leaving money on the table (or in your retirement account). They might seem like a hassle, but they're a necessary part of retirement planning. Plus, think of it this way - you've worked hard for your money, and you deserve to enjoy it. Taking your RMD is just another step in making the most of your retirement.
So, the next time someone asks if you've taken your RMD, you can smile and say, "You bet! I'm enjoying my retirement, one RMD at a time." Now, who's ready for some buffet leftovers?
