What Is The Best Loan Type For A Mortgage

So, You're Thinking About a Mortgage, Eh? Alright, let's dive into this like we're choosing a pizza topping - because let's face it, both decisions can change your life! When...

So, You're Thinking About a Mortgage, Eh?
Alright, let's dive into this like we're choosing a pizza topping - because let's face it, both decisions can change your life! When it comes to mortgages, there's no one-size-fits-all. It's all about finding the best loan type that fits your unique life slice. Let's chat about the three main types: Fixed-Rate, Adjustable-Rate, and FHA Loans.
Fixed-Rate Mortgages: The Steady Eddie
Imagine you're planning a big family dinner. You know exactly how many people are coming, so you plan your grocery list accordingly. That's a fixed-rate mortgage in a nutshell. Your interest rate stays the same throughout the loan term, usually 15 or 30 years. It's predictable, like knowing your favorite restaurant's menu by heart.
Here's why you might love it: If interest rates rise, you're locked in at your lower rate. It's perfect for those who want a consistent monthly payment and can commit to a longer term. Plus, it's like having a financial security blanket - you know exactly what you're paying each month.
Must Read
Adjustable-Rate Mortgages: The Wild Card
Now, picture this: You're at a buffet, and you're not sure what you'll like, so you try a bit of everything. That's an adjustable-rate mortgage (ARM). The interest rate can change over time, usually every year after an initial fixed period (like 5, 7, or 10 years). It's like that buffet - you might find something you love, or you might not.
Why you might consider it: ARMs often start with a lower interest rate than fixed-rate mortgages. If you plan to move or refinance before the initial fixed period ends, an ARM could save you money. But remember, rates can go up, so it's a bit of a gamble.
 Are These 5 Common Mortgage Myths True? - C21 Relentless Moves
FHA Loans: The Helping Hand
Ever had a friend help you out when you needed it most? That's an FHA loan. Backed by the Federal Housing Administration, these loans require lower down payments and credit scores than conventional loans. They're designed to help first-time homebuyers and low-to-moderate-income families.
Why you might need it: If you're struggling to save for a down payment or your credit score isn't stellar, an FHA loan could be your key to homeownership. Just remember, you'll need to pay mortgage insurance premiums, which can add to your monthly payment.
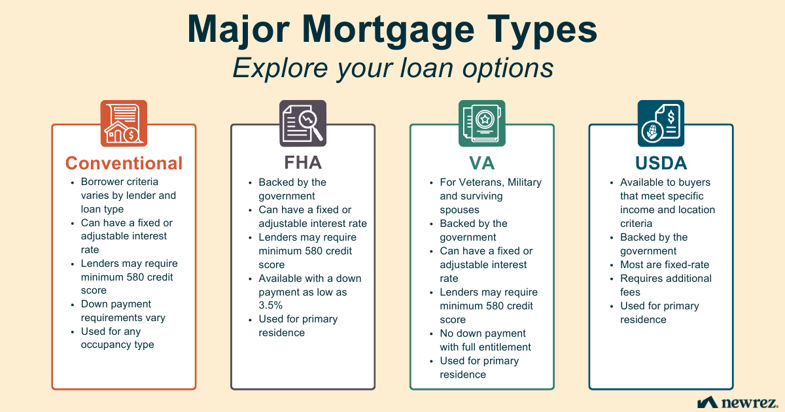 Mortgage Loans: Different Types, Terms and Structures | Newrez
So, Which Pizza Topping... I Mean, Mortgage, is Right for You?
Choosing the best loan type is like choosing a pizza topping - it's all about your personal taste and what you're in the mood for. Consider your financial situation, your plans for the future, and your comfort with risk. And remember, it's always a good idea to talk to a financial advisor or mortgage broker - they're like your personal pizza chef, helping you make the best decision for you.
In the end, the best loan type is the one that helps you achieve your dream of homeownership while giving you peace of mind. So, go forth, compare your options, and find the mortgage that's just right for you. Your perfect home is waiting!
