What Is A Good Finance Rate For A Car

Ever felt like you're in a real-life game of "Deal or No Deal" when you're at the car dealership, trying to decipher those finance rates? Fear not, car enthusiasts! We're here...
Ever felt like you're in a real-life game of "Deal or No Deal" when you're at the car dealership, trying to decipher those finance rates? Fear not, car enthusiasts! We're here to demystify those numbers and help you drive off into the sunset with a smile on your face and peace of mind in your wallet.
What's the Deal with Finance Rates?
First things first, let's talk about what a finance rate actually is. In simple terms, it's the interest rate you'll pay on your car loan. It's expressed as a percentage and is usually calculated annually. For example, if you see a rate of 4.5% APR (Annual Percentage Rate), that means you'll pay 4.5% of your loan amount in interest each year.
Now, you might be wondering, "Why should I care about this when I can just ask for a lower monthly payment?" Well, my friend, that's where the magic of compound interest comes in. A lower finance rate might mean a slightly higher monthly payment, but it could save you thousands in the long run. Think of it like investing in a high-yield savings account - the earlier you start, the more you'll have in the end.
Must Read
So, What's a Good Rate?
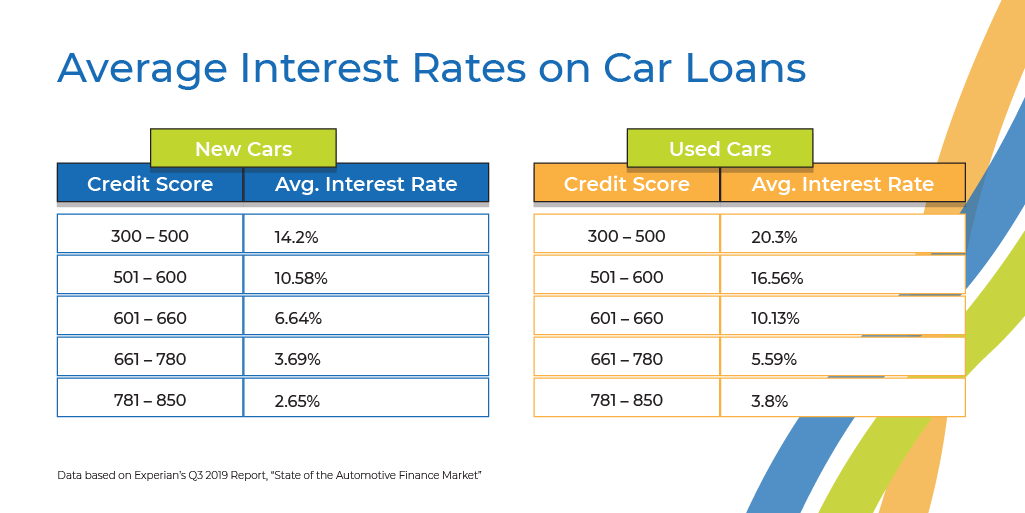
Alright, let's get down to business. What's considered a good finance rate? It depends on a few factors, like your credit score, the length of your loan, and the current market conditions. But as a general rule of thumb, anything below 6% is typically considered good for new cars, and below 10% for used cars.
To give you a better idea, let's take a look at some historical averages. According to Experian, the average new vehicle finance rate in the U.S. was around 4.5% in 2021. For used vehicles, it was about 9%. But remember, these are just averages. Your personal rate could be higher or lower depending on your financial situation.
Tips to Score a Great Rate
Now that you know what to look for, let's talk about how to get that dream rate. Here are some tips to help you negotiate like a pro:
 The Ultimate Guide to Securing the Best Auto Loan Interest Rates
- Boost Your Credit Score - The better your credit, the lower your interest rate. Pay off debts, don't max out your credit cards, and make all your payments on time. It's like training for a marathon - it takes time, but the benefits are worth it.
- Save for a Larger Down Payment - The more you put down, the less you'll need to finance, which can lower your interest rate. It's like ordering a side of fries instead of a whole extra meal - you'll save money in the long run.
- Shop Around - Don't settle for the first rate you see. Check with multiple lenders, including banks, credit unions, and online lenders. It's like trying on different outfits - you never know which one will fit you best until you try them all on.
Fun Facts and Cultural References
Did you know that the first car loan was issued in 1910 by Ford Motor Company? It was a revolutionary idea at the time, allowing people to buy cars without having to pay the full price upfront. Talk about a game-changer!
And speaking of game-changers, have you ever wondered what it would be like to have a car loan from a galaxy far, far away? In "Star Wars," the interest rates might be a little higher, considering the state of the galaxy's economy. But hey, at least you'd get to drive a speeder!
Reflection: It's All About the Journey
At the end of the day, the perfect finance rate isn't just about the numbers. It's about finding a rate that works for you and your lifestyle. It's about understanding that a car is more than just a mode of transportation - it's an investment in your future. So, whether you're cruising down the highway or just running errands around town, remember to enjoy the ride. After all, it's not about the destination - it's about the journey.
