What Do You Pay For When You Buy A House

So, you're thinking about buying a house, huh? Welcome to the big leagues, my friend! You're about to join the ranks of the responsible, the committed, and the slightly terrif...
So, you're thinking about buying a house, huh? Welcome to the big leagues, my friend! You're about to join the ranks of the responsible, the committed, and the slightly terrified (just kidding, mostly). But before you dive in, let's chat about what you're actually paying for when you sign on that dotted line.
Let's Start with the Obvious
Alright, let's get the elephant in the room out of the way - the mortgage. This is the biggie, the main event, the reason you're probably reading this. But hold onto your hats, folks, because there's more to this house-buying gig than just the monthly payments.
Down Payment: The Big Upfront Hurdle
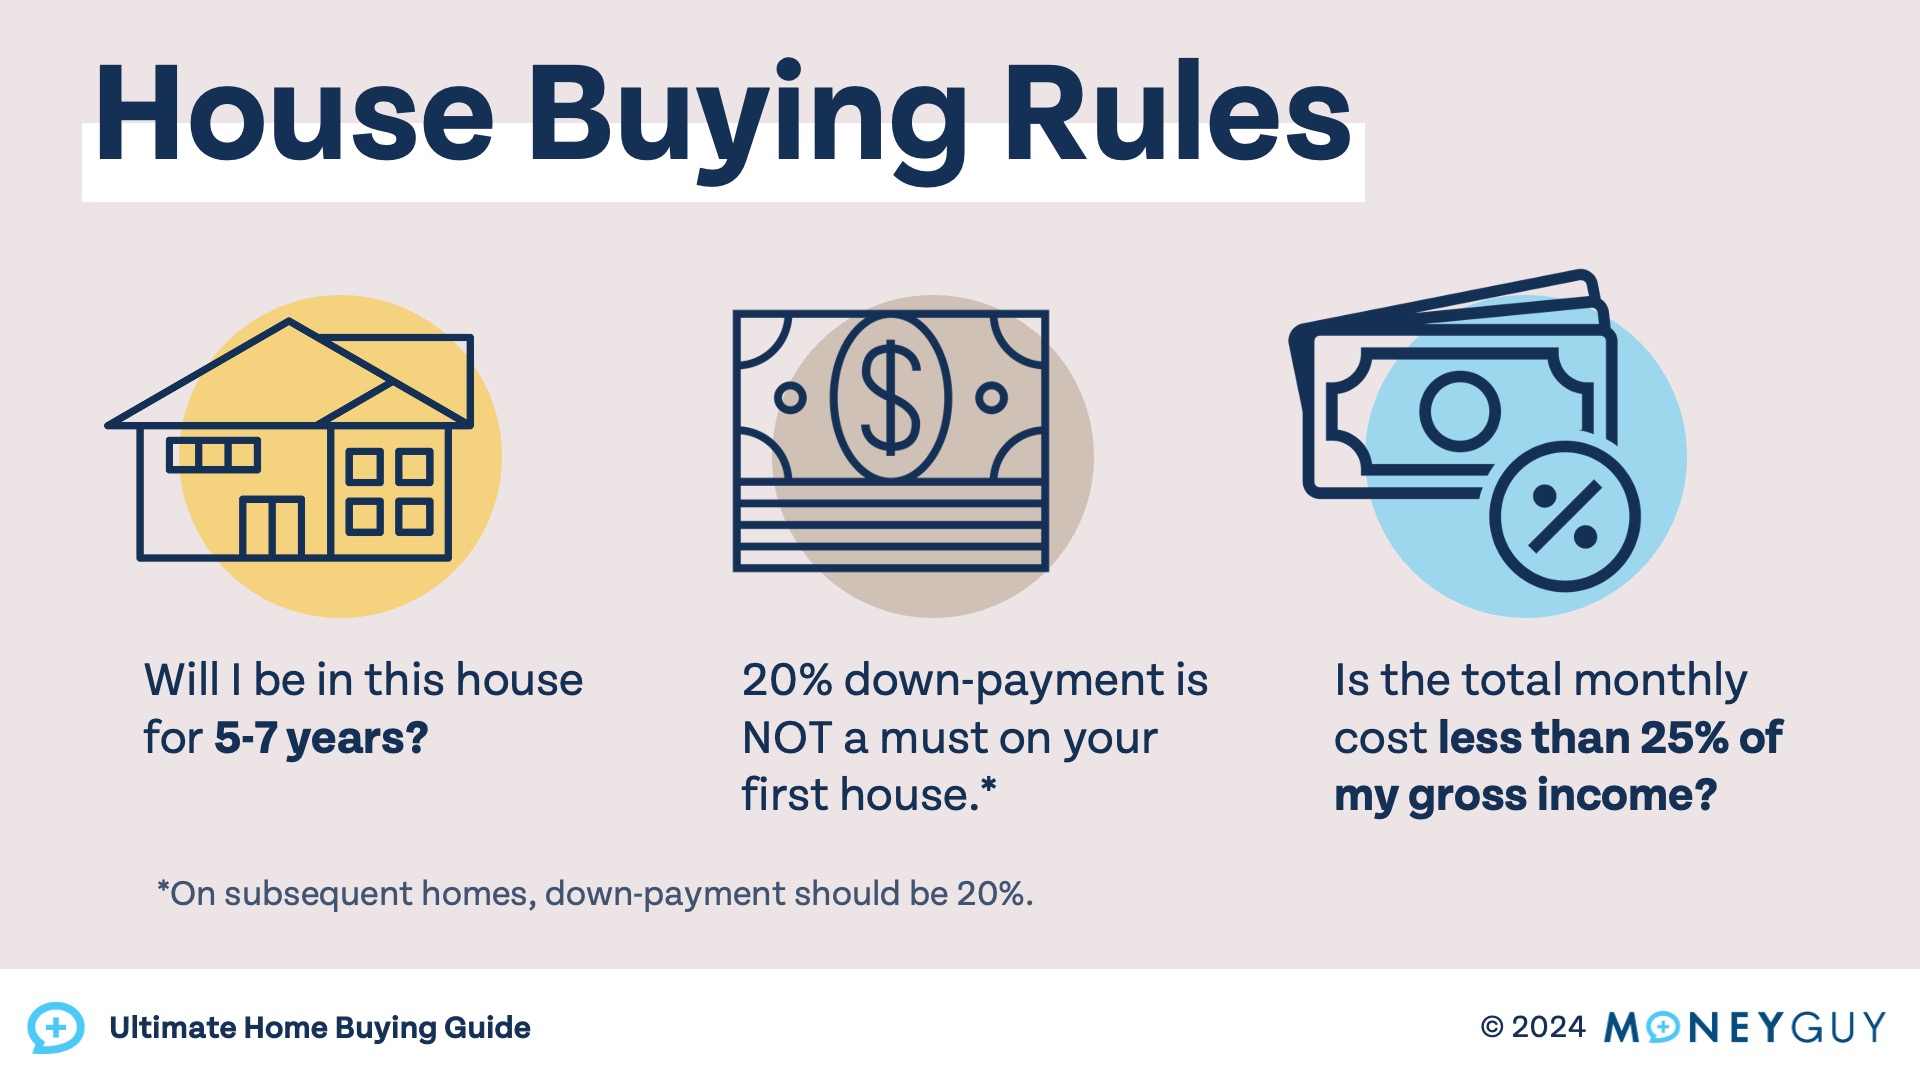
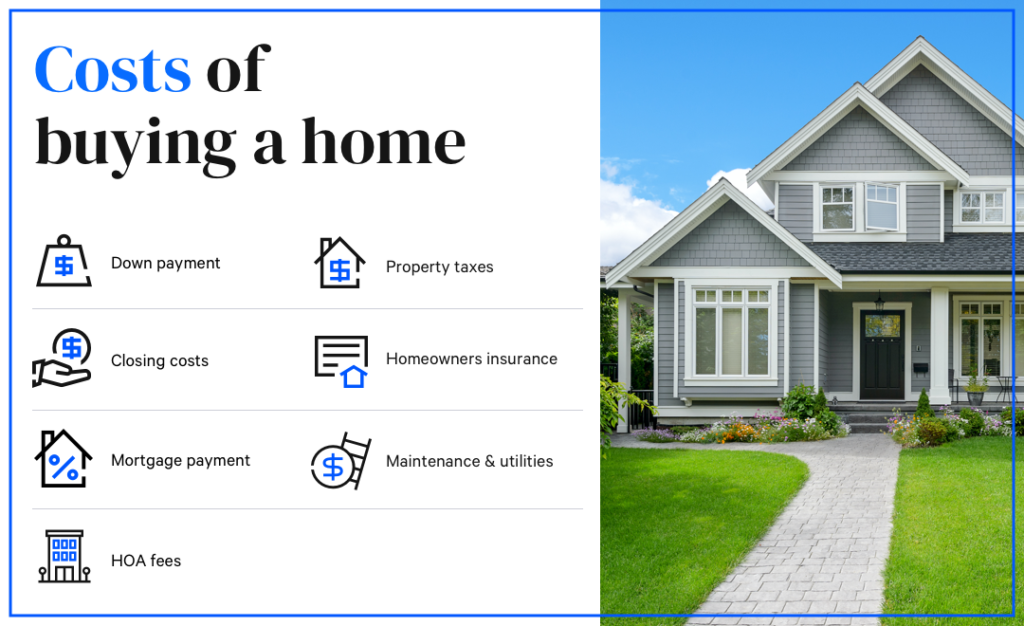
First things first, you've got to cough up some cash upfront. This is your down payment, and it's a big one. The more you put down, the less you'll pay in interest over time. But who wants to part with their hard-earned cash all at once? Not me, that's for sure. So, let's move on.
Must Read
Insurance: Protecting Your Investment
Now, you might be thinking, "I already have insurance for my car, my life, and my health. Do I really need another one?" Well, yes, yes you do. Homeowners insurance protects your new digs from all sorts of nasty surprises, like fires, floods, and burglars. And if you're putting less than 20% down, your lender will probably require you to get private mortgage insurance (PMI) as well. Fun times, right?
Property Taxes: Uncle Sam Wants His Cut
Speaking of money leaving your bank account, let's talk about property taxes. These are the fees your local government charges you for the privilege of living in their jurisdiction. They're usually calculated as a percentage of your home's value and can vary widely depending on where you live. So, do your research, folks. You don't want any nasty tax surprises.
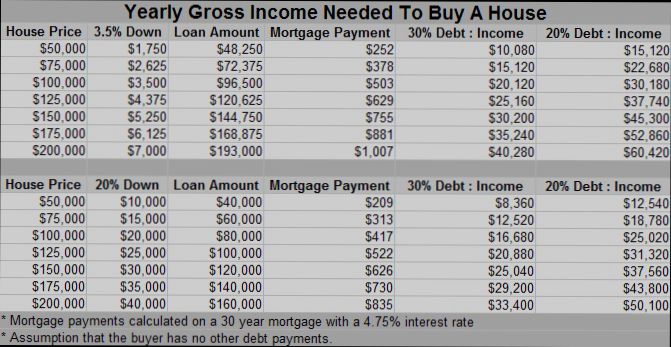 How Much Money Do You Need to Buy a House
Maintenance and Repairs: The Never-ending Story
Okay, so you've got your mortgage, your insurance, and your taxes all sorted. Now it's time to talk about the fun stuff - maintenance and repairs. Unlike renting, when something breaks in your house, it's your problem (and your dime). So, start saving for that leaky roof, the wonky plumbing, and the mysterious humming noise coming from your walls.
Utilities: The Hidden Costs
Don't forget about those pesky utility bills, either. Water, electricity, gas, internet - they all add up. And when you're a homeowner, you're responsible for all of them. So, start budgeting accordingly. And maybe invest in some energy-efficient light bulbs while you're at it. Your future self will thank you.
 How Much Money Do You Need To Buy A House? | Bankrate
Homeowners Association (HOA) Fees: The Neighborhood Watch
If you're buying a condo or a house in a planned community, you might be on the hook for HOA fees. These are the fees your neighborhood association charges to maintain common areas, enforce rules, and generally keep the neighborhood looking spiffy. They can range from a few hundred bucks a year to a small fortune, so do your homework before you buy.
Closing Costs: The Final Kick in the Pants
And finally, we have closing costs. These are the fees you pay at the end of the home buying process, when you officially become a homeowner. They can include loan origination fees, appraisal fees, title search fees, and more. They're usually a few thousand dollars, so don't be caught off guard.
But Hey, It's Worth It!
Okay, so buying a house isn't exactly cheap. But you know what? It's totally worth it. There's something incredibly satisfying about having a place to call your own, a space to fill with your stuff and your memories. So, chin up, my friend. You're about to embark on an amazing journey. And who knows? Maybe one day you'll look back on this article and laugh at how naive you were. But for now, happy house hunting!
