Taking Tax Free Lump Sum From Pension

Hey there, pension pals! Ever found yourself daydreaming about that magical day when you can finally say sayonara to the 9-5 grind and hello to a life of leisure? Well, let me...
Hey there, pension pals! Ever found yourself daydreaming about that magical day when you can finally say sayonara to the 9-5 grind and hello to a life of leisure? Well, let me tell you, taking a tax-free lump sum from your pension can be like finding a pot of gold at the end of your career rainbow. But hold your horses, let's not get ahead of ourselves. First, we gotta understand what we're dealing with here.
What's the Deal with Pensions?
Alright, so pensions, they're like the grown-up version of your piggy bank. You've been chucking money into it for years, and now it's all grown up and ready to help you retire in style. But here's the thing, not all pensions are created equal. Some are defined benefit, some are defined contribution, and some are a mix of both. It's like trying to choose between chocolate, vanilla, or strawberry ice cream, but with less brain freeze and more financial jargon.
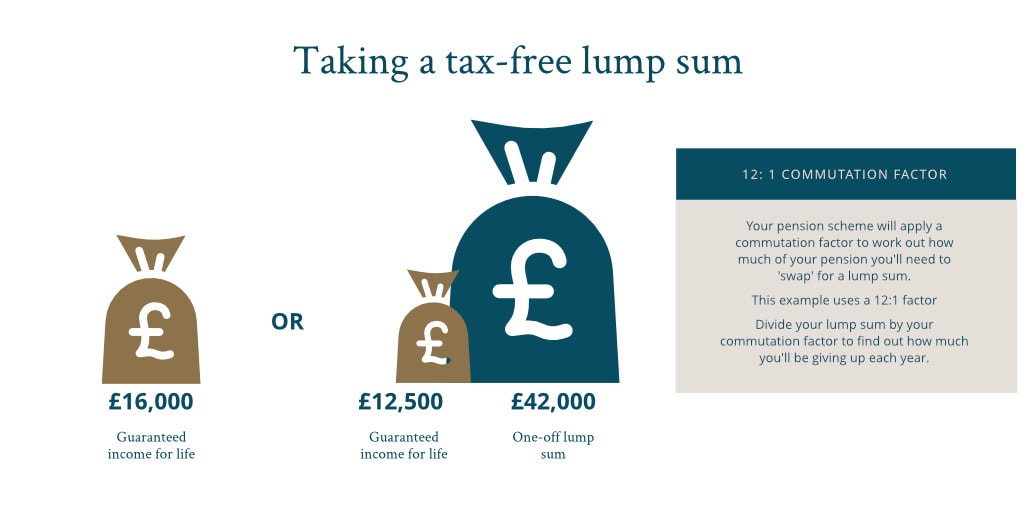
Now, if you're lucky enough to have a defined benefit pension, you might be thinking, "Great! I know exactly what I'm getting." And you'd be right, sort of. You'll get a guaranteed income for life, but it might not be as big as you'd hoped. That's where the tax-free lump sum comes in. It's like the cherry on top of your pension sundae.
Must Read
Tax-Free Lump Sum: The Cherry on Top
Imagine this: you've worked your tail off for decades, and now the government is going to give you a big ol' chunk of change, tax-free. Sounds too good to be true, right? Well, it's not. It's called a tax-free lump sum, and it's a beautiful thing. But here's the catch - it's not for everyone.
You see, not all pensions offer a tax-free lump sum. And even if yours does, there are rules. You usually have to be at least 55, and you can't take the whole thing at once. It's like when you were a kid and your mom made you wait until after dinner to have dessert. You might not like it, but you gotta do it.
But wait, there's more! The amount you can take tax-free is limited. It's called the 'lifetime allowance', and it's currently set at £1,073,100. That's a lot of zeros, I know. But don't worry, most people won't have to worry about this. It's like having a speed limit on your pension. You can go fast, but not too fast.
How Much Can You Take?
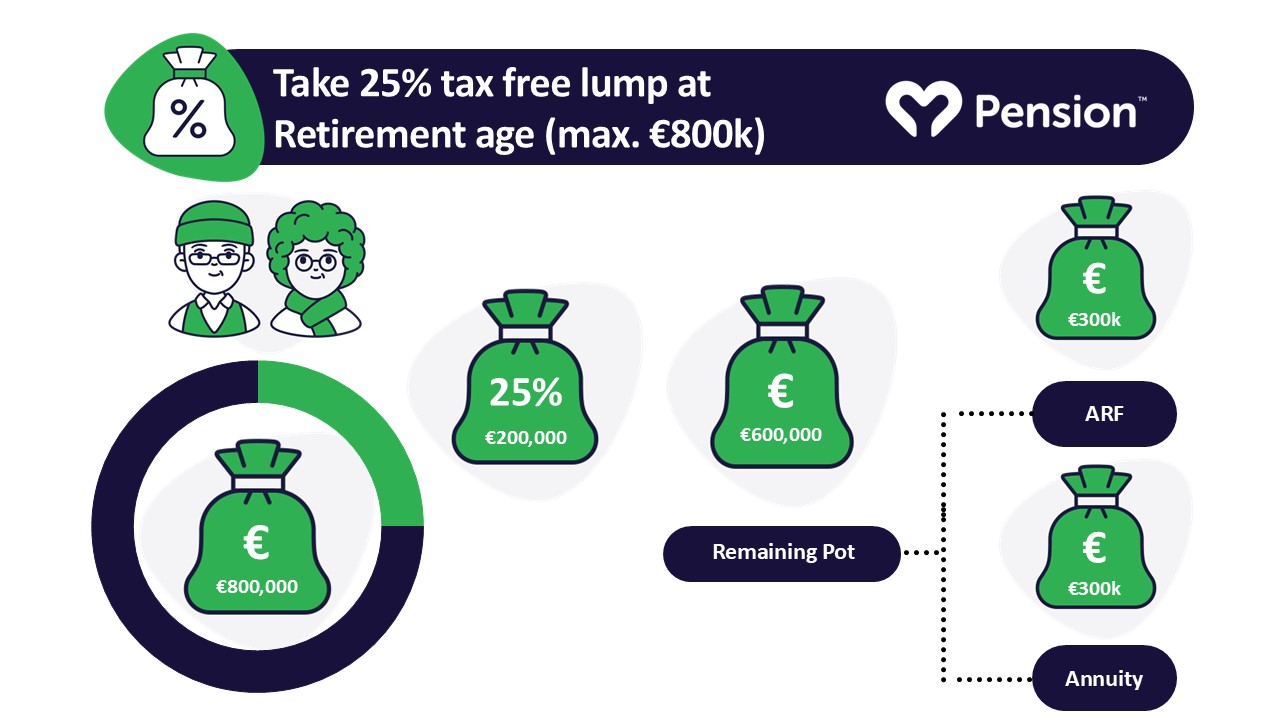
So, how much can you take as a tax-free lump sum? Well, that depends on your pension pot and your age. The general rule of thumb is that you can take 25% of your pension pot as a tax-free lump sum. But remember, that's before any tax-free cash you've already taken.
Let's say you've got a pension pot of £100,000 and you're 55. You could take £25,000 as a tax-free lump sum. Not bad, huh? But hold on to your hats, because there's more to consider.
What About the Rest?
So, you've taken your tax-free lump sum. Now what? Well, you've got a few options. You can buy an annuity, which is like a special insurance policy that gives you a guaranteed income for life. Or you can go down the flexible access route and take your pension as and when you need it. It's like choosing between a steady paycheck or a flexible freelance lifestyle.
But here's the thing, once you've taken your tax-free lump sum, any withdrawals you make after that will be taxed as income. So, you'll need to think about how much you take and when. It's like playing a high-stakes game of chess, but with less checkmates and more tax brackets.
 Final Salary Pension rules 2021: What's changed
Should You Take a Tax-Free Lump Sum?
Now, you might be thinking, "This all sounds great! I should definitely take a tax-free lump sum!" And you might be right. But here's the thing, it's not a one-size-fits-all kind of deal. It depends on your personal circumstances, your financial goals, and your risk tolerance.
For example, if you've got a big mortgage to pay off or you're planning a round-the-world trip, a tax-free lump sum could be just the ticket. But if you're not sure what you'll do with the money or you're worried about running out of cash in retirement, it might not be the best idea.
That's why it's always a good idea to talk to a financial advisor. They can help you weigh up the pros and cons, crunch the numbers, and make a plan that's right for you. It's like having a personal trainer for your pension. They'll help you work out the kinks and get you in shape for retirement.
So, What's the Verdict?
Alright, so we've talked a lot about tax-free lump sums, and I hope I've answered some of your burning questions. But here's the thing, taking a tax-free lump sum isn't a decision to be taken lightly. It's a big deal, and it's going to affect your retirement in a big way.
But hey, don't let that scare you off. Retirement should be an exciting new chapter in your life, not something to be feared. And with the right planning and the right advice, you can make the most of your pension and live the life you've always dreamed of.
So, go on, grab that pot of gold at the end of your career rainbow. You've earned it. Just remember to do your homework first. Your future self will thank you.
And there you have it, folks. The lowdown on tax-free lump sums. I hope you found this as fun to read as I did to write. Now go forth and conquer your pensions!
