Money Guy How Much House Can I Afford

Ever wondered, "How much house can I afford?" It's like trying to figure out how many pizzas you can eat, right? Too much, and you're in trouble. Too little, and you're still...
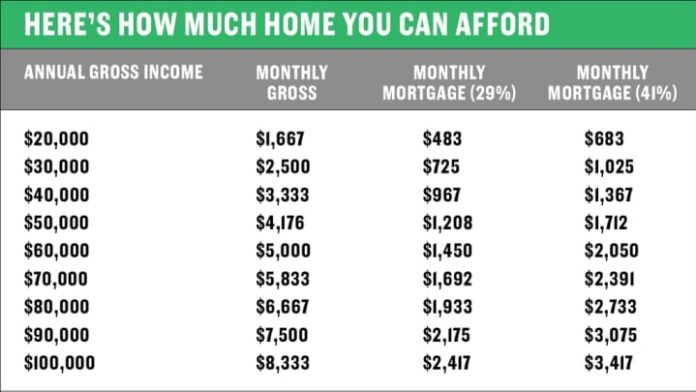
Ever wondered, "How much house can I afford?" It's like trying to figure out how many pizzas you can eat, right? Too much, and you're in trouble. Too little, and you're still hungry. So, let's dive into this, nice and easy.
First things first, what's your income?
Imagine your income is like your pizza budget. If you make $50,000 a year, that's like having $4,167 a month to spend on pizzas. But remember, you've got other stuff to buy too, like ingredients for salad (because balance, right?).
Enter the 28/36 rule
This is like your pizza-eating strategy. It says you should spend no more than 28% of your gross monthly income on housing. So, if you make $4,167 a month, you should spend around $1,167 on housing. But wait, there's more!
Must Read
The 28/36 rule also says you shouldn't spend more than 36% of your income on debts, including your mortgage. So, that's another $1,500 you've got to play with. Suddenly, that pizza budget looks a bit bigger, huh?
Now, let's talk about savings
You wouldn't want to eat pizza every day and never save for a rainy day, right? The same goes for housing. You should aim to save around 20% of your income. So, if you make $4,167 a month, that's $833 you're putting aside.
This is where it gets interesting. Because, if you're saving 20% and spending 28% on housing, you've got a bit of wiggle room. You might be able to afford a bit more house than you thought. But remember, it's all about balance.
What about the house itself?
So, you've figured out how much you can afford. Now, let's talk about the house. A good rule of thumb is that your house shouldn't be more than 2.5 to 3 times your annual salary. So, if you make $50,000 a year, your house should be around $125,000 to $150,000.
 Magic Pmi Calculator
But remember, this is just a guide. It's like saying you should eat three slices of pizza. But what if you're really hungry? Or what if you've got a big appetite? It's all about what works for you.
So, how much house can you afford?
Well, that depends on you. It depends on your income, your savings, your debts, and your appetite for risk. It's like trying to figure out how many pizzas you can eat. You've got to listen to your body, and you've got to listen to your budget.
And remember, it's not just about the house. It's about the life you want to live. Do you want to travel? Do you want to start a business? Do you want to eat pizza every day? (Hey, no judgment here.) The house you can afford is the one that fits into your life, not the other way around.
So, go ahead. Figure out your budget. Talk to a lender. And most importantly, have fun. Because buying a house is a big deal. It's like ordering a really, really big pizza. And who doesn't love a big pizza?
