Is Interest Only Mortgage A Good Idea

Should You Dive In or Tread Water? The Interest-Only Mortgage Dilemma Ever felt like you've got a million things on your mind, but the one thing you really should be thinking...
Should You Dive In or Tread Water? The Interest-Only Mortgage Dilemma
Ever felt like you've got a million things on your mind, but the one thing you really should be thinking about is that pesky mortgage? Yeah, we've all been there. So, let's chat about something that's got a lot of folks scratching their heads - interest-only mortgages. Is it a dream come true or a wolf in sheep's clothing? Let's find out!
What's the Deal with Interest-Only?
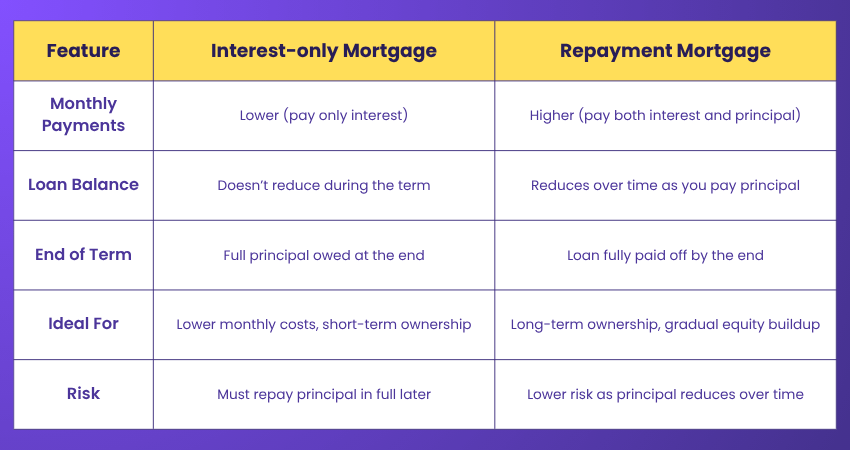
Imagine you're at your favorite coffee shop. You order a fancy latte, but you only pay for the milk, coffee, and a touch of foam - none of that expensive syrup or whipped cream. That's kind of what an interest-only mortgage is like. You're only paying for the interest part of your loan, not the actual amount you borrowed. Sounds like a sweet deal, huh?
But hold on to your hats, folks, because it's not all sunshine and rainbows. While you're sipping on that sweet, sweet coffee (or tea, no judgment here), let's talk about the elephant in the room - you're not actually paying off your loan. It's like ordering that fancy latte every day, but never chipping away at the cost of the espresso machine. You're just... treading water.
Must Read
So, Why Would Anyone Do This?
Well, there are a few reasons why some people might consider an interest-only mortgage. Maybe you're a first-time buyer and you're struggling to save for a deposit. Or perhaps you're self-employed and your income fluctuates like a rollercoaster. Maybe you just want to keep your monthly repayments as low as possible so you can splurge on avocado toast (hey, no shame in our brunch game!).
But remember, just because something's tempting, doesn't mean it's the best choice. And an interest-only mortgage is like that box of donuts in the office - it might look delicious, but it's probably not the healthiest option.
Let's Talk Numbers
Alright, let's get real for a sec. Say you've got a $200,000 mortgage at a 3% interest rate. With an interest-only mortgage, you'd be paying around $6,000 a year in interest. Not too shabby, right?
But here's the thing - after 10 years, you'd still owe the full $200,000. Zilch. Nada. Nothing. Meanwhile, your neighbor with a repayment mortgage would have paid off over $100,000 of their loan. Ouch.
But What If...?
Now, you might be thinking, "But what if I can afford to pay off some of the loan? What if I sell the house in a few years? What if I win the lottery?"
 Should I release cash from my home to become a buy-to-let landlord
Well, here's the thing - life's full of uncertainties. And while it's great to be optimistic, it's also important to be realistic. What if you don't win the lottery? What if you lose your job? What if interest rates go up?
An interest-only mortgage can be a lifesaver in certain situations, but it's a bit like playing with fire. It might be fun for a while, but it could also leave you with some nasty burns.
So, Is It Worth It?
At the end of the day, it depends on your personal circumstances. If you're sure you can afford to pay off some of your loan, or if you know you'll be selling up soon, it might be worth considering. But if you're just looking to keep your monthly repayments as low as possible, it might be a risky game to play.
Remember, an interest-only mortgage is like that shiny new toy you just have to have. It might seem like the best thing ever at first, but it could also end up gathering dust in the corner. It's all about weighing up the pros and cons, and making a decision that's right for you.
And hey, if you're still not sure, that's okay too. It's always better to take your time and make an informed decision than to rush in and regret it later. After all, this is your home we're talking about - it's not something you want to mess around with.
So, what do you think? Is an interest-only mortgage the dream or the nightmare? The choice is yours, folks. Now go forth and make some informed decisions!
