Ideal Cash Reserves For Buying New Home

So, I was chatting with my buddy, Jake, the other day. He's been saving up to buy his first home, and he's got that excited, slightly terrified look in his eyes. You know the...
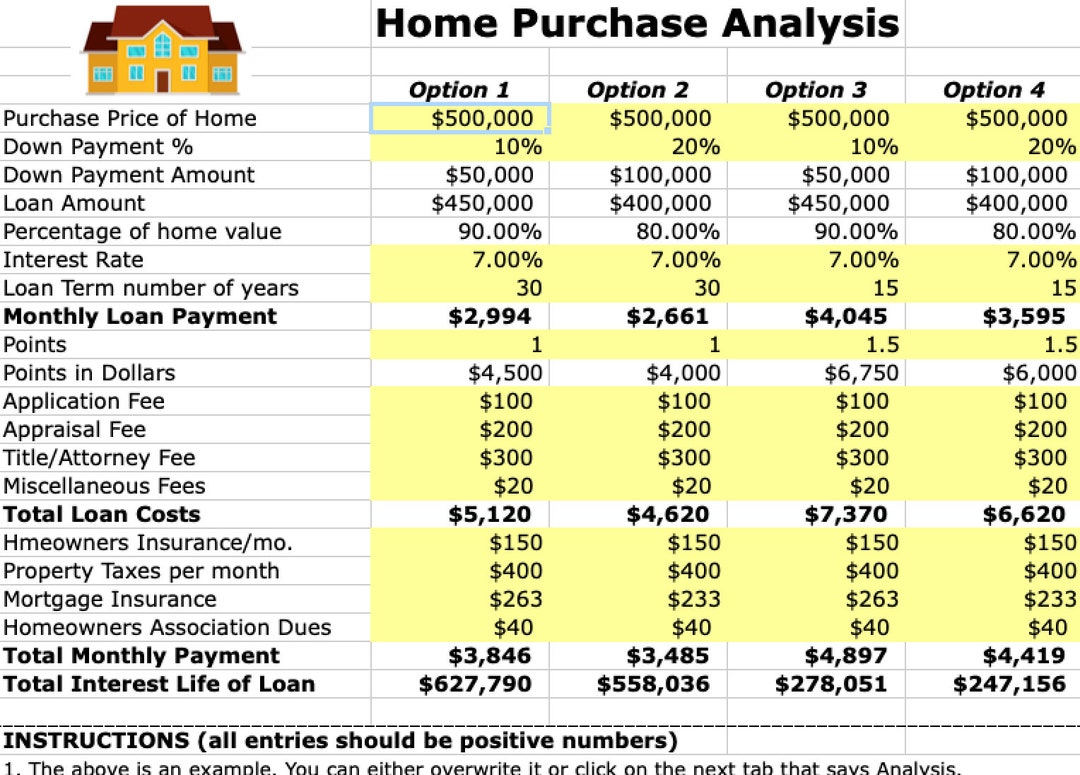
So, I was chatting with my buddy, Jake, the other day. He's been saving up to buy his first home, and he's got that excited, slightly terrified look in his eyes. You know the one, right? The 'Am I doing the right thing?' look. Anyway, we got talking about how much cash he should have stashed away before he takes the plunge.
Now, I'm no financial advisor, but I've been around the block a few times, and I've seen folks make some mistakes when it comes to cash reserves. So, I thought I'd share a few pointers with you, dear reader, about how much cash you should have squirreled away before you buy that dream home.
Why Cash Reserves Matter
First things first, why do cash reserves matter? Well, let me put it this way - imagine you're a squirrel (bear with me here). You've found the perfect nut - I mean, home - but you've only got enough nuts - I mean, cash - to buy it. No problem, right? Wrong!
Must Read
You see, life has a way of throwing unexpected expenses at you. Like that time I found a leak in my roof just after I'd bought my place. Suddenly, I needed a whole bunch of cash to fix it. If I hadn't had some cash reserves, I'd have been in a real pickle.
So, How Much Cash Should You Have?
Alright, enough with the squirrel metaphors. Let's talk numbers. A common rule of thumb is to have 3-6 months' worth of living expenses saved up. But when it comes to buying a home, you might want to aim a bit higher. Here's why:
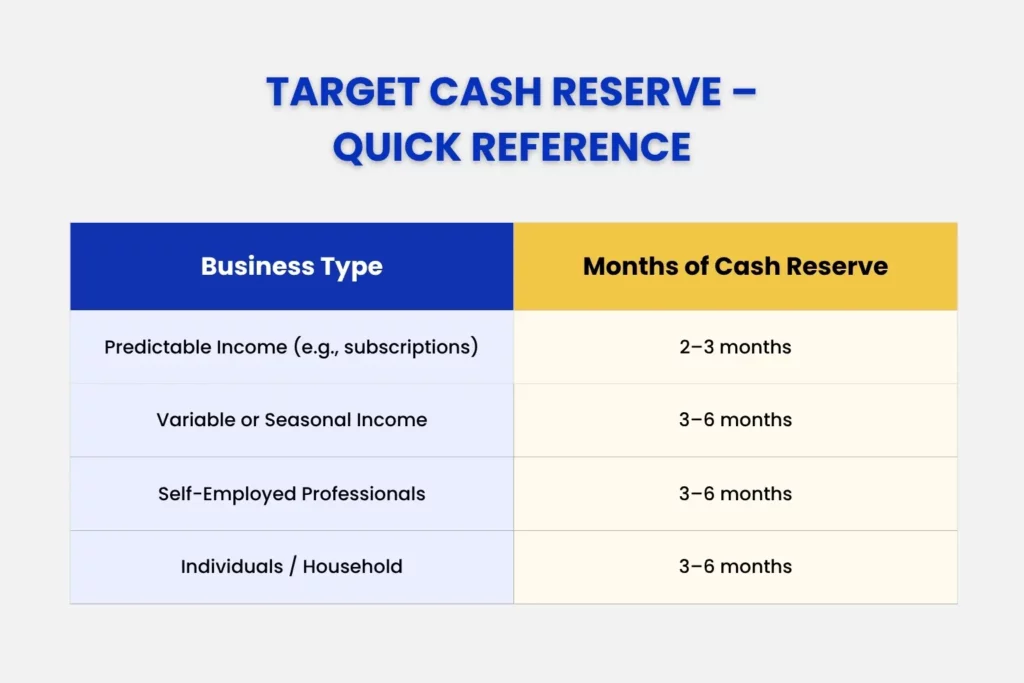 Cash Reserve Account: Complete UK 101 Guide
- Down Payment: Most lenders require a down payment of at least 3% to 20% of the home's value. The more you put down, the lower your monthly payments and the better your interest rate.
- Closing Costs: These can range from 2% to 5% of the home's value. They include fees for things like loan origination, appraisal, and title search.
- Emergency Fund: Remember our leaky roof friend from earlier? Having a healthy emergency fund can help you cover unexpected repairs or other expenses that come up after you buy your home.
So, how much is that in real terms? Well, it depends on your income and expenses, but as a rough guide, you might want to aim for 10% to 20% of the home's value in cash reserves. That should give you enough for the down payment, closing costs, and a healthy emergency fund.
But What About Debt?
Before you start saving like there's no tomorrow, it's worth thinking about your debt situation. If you've got high-interest debt, like credit card debt, it might make sense to pay that off first. After all, the interest you're paying on that debt is likely higher than the interest you'd earn on your savings.
Plus, having less debt can improve your debt-to-income ratio, which can help you qualify for a better mortgage. Win-win, right?
 Building a Balanced Portfolio: The Role of Cash Reserves - WealthGen
Final Thoughts
So there you have it, folks. Having healthy cash reserves is crucial when you're buying a home. It can help you make a bigger down payment, cover closing costs, and give you peace of mind knowing you're covered if something goes wrong.
But remember, everyone's situation is different. So, it's always a good idea to talk to a financial advisor or a mortgage broker before you make any big decisions. They can help you figure out what's right for you.
And as for Jake? Well, he's still saving up, but he's feeling a lot more confident about his cash reserves now. Maybe this article will help you feel the same way. Happy saving!
