How To Qualify For A Home Loan

So, You're Thinking About a Home Loan, Huh? Alright, let's dive in! You're here because you're curious about home loans, right? Maybe you're dreaming of that perfect little h...

So, You're Thinking About a Home Loan, Huh?
Alright, let's dive in! You're here because you're curious about home loans, right? Maybe you're dreaming of that perfect little house with a white picket fence, or perhaps you're just wondering what all the fuss is about. Either way, you've come to the right place.
First Things First: What's a Home Loan?
In simple terms, a home loan is like a big hug from your bank. They give you money to buy a house, and you promise to pay them back with interest. It's a win-win, really. You get your dream home, and they make a little profit. Pretty neat, huh?
But before you start imagining the perfect housewarming party, there are a few things you should know. Like, how do you qualify for this fancy-sounding loan? Let's find out!
Must Read
Credit Score: The Magic Number
Imagine your credit score as your personal cheerleader at a football game. The better it is, the louder it cheers for you. Lenders love a good cheerleader, so they want to see a score of at least 620. But if you want the best deals, aim for 740 or above. That's like having a squad of cheerleaders!
But what if your cheerleader is a bit lackluster? Don't worry, you can always work on improving your score. Pay your bills on time, keep your credit utilization low, and avoid opening too many new credit accounts. Your cheerleader will thank you!
Debt-to-Income Ratio: The Balancing Act
Now, let's talk about your debt-to-income ratio. This is like trying to balance a bunch of plates on a stick - it's all about finding the right balance. Lenders want to see that you're not drowning in debt. A good rule of thumb is to keep your debt-to-income ratio below 43%.
Think of it this way: if your monthly income is like a big, delicious pizza, you don't want your debts to eat up more than 43% of it. Leave some slices for your home loan payment, would ya?
Down Payment: The Bigger, The Better
You know how sometimes you have to put money in a vending machine before it gives you a snack? A down payment is kind of like that. It's the money you put down upfront when you buy a house. The more you put down, the less you'll have to borrow, and the less interest you'll pay.
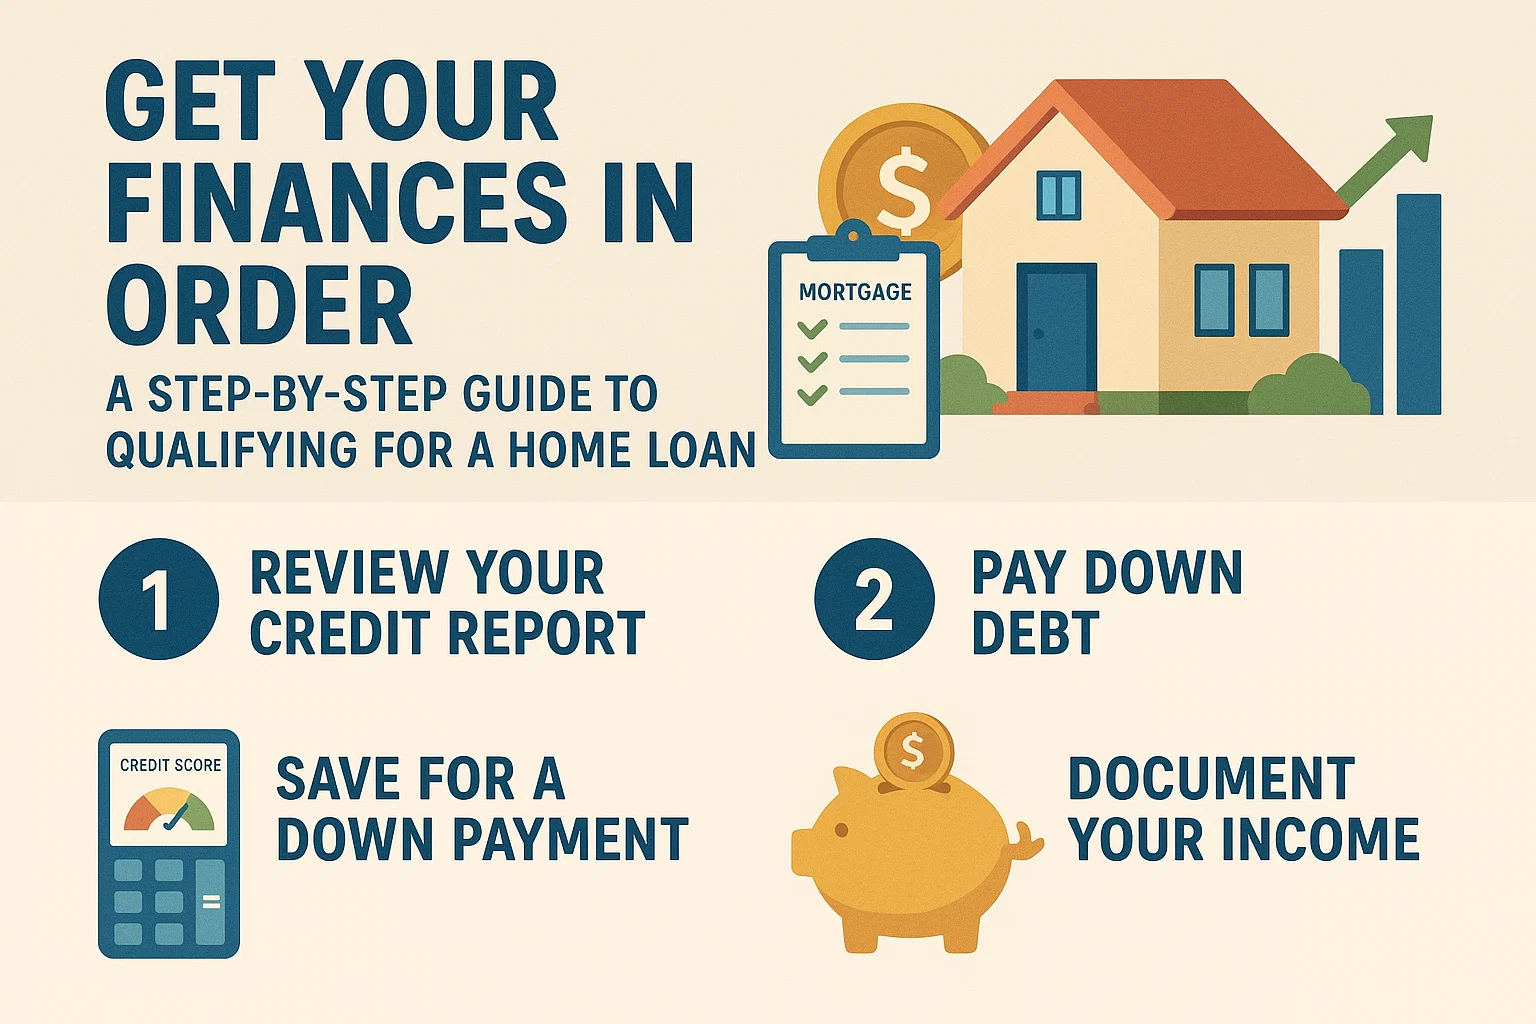 Get Your Finances in Order: A Step-by-Step Guide to Qualifying for a
Ideally, you want to put down at least 20% of the home's value. That's like getting a free snack from the vending machine! But if you can't swing that, don't worry. There are loans that require less, but you might have to pay for private mortgage insurance (PMI). It's like buying a snack and having to pay extra for the fancy wrapping.
Income and Employment: The Steady Gig
Lenders want to see that you have a steady income and a stable job. They want to know that you'll be able to make those monthly payments without breaking a sweat. So, if you're self-employed or have an irregular income, you might have to work a little harder to prove your financial stability.
Think of it like this: if you were a plant, lenders want to see that you're well-watered and thriving. They don't want to take a chance on a plant that might wilt at the first sign of drought.
Now, Let's Talk About the Fun Stuff: The Loan Types!
There are different types of home loans, each with its own perks. It's like choosing a flavor of ice cream - there's something for everyone!
FHA loans are like the kid's menu at a restaurant. They're designed for people with lower incomes or not-so-great credit. They require a smaller down payment and have less strict qualification requirements.
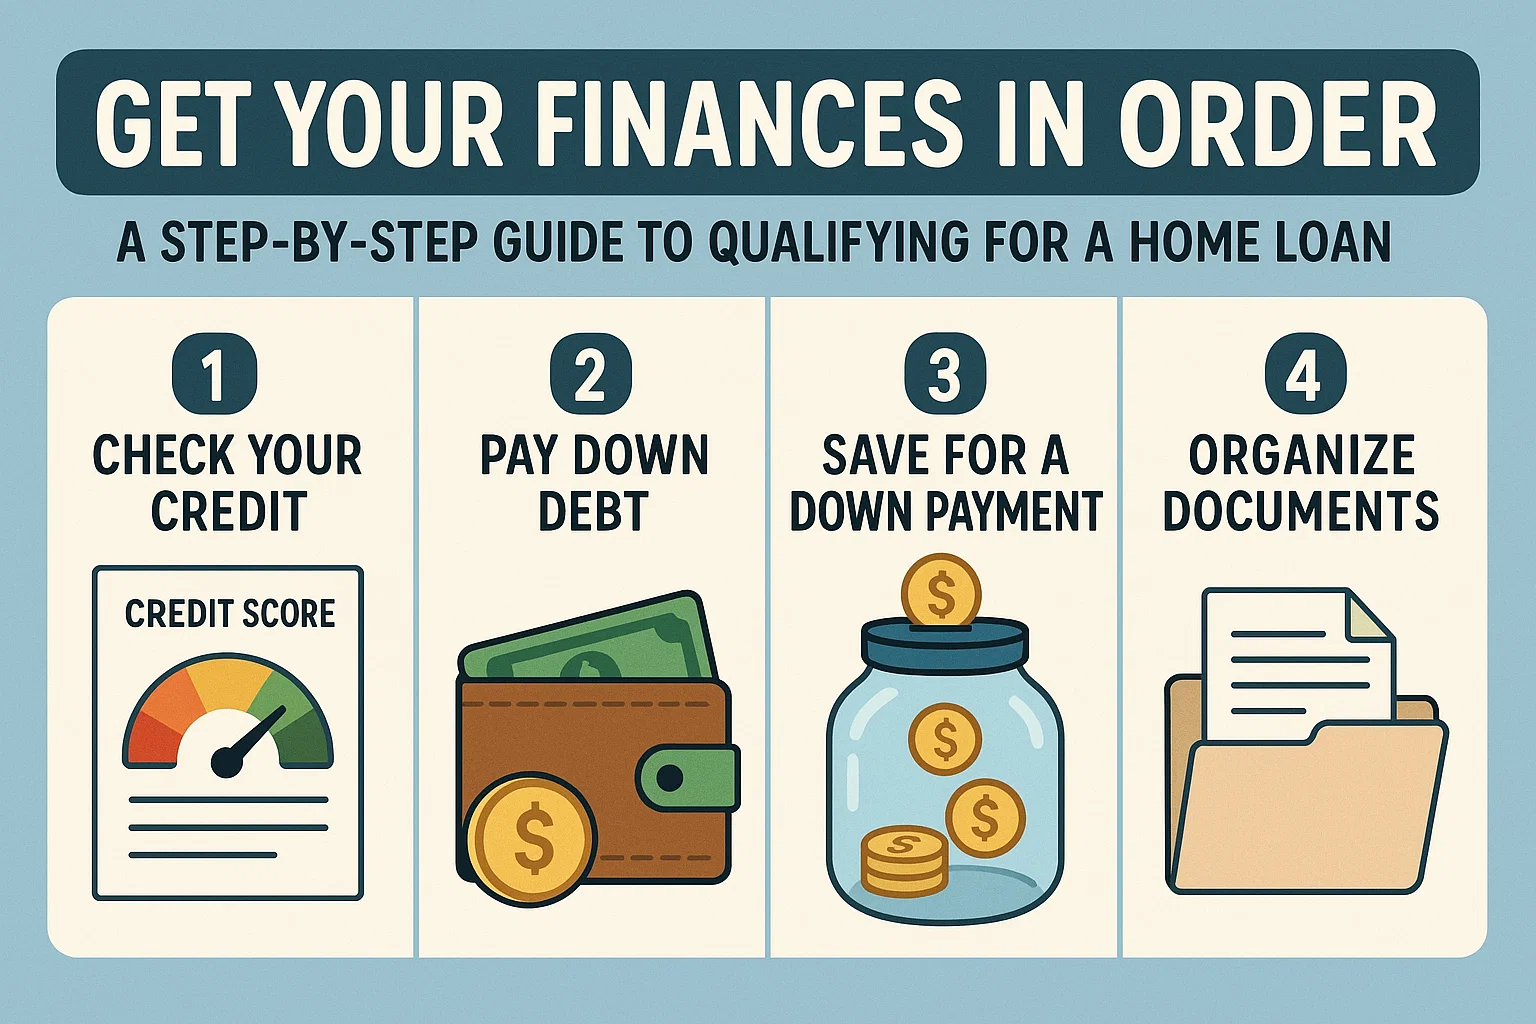 Get Your Finances in Order: A Step-by-Step Guide to Qualifying for a
VA loans are like a special meal for veterans. They offer flexible terms and don't require a down payment. It's the bank's way of saying 'thank you' for your service.
USDA loans are like a farm-to-table meal. They're designed for people living in rural areas and have income limits. They don't require a down payment, but you'll need to live in a qualifying area.
Conventional loans are like the adult menu. They're the most common type of loan and have more strict qualification requirements. But if you have good credit and a steady income, they could be the perfect fit.
So, Are You Ready to Take the Plunge?
Qualifying for a home loan is like training for a marathon. It takes time, preparation, and a whole lot of determination. But once you cross that finish line and get the keys to your new home, it's all worth it.
So, what are you waiting for? Start lacing up those running shoes and get ready to qualify for that home loan. Your dream home is just around the corner!
