How To Pick The Right Credit Card

So, there I was, standing in line at the coffee shop, when the barista asked, "Cash or card?" I fumbled through my wallet, pulling out a tangled mess of plastic. I had five cr...
So, there I was, standing in line at the coffee shop, when the barista asked, "Cash or card?" I fumbled through my wallet, pulling out a tangled mess of plastic. I had five credit cards, each with its own perks, but I couldn't remember which one was best for coffee purchases. That's when it hit me - I needed a credit card intervention. And maybe you do too.
First things first: Know thyself
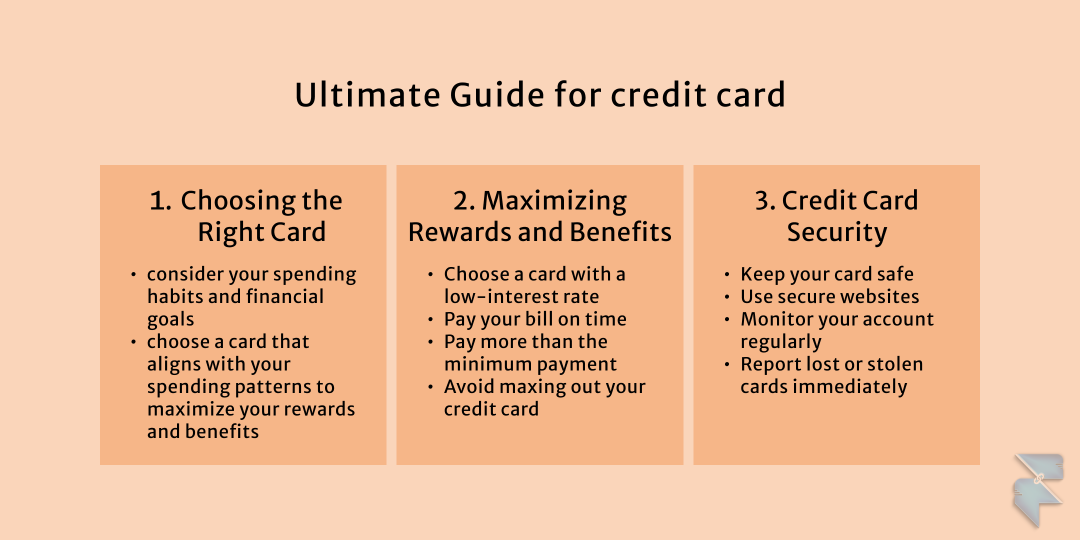
Before you start swiping, you need to understand your spending habits. Are you a coffee connoisseur like me, or do you prefer to dine out? Maybe you're a travel bug, always on the go. Knowing where your money goes will help you pick a card that rewards you for your spending.
For instance, if you're a frequent flyer, you might want a card that offers airline miles. But if you're more of a foodie, a card that gives cash back on dining could be your best bet. And if you're like me, a coffee addict, well, you get the picture.
Must Read
Welcome bonuses: The cherry on top
Many credit cards offer sign-up bonuses, like a chunk of cash or a bunch of points, just for spending a certain amount within the first few months. These can be a great way to start racking up rewards, but remember, you usually have to spend a lot to get them. So, make sure it's a bonus that fits your spending habits.
For example, if a card offers a bonus for spending $3,000 in the first three months, but you only spend $500 a month, it might not be worth it. But if you're planning a big purchase or have a lot of expenses coming up, it could be a sweet deal.
Interest rates: The fine print
Now, let's talk about the not-so-fun stuff - interest rates. If you pay off your balance in full each month, you don't have to worry about this. But if you carry a balance, the interest rate is crucial.
 How to Choose the Right Credit Card for You - YouTube
Cards with rewards often have higher interest rates, so if you think you might carry a balance, look for a card with a lower rate. Some cards even offer 0% introductory APRs, which can be a lifesaver if you're planning a big purchase.
Fees: The hidden costs
Before you sign on the dotted line, make sure to check the fees. Some cards have annual fees, which can be worth it if you earn enough rewards to offset the cost. But if you're not a big spender, a card with no annual fee might be a better fit.
Also, watch out for foreign transaction fees if you travel internationally. Some cards waive these fees, but others charge a percentage of each purchase. And don't forget to check the late fee - it's there to remind you to pay on time!
Perks: The icing on the cake
Finally, let's talk about the fun stuff - perks. Some cards offer travel insurance, extended warranties, or even access to exclusive events. These can be great benefits, but they're not worth it if the card's interest rate or fees cancel them out.
 Pick One Card Pick A Card From My NEW Golden Future Oracle Cards
For example, if you love to travel, a card that offers travel insurance could save you a lot of money if something goes wrong. But if you never leave the country, it's not going to do you much good.
So, which card is right for you?
Well, that depends on you. Are you a coffee lover like me, or do you have different spending habits? Do you travel a lot, or do you prefer to stay closer to home? The right card is the one that rewards you for the way you live your life.
So, take a look at your spending habits, consider the welcome bonuses, interest rates, fees, and perks, and pick the card that fits you best. And next time you're standing in line at the coffee shop, you'll know exactly which card to use.
Happy spending!
