How To Go About Getting A Mortgage

Alright, folks, let's dive into the big, scary world of mortgages, shall we? Don't worry, I promise we'll keep it fun and light. After all, we're talking about the key to your...
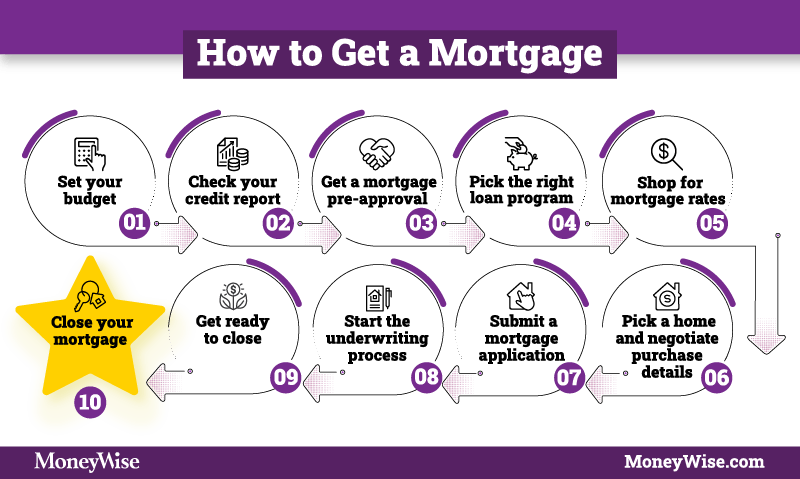
Alright, folks, let's dive into the big, scary world of mortgages, shall we? Don't worry, I promise we'll keep it fun and light. After all, we're talking about the key to your dream home, not a trip to the dentist!
First Things First: Check Your Credit Score
Before you even think about dipping your toes into the mortgage pool, you need to know where you stand. Your credit score is like your financial report card, and lenders want to see a good one. So, grab a cuppa, sit down, and check your score. Don't have it? No worries, you can get it for free from sites like AnnualCreditReport.com.
How Much Can You Bite Off?
Now, let's talk money. How much can you afford to borrow? Use an online mortgage calculator to get an idea. Remember, just because a lender says you can borrow $300,000 doesn't mean you should. Consider your lifestyle, your savings, and your sanity. You don't want to be house-rich and cash-poor, right?
Must Read
Types of Mortgages: Pick Your Flavor
Mortgages come in all shapes and sizes. There's the classic 30-year fixed-rate, the 15-year fixed-rate, and the 5/1 adjustable-rate. Then there are FHA loans, VA loans, USDA loans, jumbo loans... it's like an ice cream parlor, but with less sprinkles and more paperwork. Do your research, talk to lenders, and find the one that suits your taste.
Gather Your Docs: It's Like Tax Season, But Worse
Time to play detective. You'll need to gather all sorts of documents: pay stubs, tax returns, bank statements, investment account statements, your birth certificate, your firstborn child... okay, maybe not that last one. But you get the idea. Lenders want to know you're a safe bet.
 Mortgage Guides & Advice | Your Mortgage Expert
Pre-approval: The Goldilocks Stage
You're not quite ready to start house hunting just yet, but you're getting close. A pre-approval letter from a lender shows sellers you're serious. It's like being in the 'considering' stage of a relationship. You're not fully committed, but you're definitely interested.
House Hunting: The Fun Part!
Now comes the fun part. You get to drive around, look at pretty houses, and imagine your life in them. It's like playing 'house' as a kid, but with more expensive toys. Just remember to stay within your budget. It's tempting to fall in love with a house that's out of your league, but trust me, it's like dating someone who's only interested in your money. It never ends well.
Making an Offer: It's Like Asking Someone to Prom
You've found 'the one'. Now it's time to make an offer. It's like asking someone to prom, but with more lawyers involved. You'll need to decide on a price, and whether to include contingencies. It's a dance, folks. A delicate, high-stakes dance.
 Understanding the Six Steps of the Mortgage Process
The Home Inspection: When Your Dream House Might Turn into a Nightmare
Before you close the deal, you'll want to get a home inspection. It's like getting a thorough check-up before you commit to a lifetime with this house. It might find hidden issues, or it might give you the all-clear. Either way, it's better to know now than after you've signed on the dotted line.
Closing: The Big Kahuna
You've made it to the final stage. Closing day is like your wedding day, but with less romance and more paperwork. You'll sign a mountain of documents, hand over a big check, and finally, finally, you'll get the keys to your new home. Congratulations, you're a homeowner!
So there you have it, folks. The mortgage journey in a nutshell. It's a lot to take in, I know. But remember, it's all about finding the right fit for you. And hey, if you ever feel overwhelmed, just remember why you're doing this. You're about to make a house your home. That's pretty darn amazing.
