How To Get Your Name Off A Mortgage

So, you've decided it's time to say "bye-bye" to that mortgage that's been hanging around your neck like a, well, mortgage, right? Great! Let's dive in and make this happen. F...

So, you've decided it's time to say "bye-bye" to that mortgage that's been hanging around your neck like a, well, mortgage, right? Great! Let's dive in and make this happen. First things first, grab a cup of coffee or tea - we're gonna chat like old pals.
Why Bother?
You might be thinking, "Why should I care about getting my name off that mortgage?" Well, let me tell you, friend, it's like having a secret weight you didn't know you were carrying. Once it's gone, you'll feel lighter, freer. Plus, it's one less thing for the bank to hold over you. And who knows, maybe you'll finally be able to afford that fancy coffee you've been eyeing every morning!
Before We Start
Now, before we get our hands dirty, let's make sure you're actually on the mortgage. Sometimes, people forget they're still listed as a co-signer or co-borrower. So, check your credit report - it's free once a year at AnnualCreditReport.com.
Must Read
Two Magic Words: "Refinance" and "Assumption"
Alright, now that we're all set, let's talk about the two magical words that'll help you wave goodbye to that mortgage: refinance and assumption.
Refinance: The Easy Peasy Lemon Squeezy
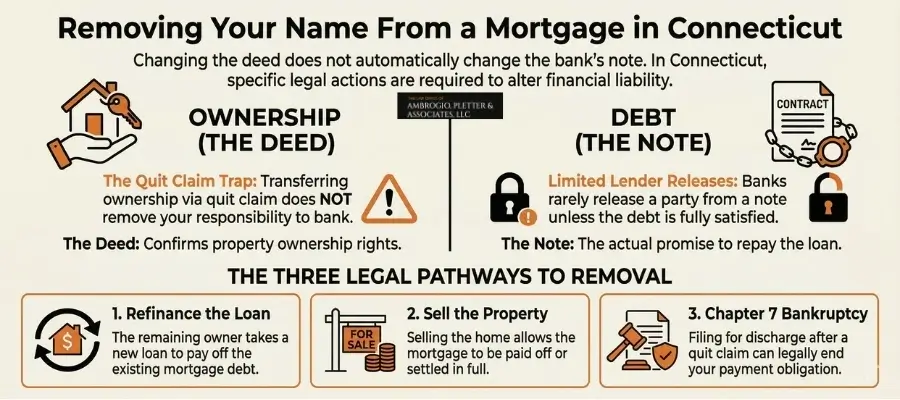
Refinancing is like trading in your old car for a new one - you're still driving the same roads, but with a different set of wheels. In this case, you're getting a new loan to pay off the old one. To get your name off the mortgage, you'll need to be the one refinancing. It's a bit of paperwork, but it's totally doable. Just make sure you've got a good credit score and can prove you've got the income to cover the new loan.
 How Do You Get Your Name Off a Mortgage Quickly and Easily
Assumption: Passing the Baton
Now, assumption is like when your friend takes over your gym membership because you're too busy binge-watching Netflix. In this case, your friend (or rather, the new buyer) takes over your mortgage. The catch? They've got to qualify for it, just like you did when you first got it. And the bank's got to agree to it. But if everything checks out, you're off the hook!
Let's Talk Shop
So, how do you know which one to choose? Well, that depends on your situation. Refinancing is usually simpler and faster, but it might not be the best option if interest rates have gone up since you first got your mortgage. Assumption, on the other hand, can be a bit more complicated, but it might be the way to go if you're selling your home and the new buyer wants to keep your mortgage.
 Is It Possible To Remove Your Name From A Mortgage in Connecticut?
Don't Go It Alone
Now, I know what you're thinking, "This all sounds like a lot of work." And you're right, it can be. But don't worry, you don't have to go it alone. There are plenty of lenders out there who'd be happy to help you refinance. And if you're selling your home, your real estate agent can help with the assumption process.
You Got This!
So, there you have it, folks! Getting your name off a mortgage is totally doable. It might take a bit of time and effort, but think about how great it'll feel when it's all done. You'll be dancing in the streets (metaphorically speaking, of course - unless you're into that sort of thing, in which case, you do you!).
Now, go forth, brave mortgage-leaver, and make it happen! And remember, if you ever feel stuck, don't hesitate to reach out to a professional. They're there to help, after all. And who knows, maybe one day you'll be sipping that fancy coffee, mortgage-free, and living your best life. Here's to you, my friend!
