How To Get A Mortgage On A Low Income

Alright folks, let's dive into the world of mortgages, where the big, scary 'M' word isn't as intimidating as it sounds. We're talking about getting a mortgage on a low income...
Alright folks, let's dive into the world of mortgages, where the big, scary 'M' word isn't as intimidating as it sounds. We're talking about getting a mortgage on a low income, and believe me, I've been there. I once tried to buy a house with nothing but a can of beans and a dream. Okay, maybe not that dramatic, but you get the gist.
First Things First: Check Your Credit Score
Imagine your credit score is like your credit history's report card. You want it to be shining like a gold star, not sulking like a detention slip. So, before you even think about a mortgage, check your score. It's like checking your temperature before you call in sick to work - you need to know where you stand.
If it's not where you want it to be, don't panic. It's like trying to grow a garden in winter - it takes time, but it's possible. Pay your bills on time, keep your credit utilization low, and watch your score bloom like a spring daffodil.
Must Read
Save, Save, Save: The Power of a Down Payment
You know how they say 'an apple a day keeps the doctor away'? Well, a good down payment keeps the PMI (Private Mortgage Insurance) away. PMI is like the annoying cousin who crashes your party and expects you to pay for their food - you don't want that.
So, start saving. Every penny counts, and it's like planting seeds for your future. You might feel like you're not making a dent, but trust me, those seeds will grow into a mighty oak tree. Aim for at least 3.5% of the home's value, but 20% is the golden ticket to avoid PMI.
Income: The Bread and Butter of Mortgages
Now, let's talk about income. It's the bread and butter of mortgages, the yin to the yang, the peanut butter to the jelly. Lenders want to know that you can afford to make those monthly payments, and they use something called a debt-to-income ratio (DTI) to figure that out.
DTI is like your financial report card. It compares how much you owe each month (your debts) to how much you earn (your income). Lenders typically like to see a DTI of 43% or less. So, if you're earning $3,000 a month, your total debts (including your new mortgage) should be $1,290 or less.
Government Programs: Your Secret Weapon
Now, here's where it gets interesting. There are government programs out there that can help you get a mortgage with a low income. They're like secret weapons in your financial arsenal, and you should definitely check them out.
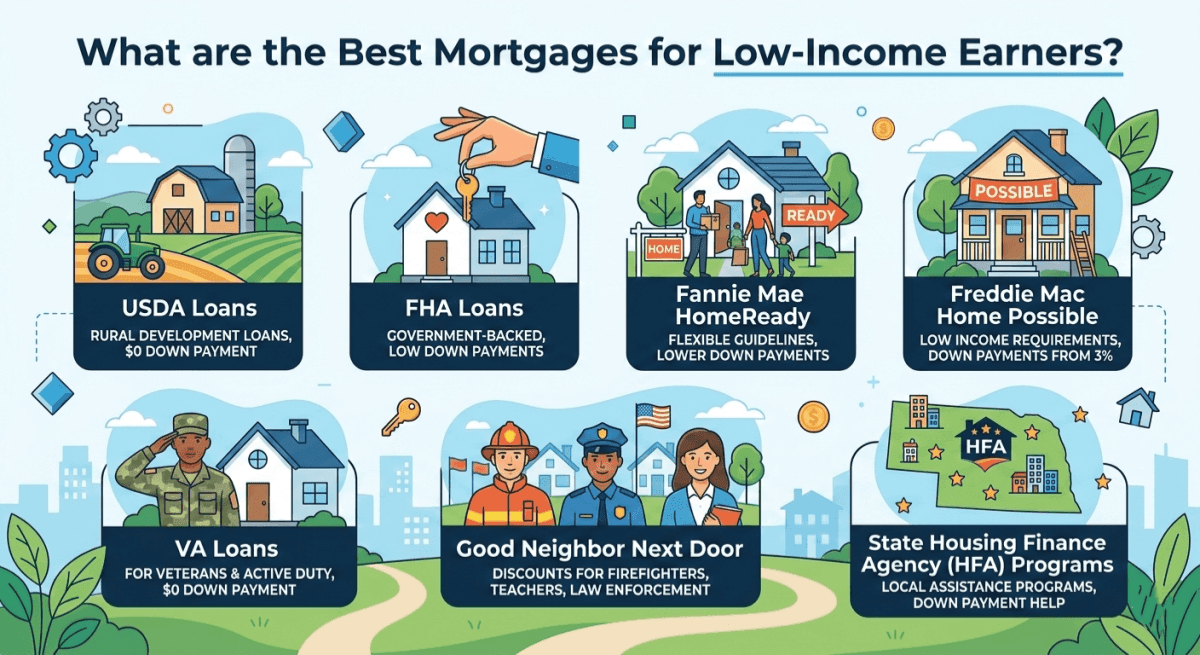 Best Mortgage for Low Income 2026: Which One for You?
FHA loans, VA loans, and USDA loans are some of the most popular ones. They have lower down payment requirements and are more lenient with credit scores. It's like having a personal trainer at the gym who's willing to work with your current fitness level and help you improve.
Shop Around: Lenders Aren't One-Size-Fits-All
You know how some clothes fit better than others? The same goes for lenders. They all have their own criteria and rates, so it's worth shopping around. It's like trying on different pairs of jeans until you find the perfect fit.
Don't be afraid to negotiate either. Lenders want your business, and they might be willing to work with you to get it. It's like haggling at a flea market - you never know until you try.
Patience, Grasshopper: It's a Marathon, Not a Sprint
Getting a mortgage on a low income isn't a sprint; it's a marathon. It takes time, patience, and a whole lot of determination. But remember, every step you take is a step closer to your goal.
So, keep at it. Keep saving, keep improving your credit, and keep looking for that perfect mortgage. And who knows? One day, you might find yourself holding the keys to your very own home. And that, my friends, is a feeling like no other.
