How To Get A Loan To Buy A Gym

Alright, so you've been pounding the pavement, not the treadmill, and you're thinking, "Hey, I could turn this town into a fitness haven! I just need a little help from my new...

Alright, so you've been pounding the pavement, not the treadmill, and you're thinking, "Hey, I could turn this town into a fitness haven! I just need a little help from my new best friend, the bank." Welcome to the wonderful world of gym loans! Let's dive in, shall we?
First things first: Know your numbers
Before you start dreaming about state-of-the-art equipment and a smoothie bar that would make Jamba Juice jealous, you need to get your financial house in order. Know your credit score, your debt-to-income ratio, and have a solid business plan ready. It's like going on a first date - you wouldn't show up in your PJs, right? (Well, maybe once, but that's a story for another time.)
Credit score: The key to unlocking the gym of your dreams
Your credit score is like your financial cheerleader. The higher it is, the more likely the bank is to throw confetti and approve your loan. Aim for a score of 680 or above. If it's not there yet, don't worry - there are plenty of ways to boost it. Pay your bills on time, keep your credit utilization low, and be patient. Rome wasn't built in a day, and your credit score won't improve overnight either.
Must Read
Find your loan match
Now that you've got your financial ducks in a row, it's time to find the perfect loan. It's like finding a gym buddy - you want someone reliable, who won't leave you hanging with the bill. Here are a few options:
Small Business Administration (SBA) loans
SBA loans are like the popular kid in school - they're backed by the government, so they're easier to get and have better terms. The catch? They take longer to process. But hey, good things come to those who wait, right?
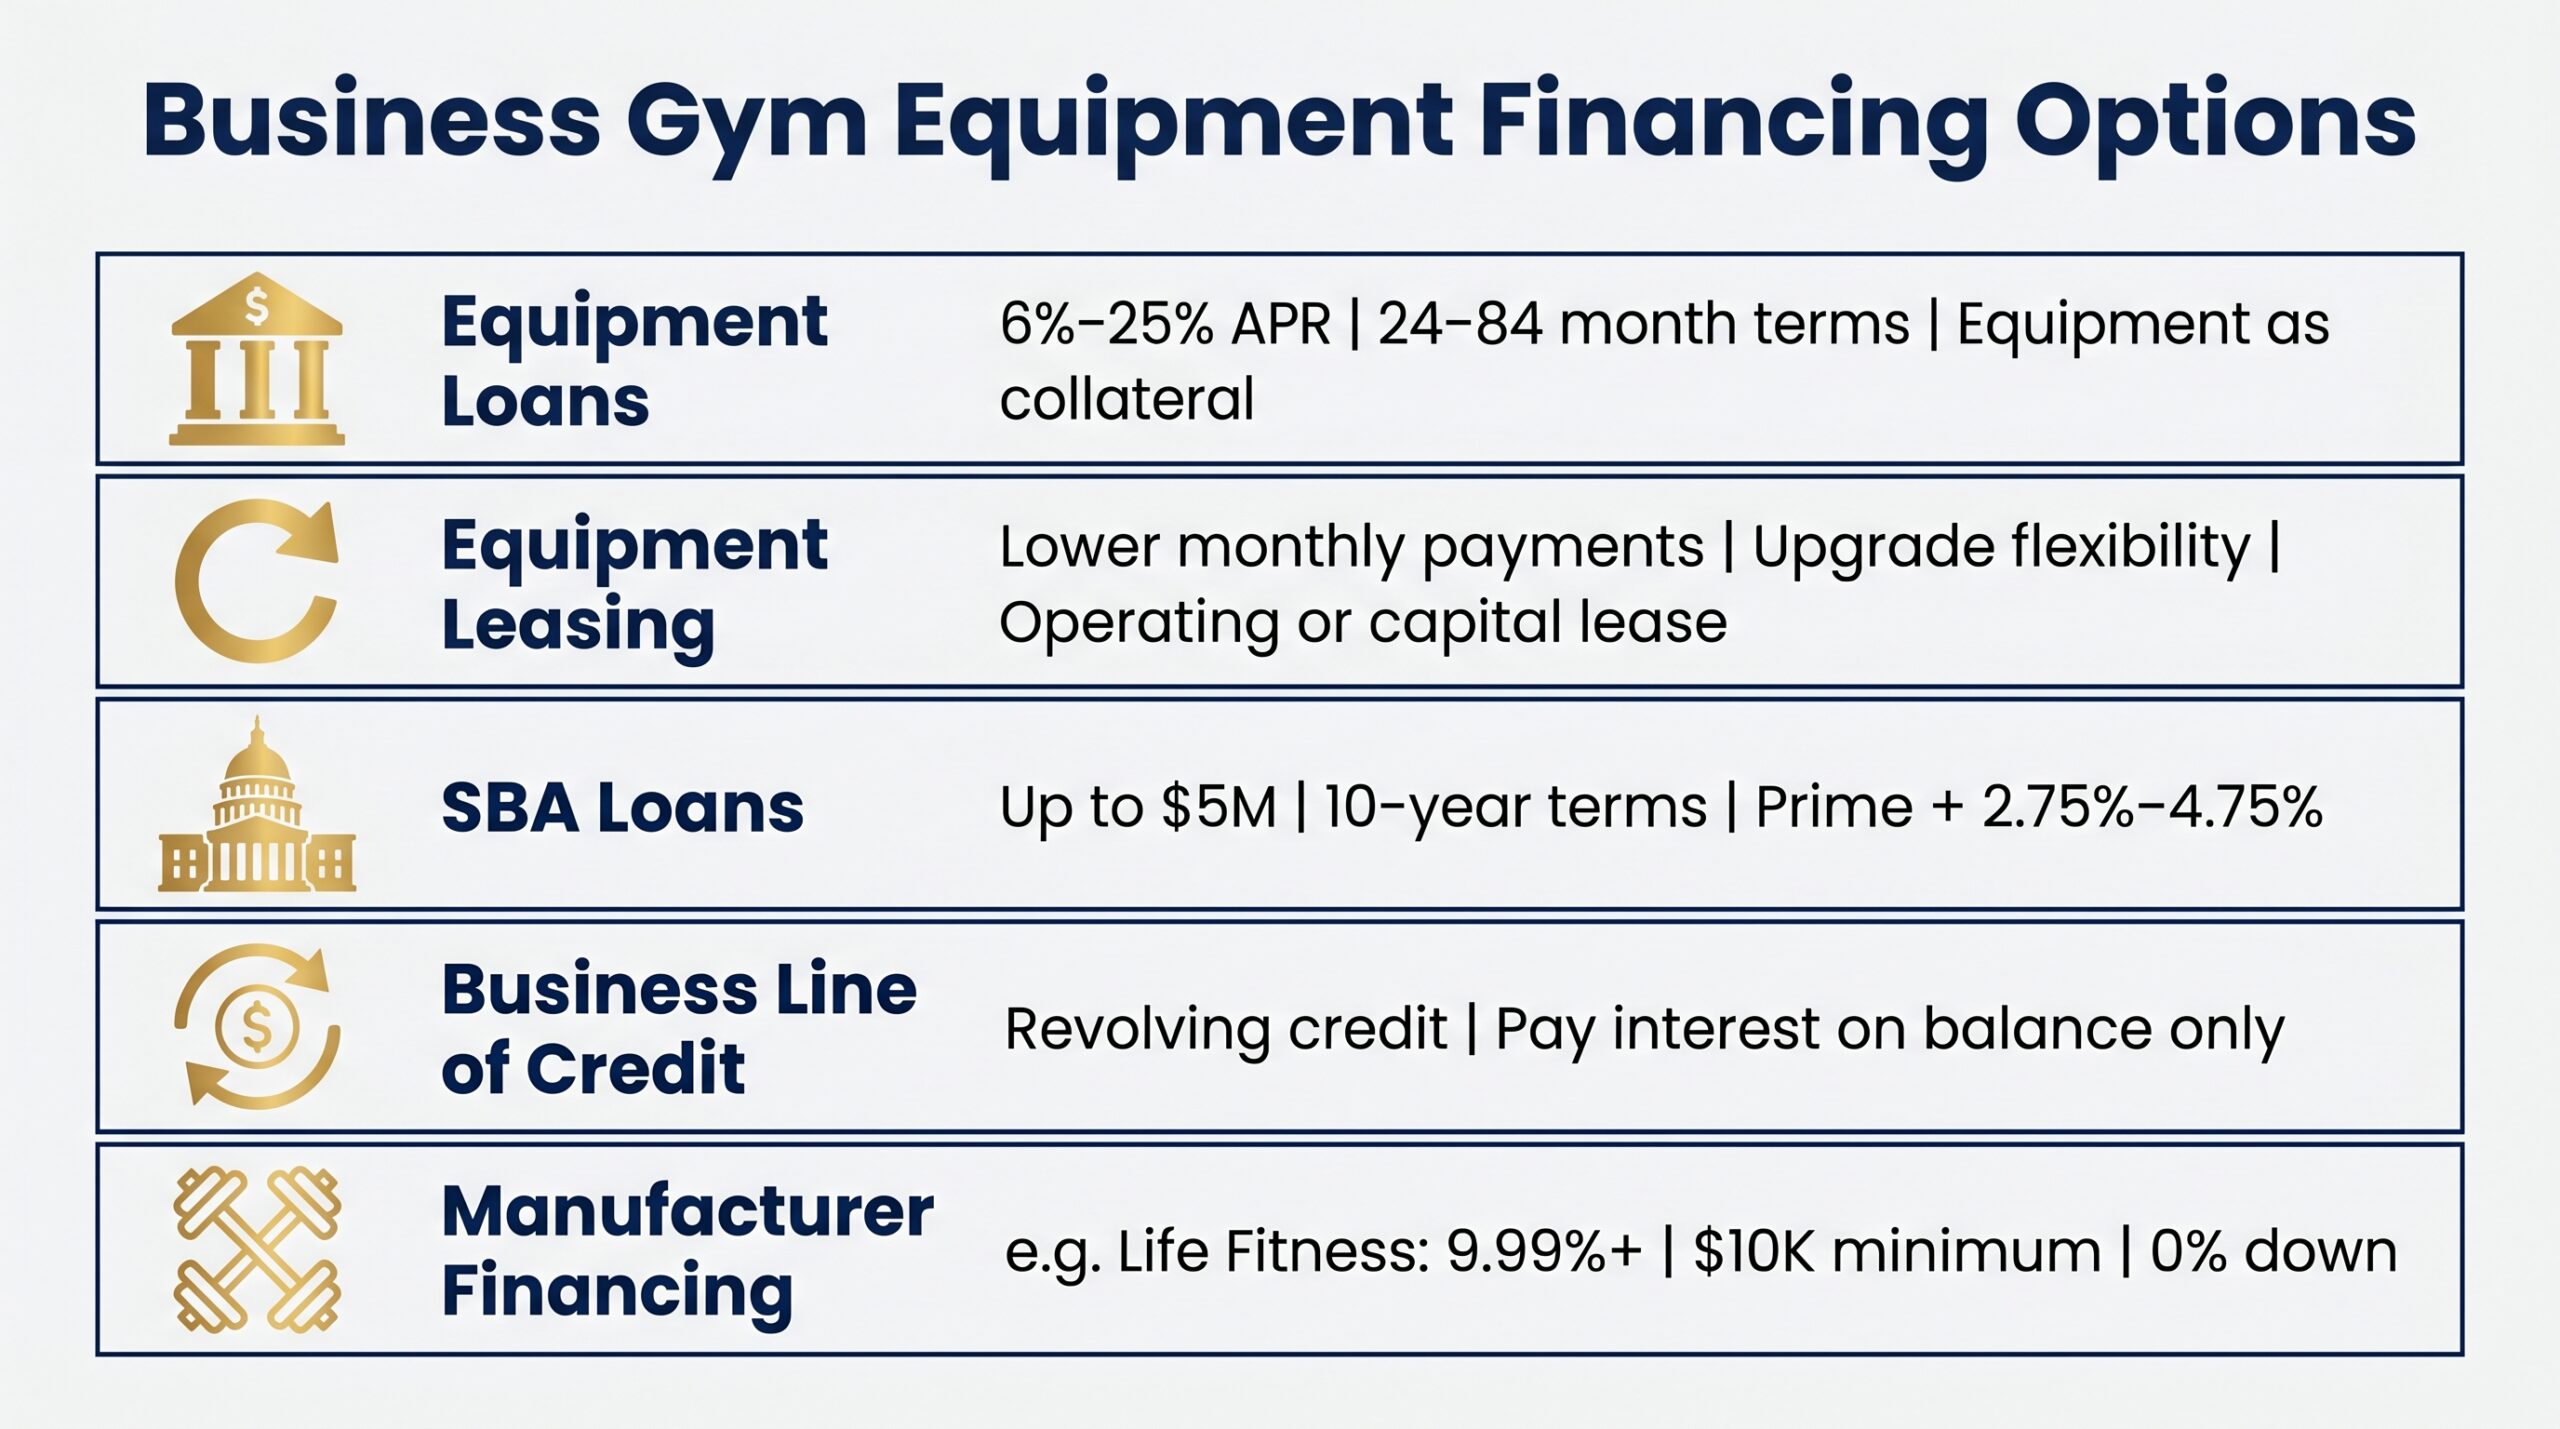 Gym Equipment Financing: Options for Owners & Individuals
Bank loans
Bank loans are like the teacher's pet - they have high standards, but if you meet them, they'll treat you right. They usually require collateral and have strict terms, but they can offer competitive rates.
Online lenders
Online lenders are like the cool kid who skips class - they're more laid-back and faster to process, but they might charge higher fees. It's a trade-off, so choose wisely.
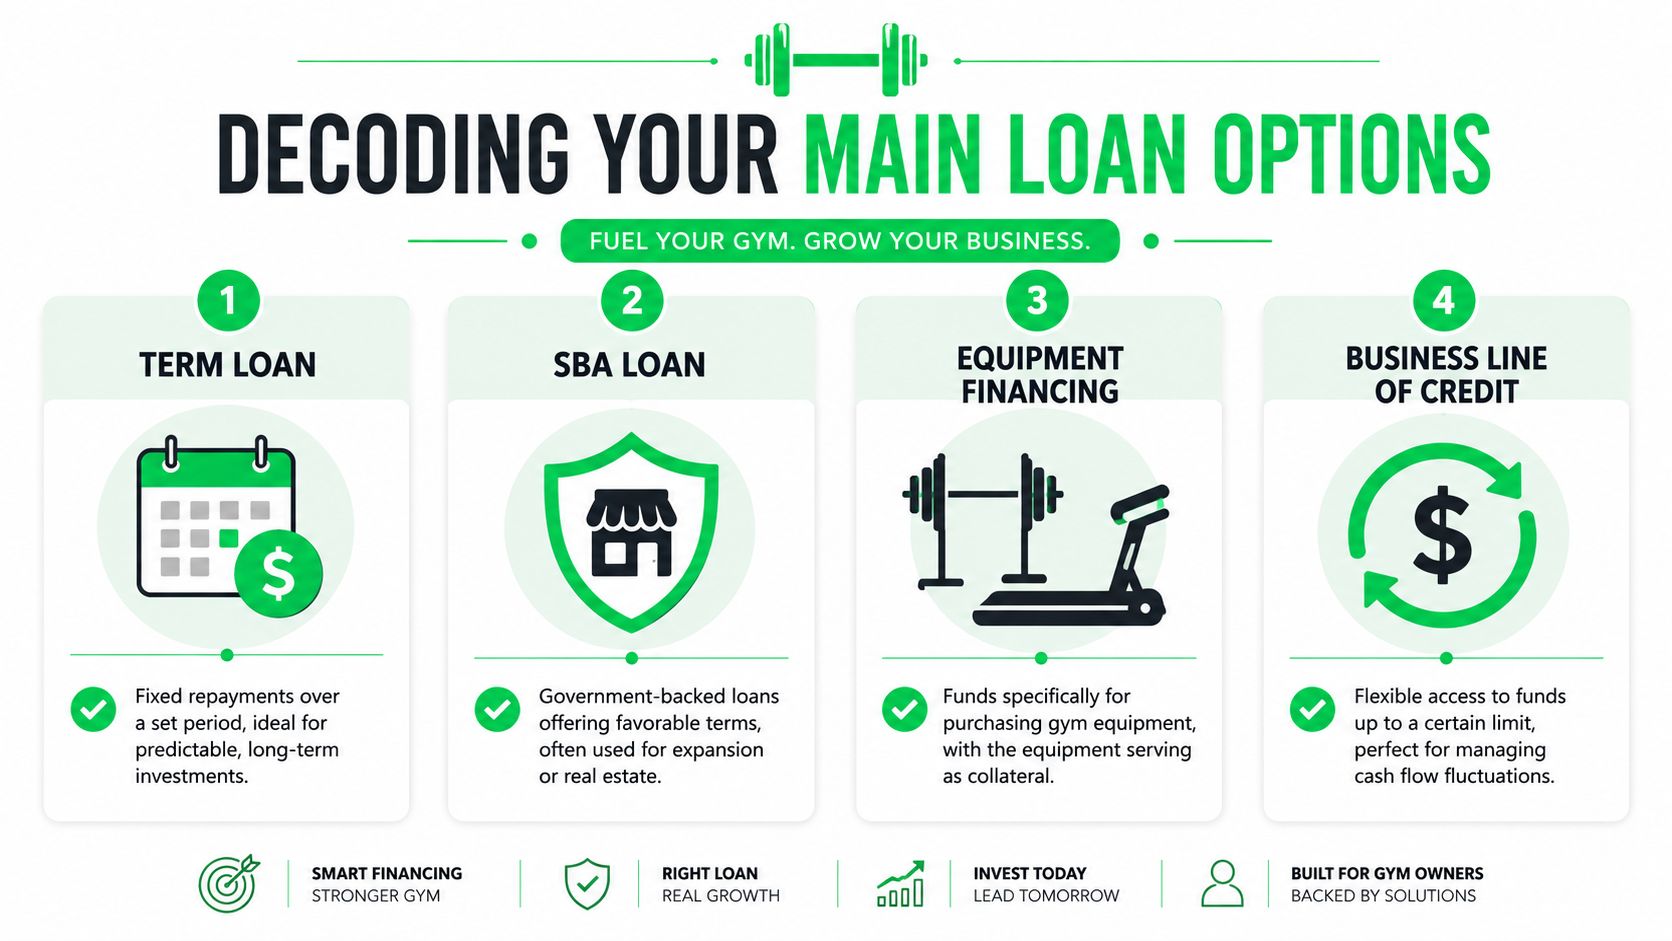 Business Loans for Gyms: Your No-Nonsense Operator's Guide | Fitness GM
Get your docs in a row
Once you've found your loan match, it's time to get your documents in order. It's like packing for a trip - you don't want to forget anything important. You'll need:
- Business plan
- Financial projections
- Resume and/or bio
- Legal documents (like your business license and articles of incorporation)
- Collateral (if required)
And that's it! You're ready to hit the gym... loan, that is. Just remember, getting a loan is like working out - it takes time, effort, and patience. But with the right attitude and a solid plan, you'll be pumping iron (and cash) in no time.
