How To Calculate Apr On Auto Loan

Hey there, fellow car enthusiast! Ever found yourself scratching your head over those finance jargon when shopping for a new set of wheels? Don't worry, you're not alone. Toda...
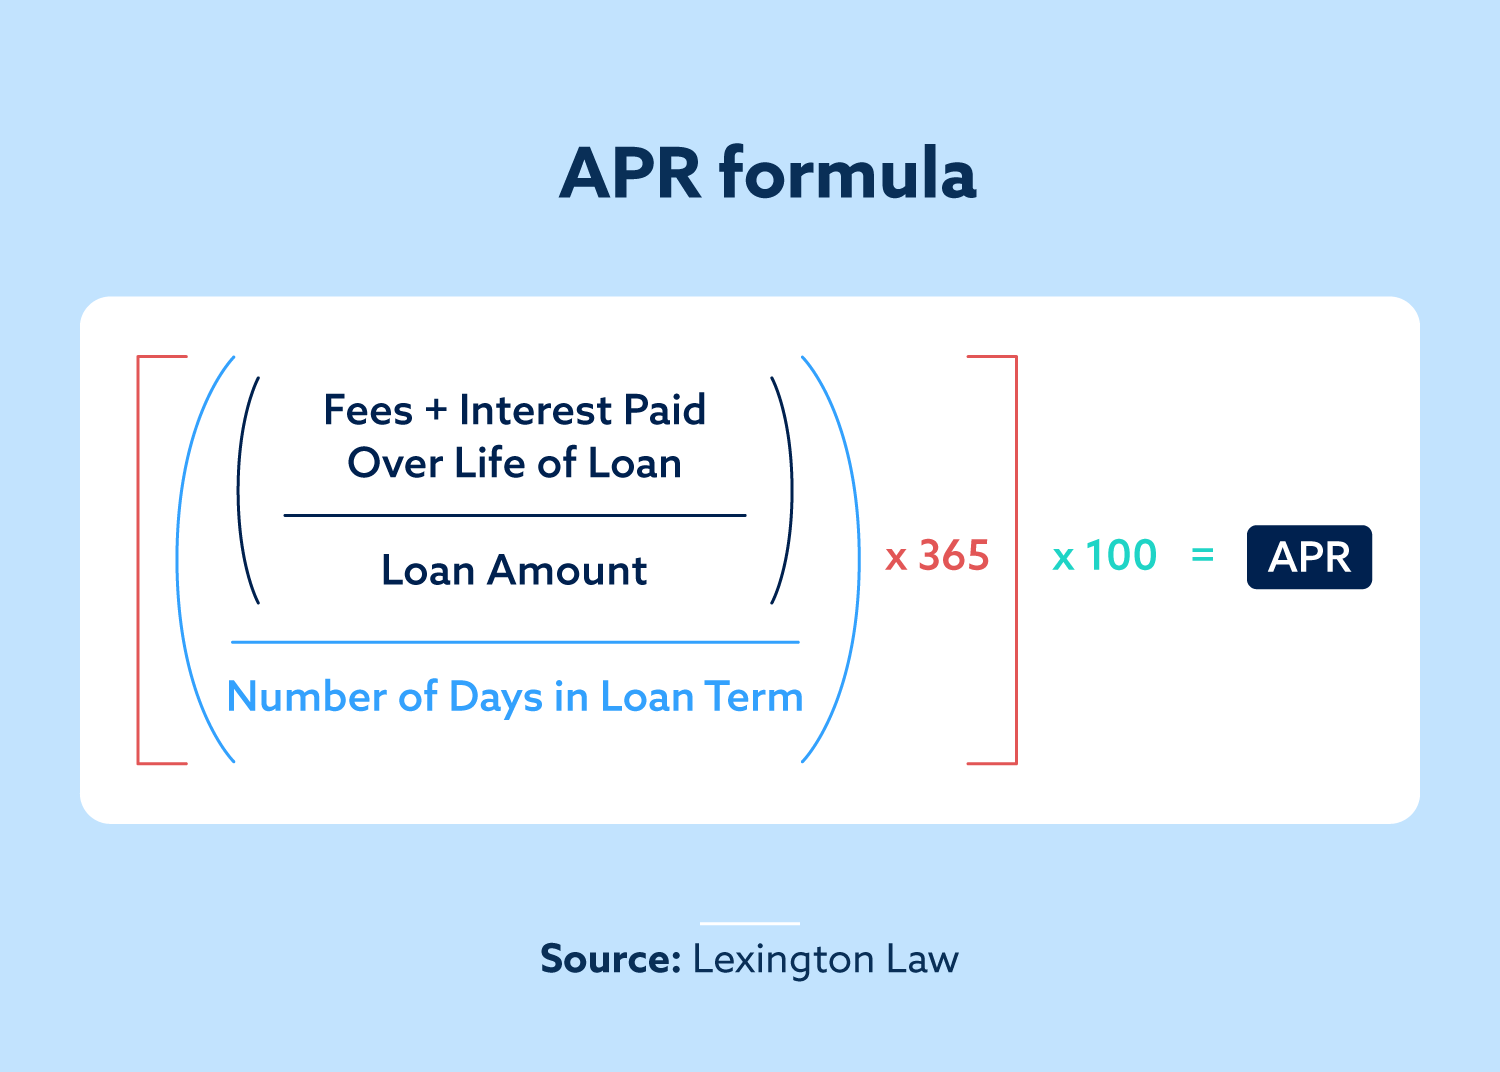
Hey there, fellow car enthusiast! Ever found yourself scratching your head over those finance jargon when shopping for a new set of wheels? Don't worry, you're not alone. Today, we're going to tackle one of those mysterious terms - Annual Percentage Rate (APR) on auto loans. By the end of this, you'll be calculating APR like a pro, and you'll understand why it's as important as knowing your own birthday. Let's dive in!
First Things First: What's APR?
Imagine you're at your favorite coffee shop. You order a fancy latte for $5. The barista says, "That'll be $5 today, and $1 every day for the next year." That's basically APR! It's the total cost of borrowing money, expressed as a percentage of the loan amount. It includes the interest rate and any fees the lender charges.
Why Should You Care About APR?
Ever bought a pair of shoes that seemed like a great deal, only to find out they were on sale for the same price last week? That's what happens when you don't consider APR. It's like the hidden tax on your loan. A lower APR means you pay less in interest, and a higher APR means you pay more. It's that simple!
Must Read
APR vs. Interest Rate: What's the Difference?
You might be thinking, "But I already know my interest rate!" That's great! But remember, interest rate is just one part of the APR puzzle. It only considers the interest you pay, not the fees. APR, on the other hand, gives you the whole picture. It's like comparing a recipe that only lists ingredients (interest rate) to one that also tells you the cooking time and adds salt to taste (APR).
Now, Let's Calculate APR!
Ready to roll up your sleeves and do some math? Don't worry, it's not as scary as it sounds. Let's say you're borrowing $20,000 for a shiny new car with a 60-month term (that's 5 years, folks!). Your lender quotes you an interest rate of 6% and a fee of $500. Here's how you calculate the APR:
- First, find the total amount of interest you'll pay over the life of the loan. In this case, that's $20,000 * 6% * 5 years = $6,000.
- Next, add the fee to the total interest. So, $6,000 + $500 = $6,500.
- Now, divide that number by the original loan amount and multiply by 100 to get the APR. So, ($6,500 / $20,000) * 100 = 32.5%.
And there you have it! Your APR is 32.5%.
Why Bother Calculating APR?
You might be wondering, "Why go through all that trouble when the lender can just tell me the APR?" Well, my friend, it's important to double-check because lenders aren't always forthcoming with the APR. They might quote you a low interest rate, but hide the fees. By calculating the APR yourself, you'll know exactly what you're getting into.
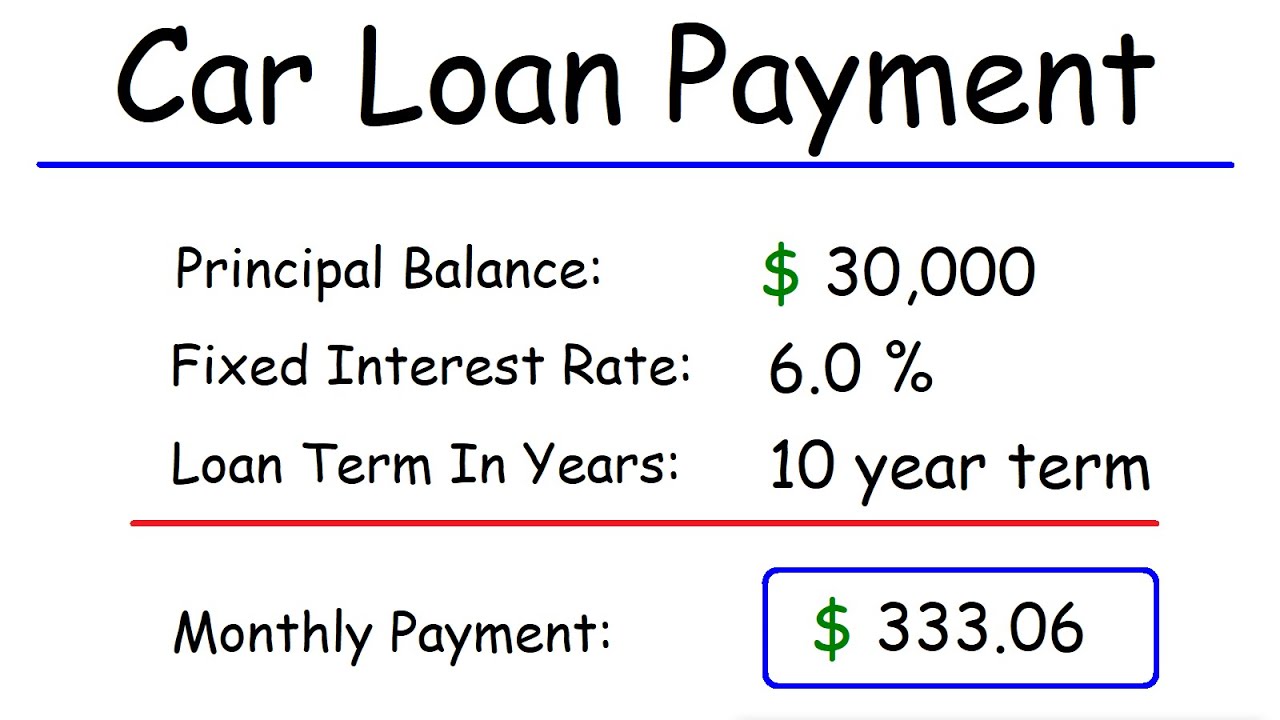 How To Calculate Apr On Car Loan
Plus, it's a great way to compare offers from different lenders. Let's say one lender offers a 5% interest rate with a $1,000 fee, and another offers a 6% interest rate with no fee. You might think the first offer is better, but if you calculate the APR, you'll see that the second offer is actually cheaper.
APR and Your Credit Score: A Love Story
Here's a fun fact: Your credit score and APR are like two lovebirds. The better your credit score, the lower the APR. That's because lenders see you as less risky, so they're willing to charge you less in interest. It's like they're saying, "You're so responsible, we trust you with our money!"
On the other hand, if your credit score is on the lower side, lenders might charge you a higher APR. They see you as riskier, so they want to make sure they get their money back with interest. It's like they're saying, "We're not sure about you, so we're going to charge you more just in case."
APR and Your Budget: A Match Made in Heaven
Now that you know how to calculate APR, it's time to put that knowledge to good use. When you're shopping for a car loan, always ask for the APR, not just the interest rate. Then, use that number to figure out your monthly payments. There are plenty of online calculators that can help with that.
For example, if you're borrowing $20,000 with a 32.5% APR and a 60-month term, your monthly payment would be around $460. That's a big chunk of change, so make sure it fits into your budget. Remember, it's always better to borrow less and pay off your car faster than to stretch yourself too thin.
 What APR Means (Annual Percentage Rate)?
APR and Negotiation: The Art of the Deal
Here's a little secret: APR is negotiable. That's right, you can haggle with your lender just like you would with a car salesperson. If you have a good credit score, you're in a great position to negotiate a lower APR. You can also ask your lender to waive fees or reduce the interest rate.
But remember, it's always better to negotiate the price of the car first. That's where you'll see the biggest savings. Once you've got the best price on the car, then you can start negotiating the APR.
APR and the Future: A Crystal Ball
APR isn't just about the here and now. It's also about the future. When you're calculating APR, you're essentially predicting how much your loan will cost you down the line. It's like looking into a crystal ball and seeing your financial future.
So, the next time you're in the market for a new car, don't forget to ask about the APR. It's the key to understanding the true cost of your loan and making sure you're getting the best deal. And who knows, maybe you'll even have some fun with that fancy math we did earlier!
Happy calculating, and happy driving!
