How To Buy Someone Out Of A Joint Mortgage

Ever found yourself in a mortgage pickle with a pal? Like sharing a mortgage is a great idea until you're binge-watching "Friends" reruns and they're all "How you doin'?" to t...
Ever found yourself in a mortgage pickle with a pal? Like sharing a mortgage is a great idea until you're binge-watching "Friends" reruns and they're all "How you doin'?" to the neighbor. Suddenly, you're not laughing anymore. Time to buy them out, huh?
First things first, let's talk numbers.
Buying someone out of a mortgage is like splitting the bill at a fancy dinner. You gotta know what you're paying for. So, grab a calculator and let's crunch some numbers.
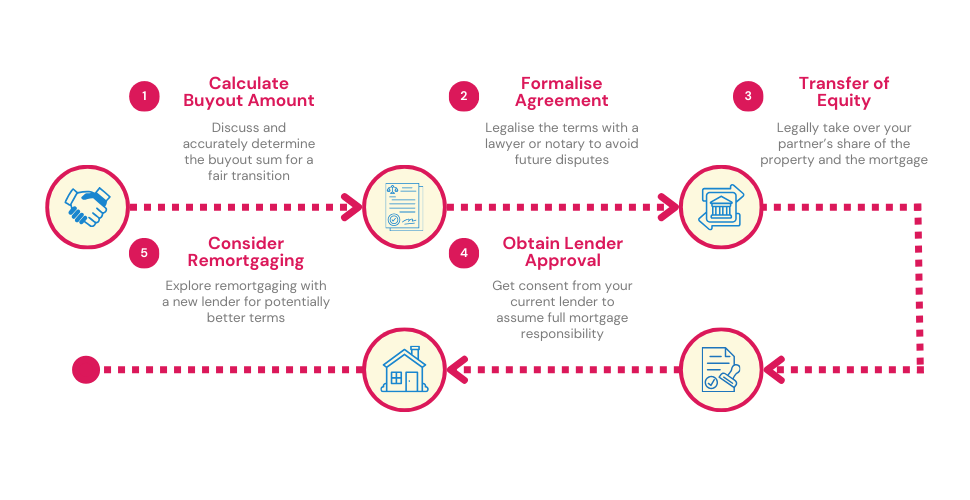
First, find out how much equity you've built. That's the difference between your home's value and the outstanding mortgage. Then, decide who's staying and who's going. The one leaving gets their share of the equity, and you'll need to refinance the mortgage in your name alone.
Must Read
Now, let's talk about the fun part: the break-up fee.
This is the amount the leaver gets for their share of the equity. It's usually calculated by taking their percentage of the equity and multiplying it by the home's value. For example, if your home's worth $300,000 and you've each paid 50% of the mortgage, the leaver gets $75,000 (half of $150,000, which is half of $300,000).
But wait, there's more! You'll also need to factor in closing costs for the refinance. These can range from 2% to 5% of the new loan amount. So, if you're refinancing for $250,000, you're looking at $5,000 to $12,500. Yikes!
Time to get legal.
Now that you've got your numbers sorted, it's time to make it official. You'll need a quitclaim deed, which transfers the leaver's interest in the property to you. It's a simple document, but you'll need to file it with your county recorder's office.
 Can a Joint Mortgage Be Transferred to One Person?
Next, you'll need to refinance the mortgage. This involves getting a new loan in your name alone, which pays off the old loan. The lender will want to know that you can afford the new mortgage on your own, so you'll need to provide proof of income and good credit.
But wait, what if you can't refinance alone?
If your lender won't approve you for a refinance, you might need to get a new loan with the leaver still on it. This is called a "subject to" agreement, and it's like a temporary Band-Aid. The leaver stays on the mortgage, but they don't have to pay. You do. Until you can refinance again.
Let's talk about the elephant in the room: taxes.
When you buy someone out of a mortgage, it's considered a sale for tax purposes. The leaver will need to report their share of the equity as capital gains. If they've lived in the home for at least two of the past five years, they can exclude up to $250,000 of the gain from their taxes (or $500,000 if they're married filing jointly).
 Buying your partner out of a joint mortgage - Nuts About Money
But here's where it gets weird: the leaver might have to pay taxes on their share of the closing costs too. It's like paying taxes on a break-up fee. Fun, right?
Finally, let's talk about the future.
Buying someone out of a mortgage can be a great way to avoid a messy break-up. But it's not always easy. You might have to pay more in closing costs than you expected. Or you might not be able to refinance alone. But at least you'll have your own space to watch "Friends" reruns in peace.
So, if you're thinking about buying someone out of a mortgage, do your homework. Talk to a lender, a real estate attorney, and maybe even a therapist. Because breaking up is hard to do, even when it comes to mortgages.
