How To Buy Someone Out Of A House Mortgage

Ever wondered how to buy someone out of a house mortgage? It's like splitting a giant pizza, but with a bit more paperwork. Let's dive in, shall we? Why Buy Someone Out? The...
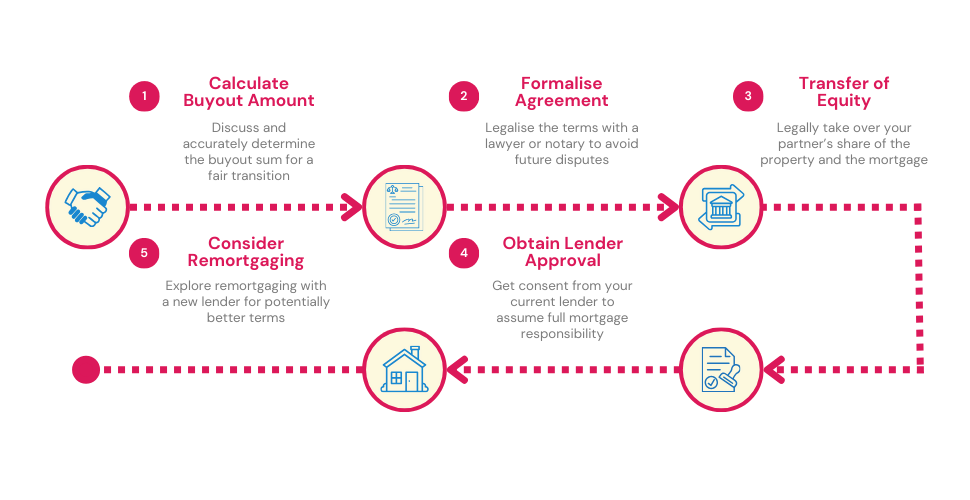
Ever wondered how to buy someone out of a house mortgage? It's like splitting a giant pizza, but with a bit more paperwork. Let's dive in, shall we?
Why Buy Someone Out?
There are plenty of reasons why you might want to buy someone out of a mortgage. Maybe you're in a long-term relationship and want to merge your finances. Or perhaps you're a family member helping out, or even a friend who's had a change of heart about co-owning a place.
It's like when you and your buddy decide to split the rent, but one of you wants to buy the other out. It's a big decision, so let's break it down.
Must Read
Understanding the Mortgage
First things first, you need to understand the mortgage. It's like the lease on your car, but for a house. It's a loan that the bank gives to the homeowner, which they pay back over time.
There are two types of mortgages: fixed-rate and adjustable-rate. A fixed-rate mortgage has the same interest rate for the entire loan term. An adjustable-rate mortgage, on the other hand, has an interest rate that can change over time.
Now, let's talk about who's responsible for the mortgage payments. If you're buying someone out, you'll want to know who's been making the payments and who's responsible for the loan.
What's the House Worth?
Before you buy someone out, you need to know what the house is worth. It's like knowing the value of that vintage guitar you've been eyeing at the pawn shop.
 Property ownership disputes: A complete guide to TOLATA claims
You can get a rough estimate using online tools, but for a more accurate value, you'll want to hire a professional appraiser. They'll look at the house's condition, size, location, and recent sales of similar homes in the area.
Who Owes What?
Now, let's talk about who owes what. This is where things can get a bit tricky. The amount of money you'll need to pay to buy someone out depends on a few factors:
- Equity: This is the difference between the home's value and the outstanding mortgage balance. If you're buying out the person with more equity, you'll pay more.
- Mortgage Balance: This is the total amount of the mortgage that's still owed. You'll need to pay off this amount to buy someone out.
- Property Taxes and Insurance: These are ongoing costs that need to be paid. You'll need to agree on who pays what, or if one person will pay both.
It's like splitting the bill at a restaurant. If one person ordered the expensive steak and the other had the salad, they wouldn't pay the same amount, right?
Legal Stuff
Once you've agreed on the amount, it's time to make it official. You'll need to hire a real estate attorney to draw up a quitclaim deed. This is a legal document that transfers the ownership of the property from one person to another.
 Can you buy someone out of their house? - Goldmanread
You'll also need to contact the mortgage lender. They'll need to approve the transfer of the loan, and they might require additional paperwork. It's like getting your parents to sign off on a big purchase, but with more paperwork.
What About the Mortgage?
Now, let's talk about what happens to the mortgage. If you're the one buying out the other person, you'll need to refinance the loan in your name. This means you'll apply for a new mortgage and pay off the old one.
If you're the one being bought out, you'll be released from the mortgage. It's like finally paying off your student loans - a huge weight off your shoulders!
Final Thoughts
Buying someone out of a house mortgage is a big decision, but it doesn't have to be a scary one. With a bit of knowledge and the right team of professionals, you can navigate the process like a pro.
So, there you have it. Buying someone out of a mortgage is like splitting a giant pizza, but with more legal stuff. It's a big decision, but with the right information, you can make it a piece of cake. Happy house-buying!
