How Much Should I Be Saving For Retirement

Hey there, future retiree! Let's chat about something that's super important, yet often feels as exciting as watching paint dry - retirement savings. Don't worry, I promise to...
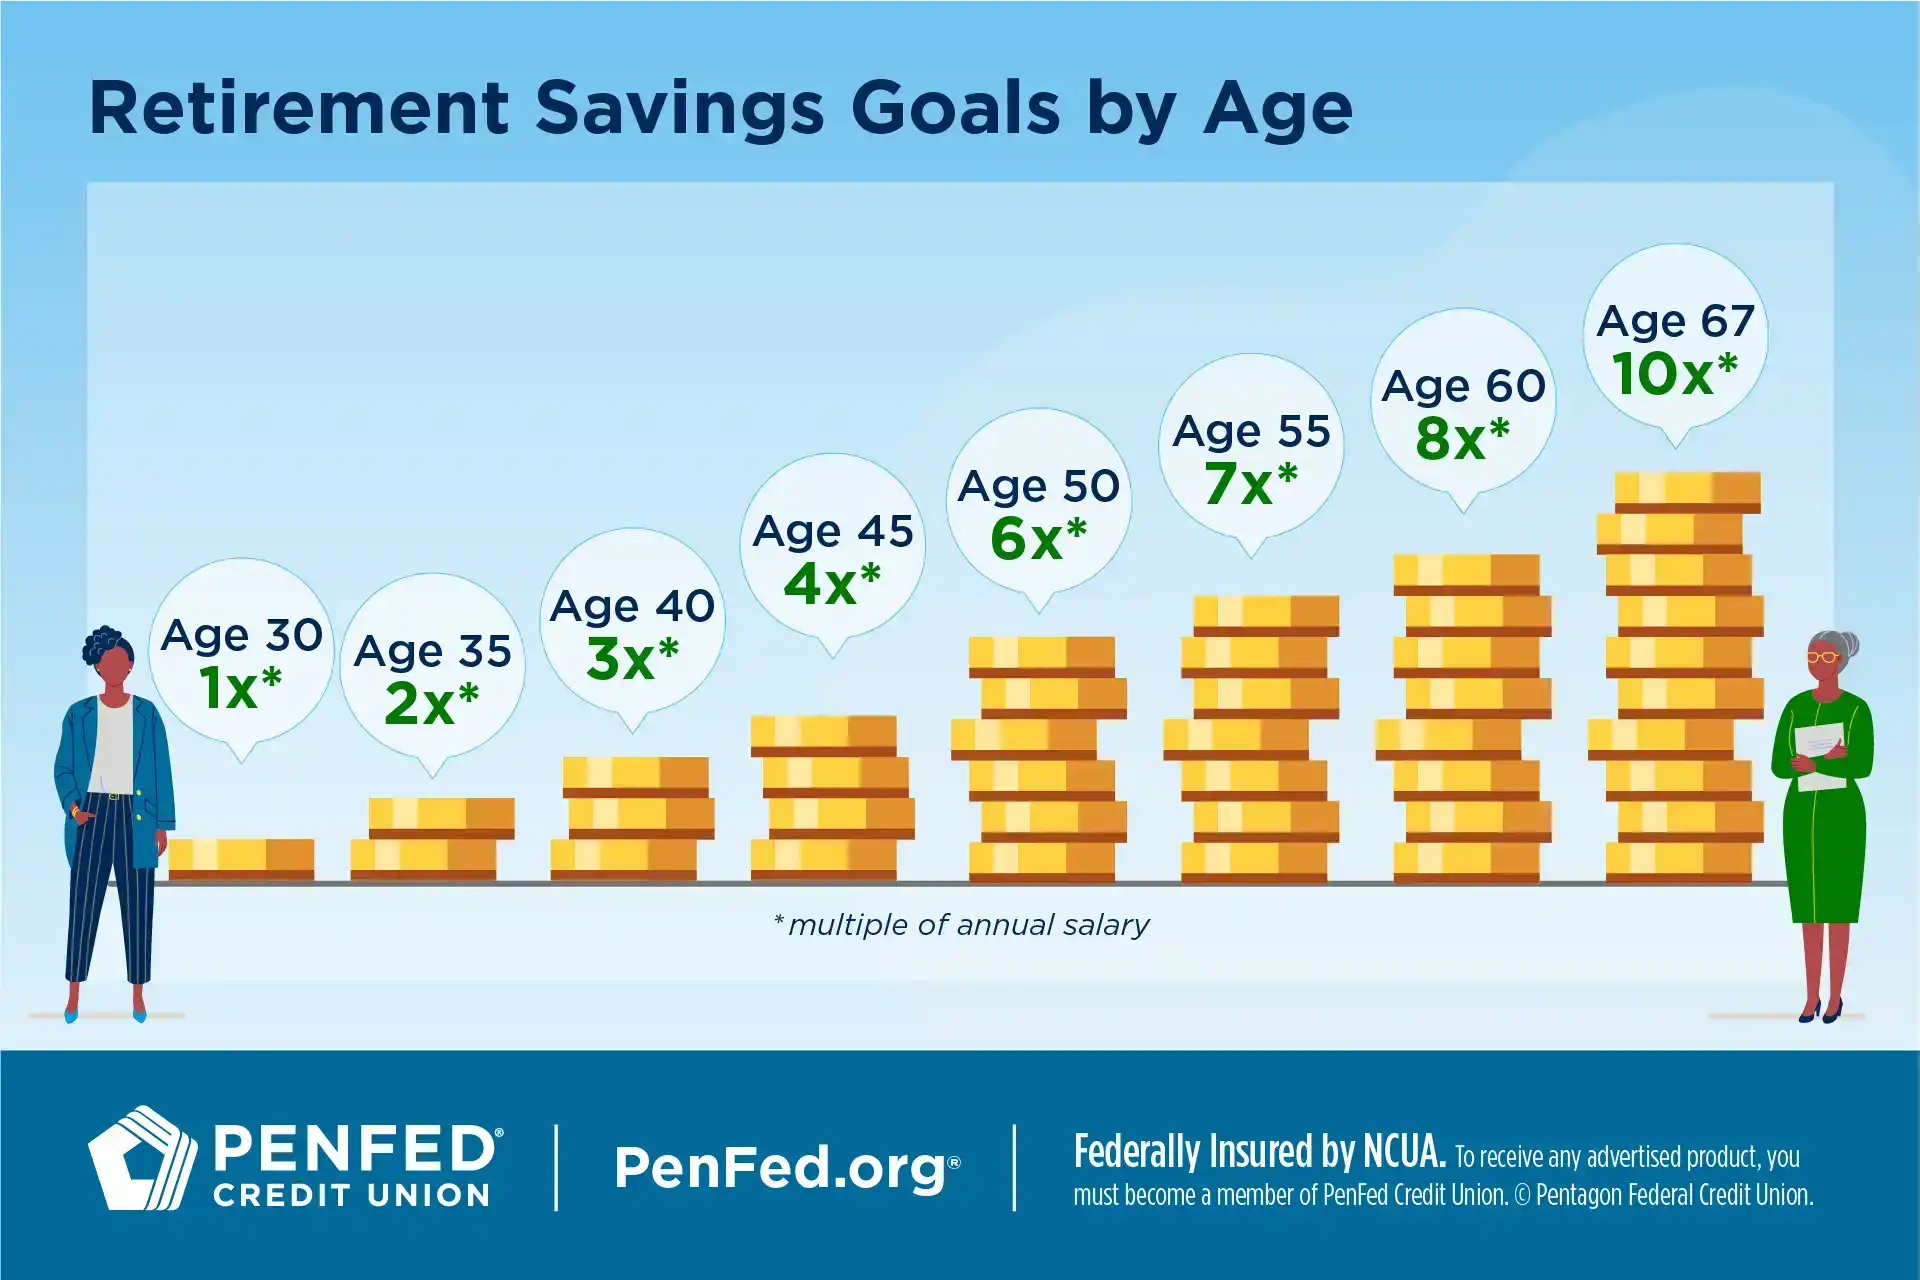
Hey there, future retiree! Let's chat about something that's super important, yet often feels as exciting as watching paint dry - retirement savings. Don't worry, I promise to keep it fun and painless, like a root canal with a happy ending. (Too much? Let's move on.)
First things first: Why save for retirement?
Imagine you're a squirrel (stick with me here). You've got a cozy little nest, but you know winter's coming. You're not gonna survive on acorns alone, right? So, you start hoarding nuts. That's basically what retirement savings are - your personal nut stash for the future.
Now, you might be thinking, "But I'm not a squirrel! I have a job, and I'll just keep working forever!" Well, friend, even if you're the energizer bunny, there might come a time when you want to kick back, relax, and not worry about the daily grind. That's where your retirement savings come in.
Must Read
So, how much should you be saving?
Alright, let's get down to brass tacks. The magic number you've probably heard thrown around is 15% of your pre-tax income. That's right, 15%! It sounds like a lot, but let's break it down.
Think of it like this: if you're making $50,000 a year, that's $7,500 you'd be saving. It's like giving yourself a really generous raise every year, just for your future self. Not too shabby, huh?
But hey, I get it. You're not made of money (yet). So, if 15% feels like too much, start with what you can. Even saving 1% is better than nothing. The important thing is to start.
But what if I've got debt?
Great question! If you're drowning in student loans or credit card debt, it might feel like you can't afford to save for retirement. But here's the thing - interest on debt can pile up fast, while retirement savings can grow even faster with compound interest. So, it's like choosing between a snowball rolling uphill (good) or downhill (bad).
 Retirement Calculator - See How Much You'll Need to Retire
Here's a tip: Pay off high-interest debt first, then start saving for retirement. And if your employer offers a 401(k) match, that's free money! Always take it.
Investing: The magic of compound interest
Now, let's talk about investing. Because, you know, money doesn't grow on trees (yet). But it can grow in the stock market, thanks to something called compound interest.
Imagine you invest $100 and it grows by 10% each year. After 10 years, you'd have over $260! After 20 years, you'd have over $670! And after 30 years? Over $1,700! That's like having a money tree, but with less watering and more patience.
Of course, the market goes up and down, so you've got to be ready for some rollercoaster rides. But historically, it trends upward. So, don't let fear keep you from investing. Remember, time is your friend here - the earlier you start, the more time your money has to grow.
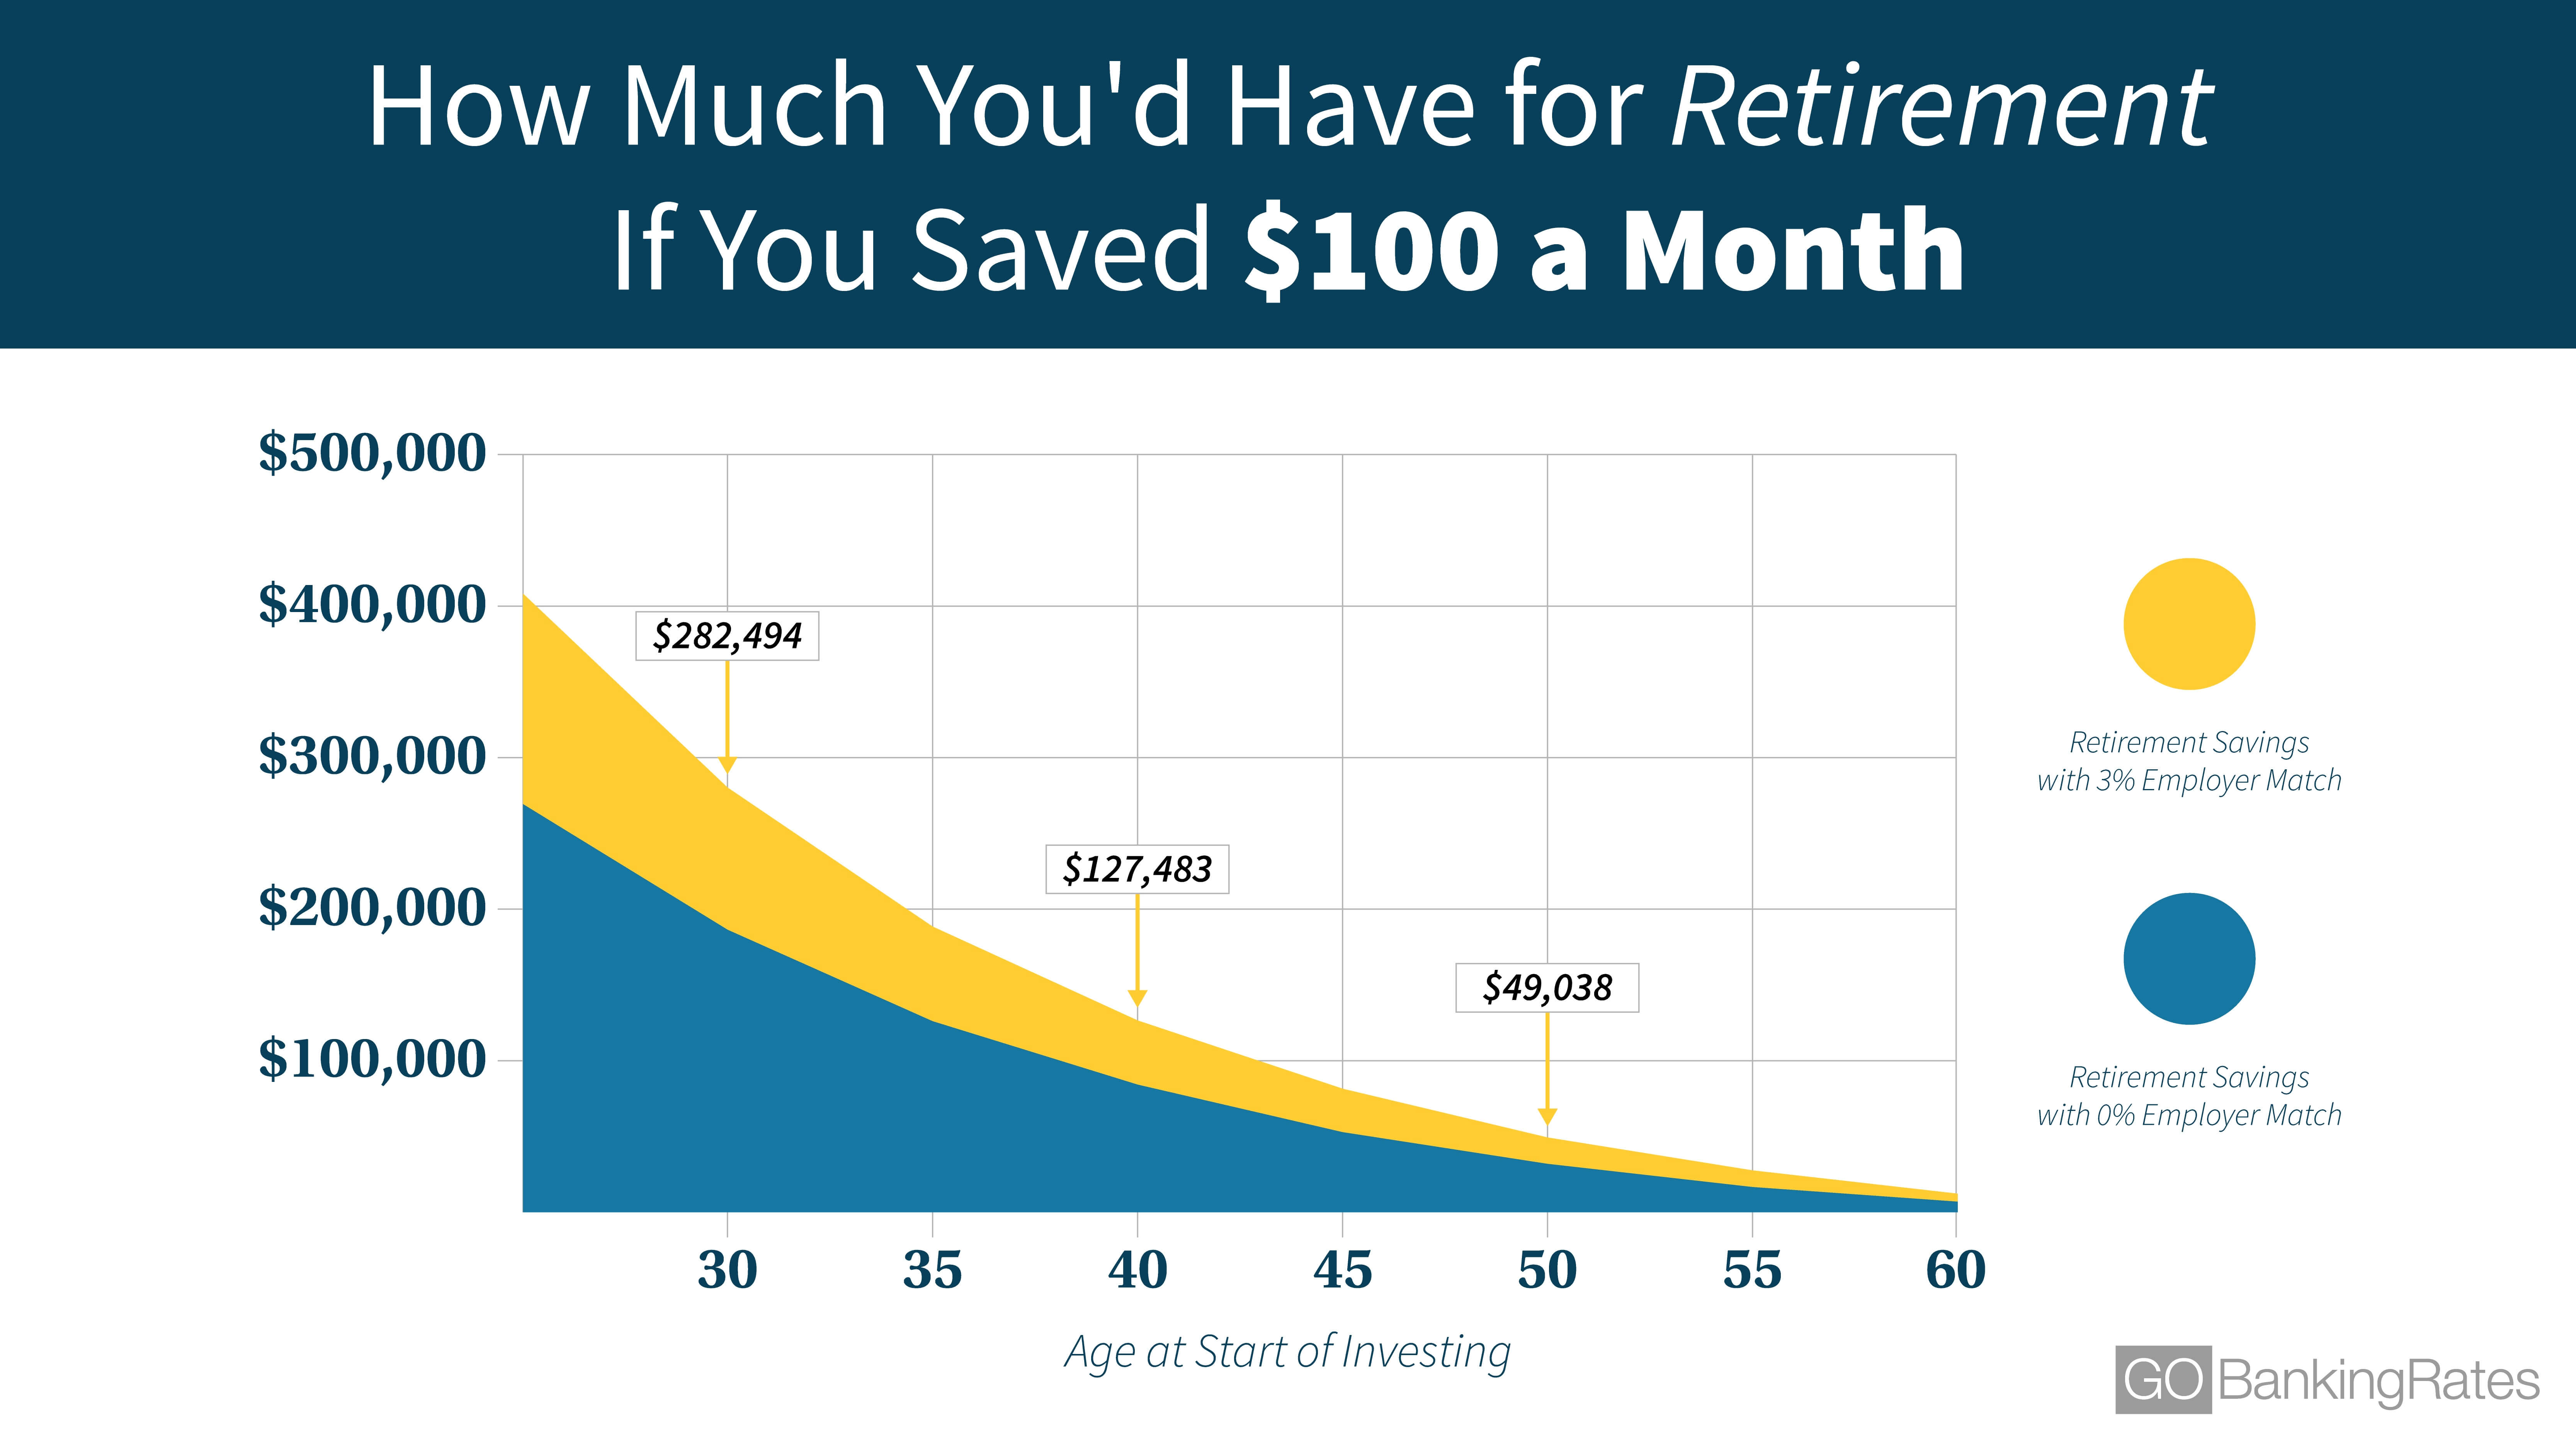 Can You Retire by Saving One Hundred Dollars a Month? | GOBankingRates
Retirement savings: It's not just about the money
Alright, let's talk about something that's not so fun - outliving your money. It's a real thing, and it's scary. But here's the good news: saving for retirement isn't just about having a big nest egg. It's about having options.
When you've got a solid retirement savings, you can afford to take risks, try new things, and live life on your terms. You can travel, volunteer, start a business, or just kick back and enjoy your grandkids. The world is your oyster!
And hey, if you ever find yourself running out of money, you can always become a professional squirrel. You'll already know how to hoard nuts!
You've got this!
So, there you have it. Saving for retirement isn't as complicated as it seems. It's just about starting small, investing wisely, and giving your money time to grow. And remember, every little bit helps. Even if you can only save $5 a week, that's $260 a year. That's $2,600 in 10 years. And that, my friend, is a start.
Now, go forth and save! Your future self will thank you. And who knows? Maybe one day, you'll be the one sipping piña coladas on a beach, laughing at the fact that you ever worried about retirement savings. Until then, keep hoarding those nuts!
