How Much Home Can I Realistically Afford

So, you're thinking about buying a home, huh? Welcome to the big leagues, buddy! You're about to embark on a journey that's part excitement, part confusion, and all kinds of f...
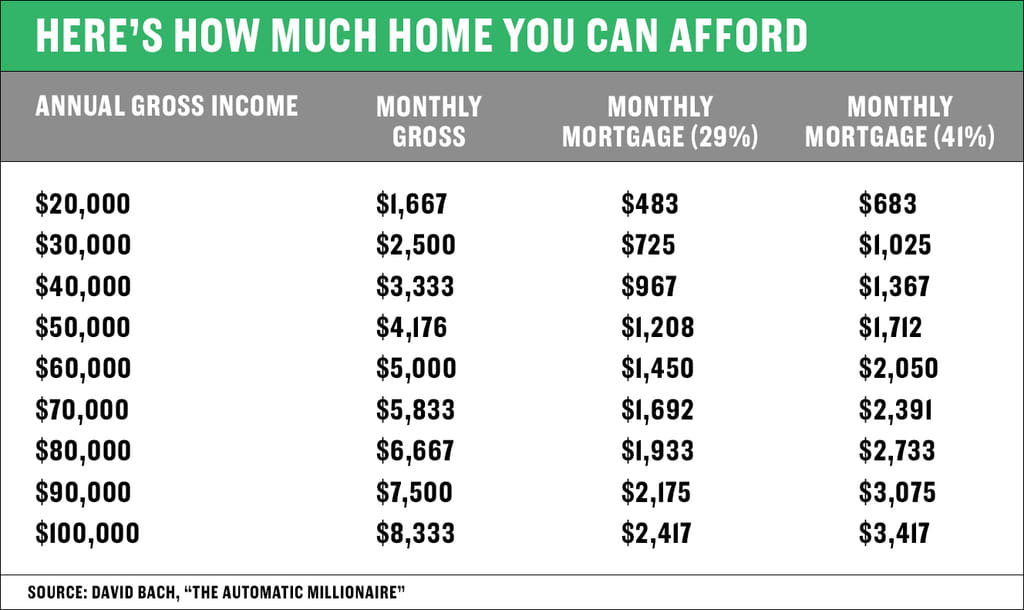
So, you're thinking about buying a home, huh? Welcome to the big leagues, buddy! You're about to embark on a journey that's part excitement, part confusion, and all kinds of fun. Let's dive into the nitty-gritty of figuring out how much home you can realistically afford. Grab a cup of coffee, get comfy, and let's chat like we're old pals.
First Things First: The Big Picture
Imagine you're at a buffet. You've got your plate, and you're eyeing up the prime rib, the crab legs, and the chocolate lava cake. But hold on a sec, you've also got to leave room for some veggies and a drink, right? Buying a home is kinda like that. You've got to consider the whole meal, not just the main course.
Income: The Main Course
Let's start with your income. It's the main event, the star of the show. Most financial gurus suggest spending no more than 28% of your gross monthly income on housing. That includes your mortgage, property taxes, insurance, and utilities. So, if you're bringing home $5,000 a month, you should be looking at homes that cost around $1,400 a month to maintain.
Must Read
But wait, you say. I make $5,000 a month, and I've got student loans, credit card debt, and a pet unicorn that eats $500 worth of glitter a month. Okay, okay, let's adjust that number. Some experts suggest the 28% rule is too generous and recommend aiming for 25% or even less. It's all about what you can comfortably afford.
Debt: The Unwanted Side Dish
Speaking of debt, let's talk about that. Lenders typically want your total debt payments (including your new mortgage) to be no more than 43% of your income. So, if you're spending $1,000 a month on debt, you should be looking at homes that cost around $1,100 a month to maintain.
Think of debt like that cousin who always crashes your parties. You love 'em, but they can be a real drain on your resources. The less debt you have, the more money you'll have for your new home and all the fun stuff that comes with it (like furniture that doesn't come from IKEA).
Now, Let's Talk About Savings
You know what's not fun? Eating a whole plate of buffet food and then realizing you've got no room left for dessert. That, my friend, is the story of not having enough savings. When you're buying a home, you need to have some cash on hand for a down payment, closing costs, and moving expenses.
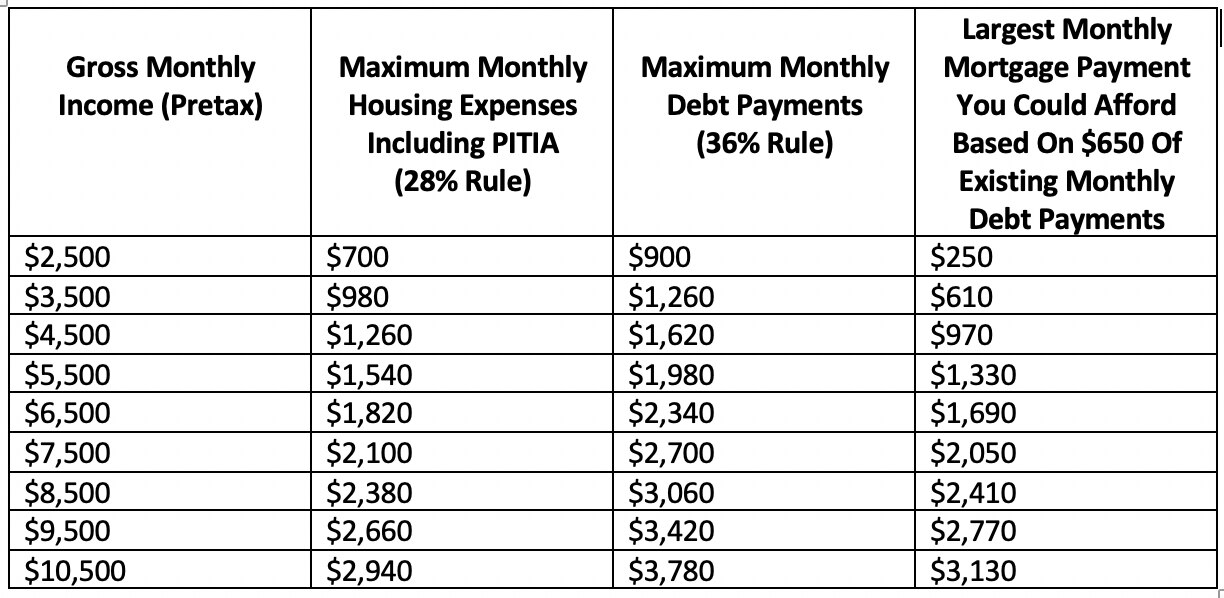 Housing Budget Calculator at Andrea Mcclelland blog
Ideally, you should aim to put down at least 20% of the home's purchase price. That might sound like a lot, but it helps you avoid private mortgage insurance (PMI) and gives you some negotiating power. Plus, it's just good practice to have some savings stashed away for a rainy day.
Location, Location, Location
You've probably heard that real estate is all about location, location, location. Well, it's true. Where you buy can have a big impact on how much home you can afford. If you're looking in a hot market like San Francisco or Manhattan, you're going to need a bigger budget (and maybe a trust fund). But if you're open to exploring less expensive areas, you might be surprised at what you can find.
Think of it like dating. You might have your heart set on that supermodel who's way out of your league. But then you meet someone who's just as amazing, but a little more attainable. That's what exploring different locations can do for your home-buying prospects.
So, How Much Can You Really Afford?
Alright, let's do some math. Let's say you make $60,000 a year, have $10,000 in savings, and $500 in monthly debt payments. Using the 25% rule for housing, you can afford a home that costs around $1,500 a month to maintain. With a 20% down payment, that means you can afford a home that costs around $180,000.
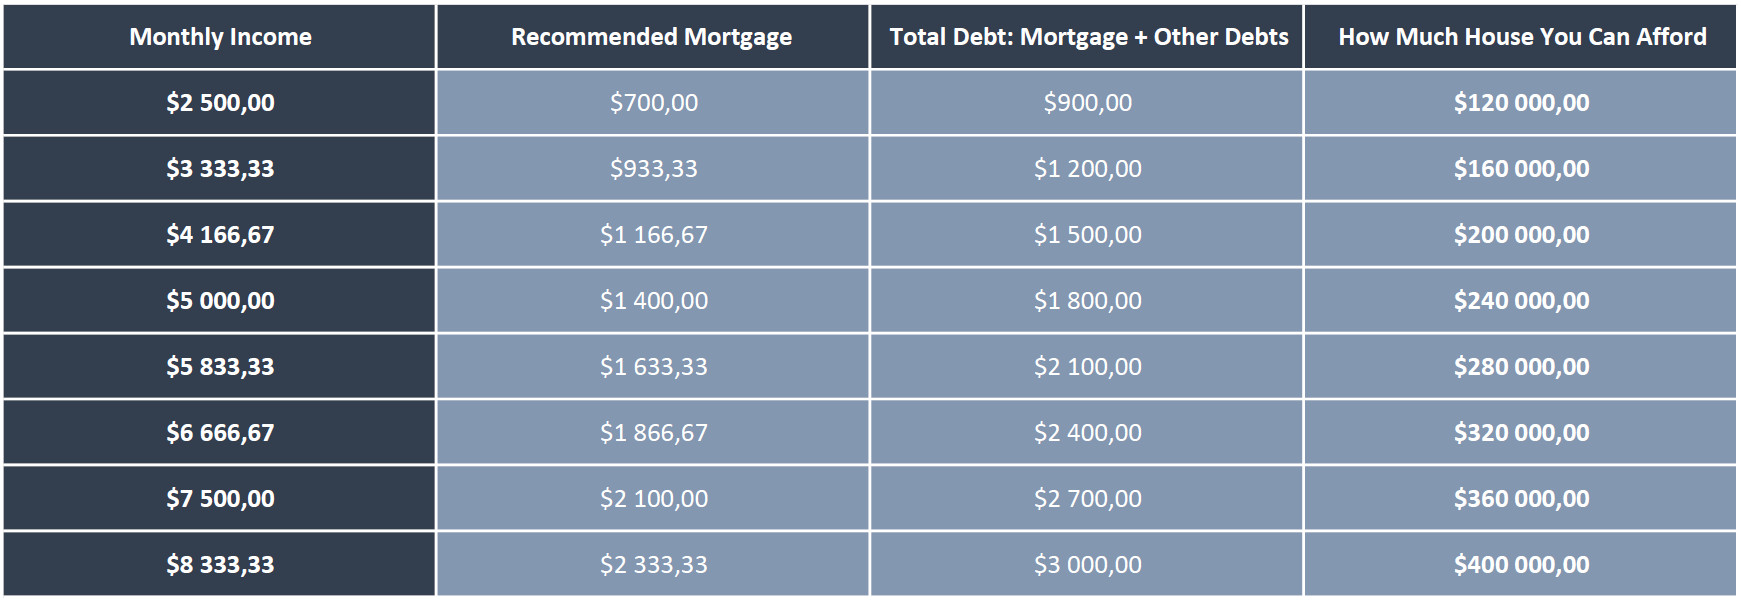 How Much House Can I Afford? Quick Guide To Home Affordability
But remember, that's just a starting point. You've also got to consider things like property taxes, homeowners insurance, and maintenance costs. And don't forget about all the fun stuff you want to do with your new home, like hosting parties, planting a garden, or building a treehouse (just me?).
Final Thoughts: It's Okay to Start Small
You might be dreaming of a McMansion with a pool, a home theater, and a guest house for your cousin who always crashes your parties. But remember, it's okay to start small. You don't have to buy your dream home right off the bat. Sometimes, the best homes are the ones you grow into.
Think of it like your career. You might start out in an entry-level position, but with hard work and dedication, you can work your way up to the corner office. The same goes for homeownership. You might start with a cozy starter home, but with some elbow grease and a little bit of luck, you can turn it into something amazing.
So, go ahead, take that first step. Figure out how much home you can realistically afford, and then go out there and make it happen. You never know what amazing things you'll find along the way.
