How Much Fees To Buy A House

Ever wondered, "How much does it really cost to buy a house?" I mean, aside from the obvious price tag, what other costs are we looking at here? Let's dive into this, shall we...

Ever wondered, "How much does it really cost to buy a house?" I mean, aside from the obvious price tag, what other costs are we looking at here? Let's dive into this, shall we?
So, What's the Big Ticket Item?
The most obvious cost is the purchase price of the house itself. This is what gets all the headlines, and it's the number that'll make your eyes widen or your heart flutter. But hold on to your hats, because there's more to this story.
Let's say you've found your dream home and the seller's asking for $300,000. That's a hefty sum, right? But wait, that's not all, folks. There are more costs lurking around the corner, like a friendly neighborhood raccoon.
Must Read
Down Payment: The First Hurdle
First up, we've got the down payment. This is the chunk of cash you put down to secure the loan. The bigger the down payment, the less you'll need to borrow, and the lower your monthly payments will be. A common down payment is around 20% of the purchase price, which in our example would be $60,000. That's like buying a nice car, isn't it? But instead of driving it off the lot, you're driving a key into a new lock.
But here's a fun fact: You don't always need to put down 20%. Some loans require as little as 3% or even 0%. It's like ordering a pizza with extra toppings, but you're only paying for the cheese.
Closing Costs: The Hidden Fees
Next, we've got closing costs. These are the fees that pop up at the end of the buying process, like a party crasher at a surprise party. They can range from 2% to 5% of the purchase price, so in our example, that's between $6,000 and $15,000. Yikes!
These costs can include fees for the loan origination, appraisal, home inspection, title search, and more. It's like ordering a meal at a restaurant, but then the waiter brings you a separate bill for the salt and pepper.
But Wait, There's More!
Alright, so you've got the down payment and closing costs covered. You're feeling pretty good about yourself, right? Well, hold on to your hats, because we're not done yet.
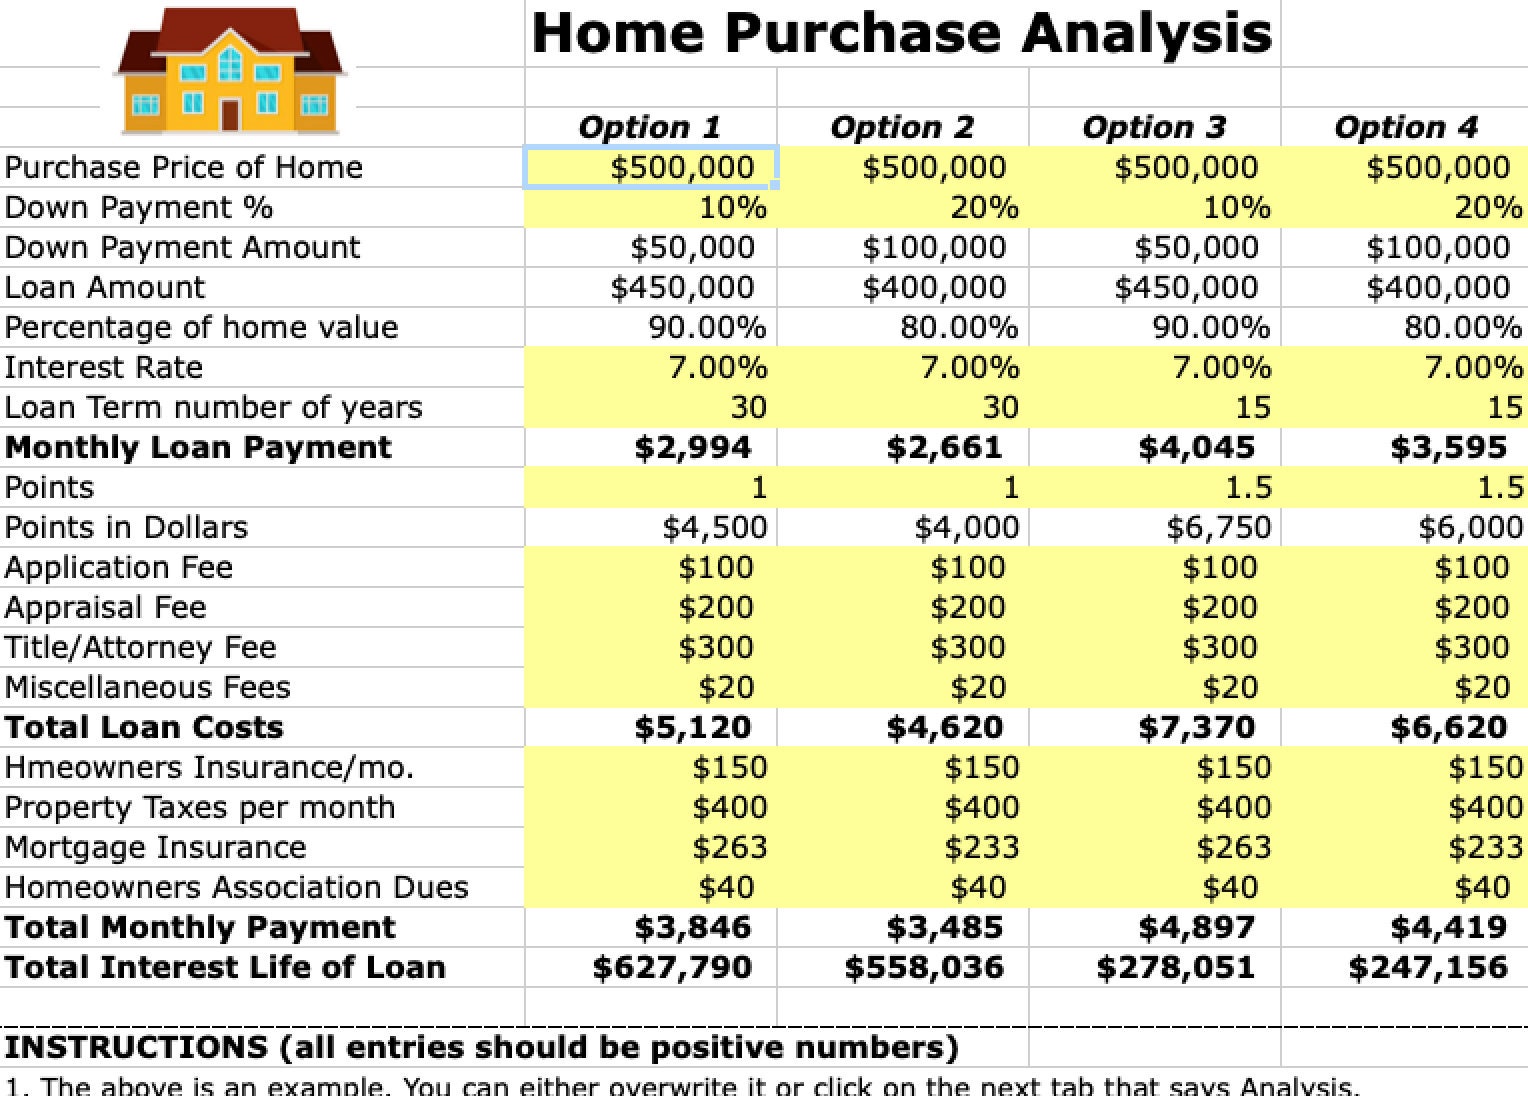 How To Plan For Major Home Expenses — Yongnam
There are also ongoing costs to consider. These are the expenses that keep on giving, long after you've moved in. They include things like property taxes, homeowners insurance, utilities, maintenance, and repairs.
Property taxes can vary widely depending on where you live. In some places, they're a tiny fraction of the home's value, while in others, they can be as high as 2% of the home's value each year. That's like paying rent on your property, even after you've bought it.
Homeowners insurance is another ongoing cost. This protects your home and belongings from damage or theft. The cost can vary depending on your location and the value of your home, but it's typically a few hundred dollars a year.
Then there are the utilities, like electricity, water, gas, and internet. These can vary depending on your usage and the time of year, but they're a necessary evil, like paying for your morning coffee.
And let's not forget maintenance and repairs. Things break, and they need fixing. Some people set aside a certain amount each month for these unexpected expenses. It's like saving for a rainy day, but with a leaky roof.
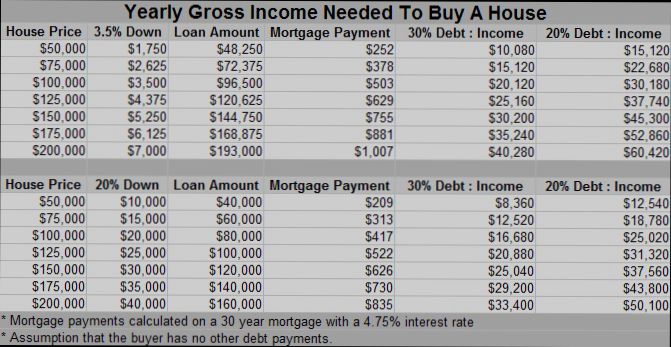 How Much Money Do You Need to Buy a House
So, How Much Does It Really Cost?
Alright, let's add it all up. In our example, the purchase price is $300,000. If you put down 20% as a down payment, that's $60,000. Closing costs could be around $10,500 (let's take the average of 3.5%). So, that's $370,500 so far.
Property taxes and homeowners insurance could add another $6,000 to $12,000 a year, depending on where you live. That's like buying a new TV every year, but instead of binge-watching, you're binge-paying.
And then there are the ongoing utilities, maintenance, and repairs. These can vary widely, but let's say you set aside $5,000 a year for these expenses. That's like buying a new wardrobe every year, but instead of new clothes, you're getting new pipes.
So, in our example, the total cost over the first year could be around $386,500 to $402,500. That's a lot of zeros, isn't it? But remember, this is just an example. Your costs could be higher or lower, depending on your situation.
And hey, don't forget, you're not just buying a house. You're buying a home. A place to make memories, to grow, to live. It's an investment, not just in property, but in your future. So, is it worth it? That's a question only you can answer.
