How Much Equity Can I Take Out Of My House

Alright, picture this: You're sitting in your cozy living room, sipping on your favorite beverage, and suddenly, you get this brilliant idea. "Hey," you think to yourself, "I...

Alright, picture this: You're sitting in your cozy living room, sipping on your favorite beverage, and suddenly, you get this brilliant idea. "Hey," you think to yourself, "I could totally turn my house into an ATM!" Now, before you start drilling holes in your walls, let's chat about how much equity you can actually tap into from your humble abode.
So, What's This Equity Thingy?
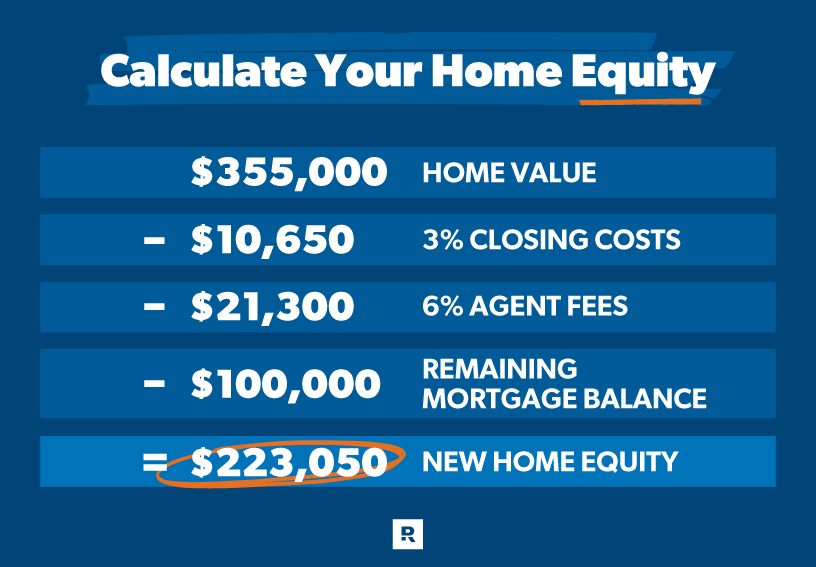
Equity, my friend, is like the cool kid at the party. It's the difference between what your house is worth and what you owe on it. For instance, if your house is worth $300,000 and you've got a mortgage of $150,000, then you've got $150,000 of equity. It's like having a secret stash of cash hidden under your mattress, but instead of ones and fives, it's in the form of bricks and mortar.
Now, How Much Can I Take Out?
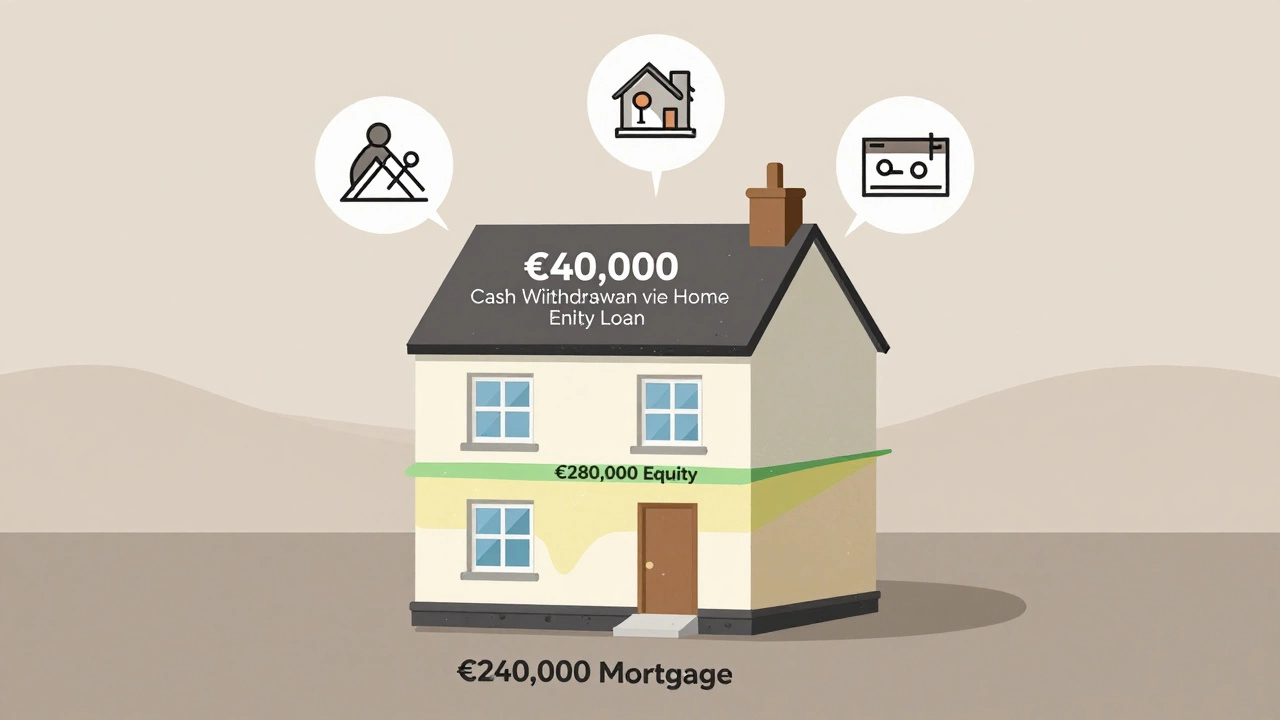
Well, it depends on how much your lender is willing to let you tap into. Most lenders will let you borrow up to 80% of your home's value, minus what you already owe. So, using our earlier example, if your lender is willing to lend you up to 80% of your home's value, you could potentially borrow $240,000 (80% of $300,000). But remember, you've already got a mortgage of $150,000, so you could potentially take out another $90,000.
Must Read
But hold your horses! Lenders usually have a minimum amount they're willing to lend, which is typically around $10,000 to $15,000. So, if you're looking to borrow less than that, you might be out of luck.
Why Would You Want to Take Out Equity?
Great question! People tap into their home equity for all sorts of reasons. Some use it to consolidate debt, others use it to fund home improvements, and some even use it to start a business. It's like having a magical piggy bank that you can crack open whenever you need a little extra cash.
 How to Own Your Dream Home - Ramsey
But remember, just because you can tap into your equity, doesn't mean you should. It's a big decision that comes with its own set of risks and rewards. So, it's always a good idea to do your homework and talk to a financial advisor before you make any big decisions.
What Are the Risks?
Well, for starters, you're turning unsecured debt (like credit card debt) into secured debt. That means if you can't make your payments, your lender could foreclose on your home. It's like trading in your fancy sports car for a beat-up old sedan - sure, it might be more reliable, but it's also a lot harder to lose.
Plus, if your home's value drops, you could end up owing more than your home is worth. It's like buying a new TV right before the store goes out of business and the price drops by half. You're stuck with a TV that's worth less than what you paid for it.
 Can I Take Equity Out of My House Without Refinancing? Here’s How
So, Should You Tap Into Your Equity?
That, my friend, is the million-dollar question. If you're looking to consolidate debt, fund home improvements, or start a business, tapping into your equity could be a great option. But if you're just looking to buy a fancy new car or go on a lavish vacation, you might want to think twice.
Remember, your home is your castle, and your equity is the treasure hidden within. You wouldn't just give your treasure away to the first pirate who asks, would you? So, do your homework, talk to a financial advisor, and make sure you're making the right decision for you and your family.
And hey, if all else fails, you could always try selling your plasma or becoming a professional banana baker. I hear there's a big market for that sort of thing these days. But that's a story for another time.
