How Much Can I Borrow Second Mortgage

So, You're Thinking About a Second Mortgage, Eh? Alright, let's dive into the world of second mortgages. It's like having a secret stash of cash hidden behind your main loan....

So, You're Thinking About a Second Mortgage, Eh?
Alright, let's dive into the world of second mortgages. It's like having a secret stash of cash hidden behind your main loan. But how much can you borrow? Let's find out!
First Things First: What's a Second Mortgage?
A second mortgage is like having a backup loan on your home. It's secured by your property, just like your first mortgage. But remember, it's a big deal. You're putting your home on the line, twice!
Now, let's talk numbers. How much can you borrow? Well, it depends on a few things. Buckle up, we're going on a little ride through the factors that matter.
Must Read
Factor 1: Your Home's Value
Imagine your home is a big, delicious cake. The more it's worth, the bigger the slice you can have. That's basically how lenders see it. They'll lend you a percentage of your home's value, minus what you still owe on your first mortgage.
For example, if your home is worth $300,000, and you've paid off $150,000 of your first mortgage, you might be able to borrow up to 80% of the remaining $150,000. That's $120,000!
Factor 2: Your Credit Score
Your credit score is like your financial report card. The better it is, the more lenders will trust you with a bigger loan. But if it's not so hot, don't worry, you can still borrow, just maybe not as much.
For instance, if you have excellent credit, you might be able to borrow up to 100% of your home's value (minus your first mortgage, of course). But if your credit is fair, you might only be able to borrow up to 80%.
Factor 3: Your Debt-to-Income Ratio
Your debt-to-income ratio is like a balance scale. It compares how much you earn to how much you owe. Lenders want to see that you're not already drowning in debt before they throw you a life jacket in the form of a loan.
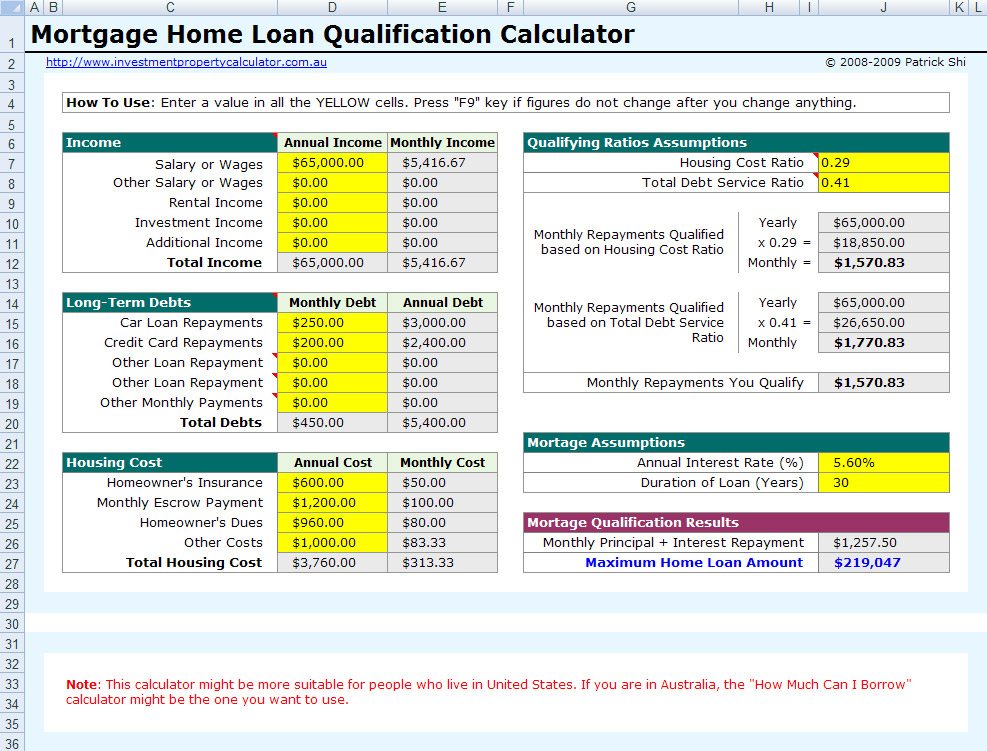 Free Mortgage How Much Can I Borrow Calculator
Ideally, your total debts (including your new mortgage payment) shouldn't be more than 43% of your income. So, if you earn $5,000 a month, your total debts shouldn't exceed $2,150.
So, How Much Can You Really Borrow?
Let's say you have a home worth $300,000, with $150,000 left on your first mortgage. You have excellent credit and a debt-to-income ratio of 30%. You could potentially borrow up to $120,000 with a second mortgage!
But remember, this is just an example. Your situation might be different. That's why it's always a good idea to talk to a lender. They can give you a more accurate estimate based on your specific circumstances.
Why a Second Mortgage? Why Not?
So, why would you want a second mortgage? Well, it could be to consolidate debt, make home improvements, or even start a business. But it's not all sunshine and roses. You're putting your home at risk, and you'll have to make another mortgage payment every month.
But hey, it's your call. Just make sure you understand the pros and cons before you dive in. And remember, it's always a good idea to have a financial plan. It's like having a map when you're lost in the woods. You might not know exactly where you're going, but at least you have an idea!
And there you have it! The fun and fabulous world of second mortgages. Now go forth, borrower, and may the odds be ever in your favor!
