How Much Can I Borrow On Buy To Let

So, I was chatting with my mate, Jack, the other day. He's been eyeing this sweet little flat in the heart of the city. Not for him to live in, mind you, but to rent out. He's...
So, I was chatting with my mate, Jack, the other day. He's been eyeing this sweet little flat in the heart of the city. Not for him to live in, mind you, but to rent out. He's got the bug, you see - the buy-to-let bug. I could see the cogs turning in his head, calculating potential yields, imagining a stream of tenants rolling in like clockwork. But then he hit a snag. He turned to me, eyes wide, and asked, "How much can I actually borrow for this?"
Now, Jack's not alone in wondering this. It's a question that's been keeping many a would-be landlord up at night. So, let's dive in, shall we?
First Things First: What's Your Deposit?
Before we even think about how much you can borrow, let's talk about the elephant in the room - the deposit. Lenders typically want you to stump up at least 25% of the property's value. That's right, folks, you're gonna need some serious cash up front. But why so much? Well, it's to protect the lender. If you can't keep up with the repayments, they want to know they can sell the property and get their money back.
Must Read
Now, I know what you're thinking, "But why 25%? That's a lot!" And you're right, it is. But don't worry, there are ways to reduce it. Some lenders will accept a 20% deposit, and some even go as low as 15%. But remember, the less you put down, the more you'll pay in the long run. It's a balancing act, folks.
Now, Let's Talk Borrowing
Alright, so you've got your deposit sorted. Now, how much can you borrow? Well, that depends on a few things. First up, lenders will look at your income. They'll want to know you can afford the repayments. Typically, they'll lend you up to 4.5 times your salary. So, if you're earning £50,000 a year, you could potentially borrow up to £225,000.
But wait, there's more! Lenders will also consider the property's rental yield. That's the annual rent divided by the property's value, expressed as a percentage. They'll usually want to see a yield of at least 25% of the mortgage repayments. So, if your repayments are £1,000 a month, they'll want to see a rental income of at least £3,000 a year.
 How much can I borrow? - Buy to let mortgage | Best Buy to Let
Stress Tests and Interest Cover Ratios
Now, lenders aren't just interested in whether you can afford the repayments now. They want to know you can afford them if interest rates go up. That's where stress tests come in. They'll calculate what your repayments would be if interest rates were, say, 3% higher, and check you can still afford them.
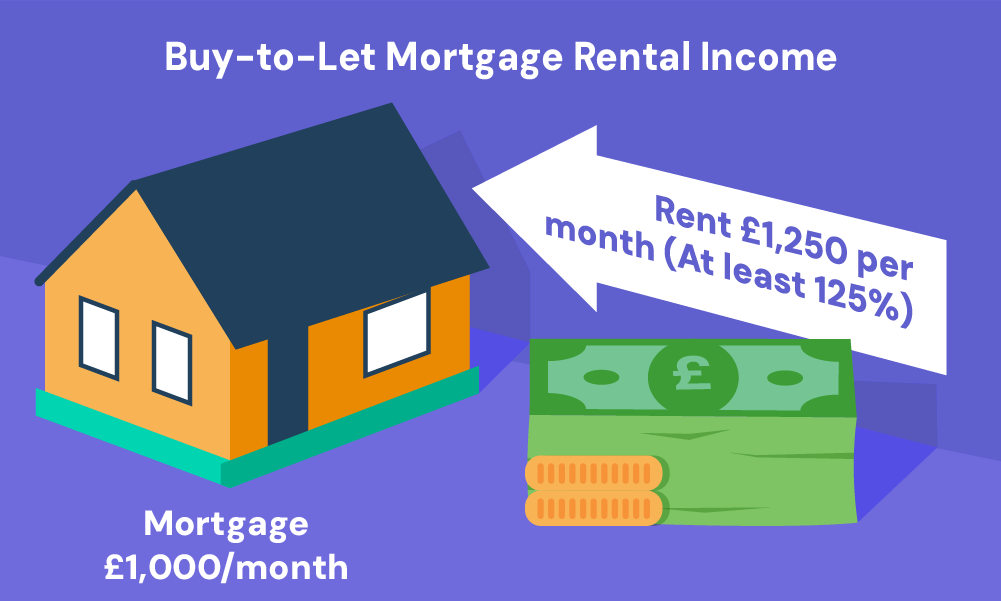
Similarly, they'll look at your interest cover ratio. This is your rental income divided by your mortgage repayments. They'll want to see a ratio of at least 125%. So, if your repayments are £1,000 a month, they'll want to see a rental income of at least £1,500 a year.
Other Factors to Consider
Alright, so we've talked about income, deposits, and affordability. But there are other factors lenders will consider. Your credit score is a big one. If you've got a history of missed payments or defaults, you might struggle to get a mortgage. And if you do, it'll likely come with a higher interest rate.
 Does having a buy-to-let mortgage affect how much you can borrow
Then there's the property itself. Lenders will want to know it's in good nick and that it's got a good chance of increasing in value. They'll also consider the type of property it is. Some lenders won't touch flats above a certain number of floors, for example.
So, How Much Can You Borrow?
Phew, that's a lot to take in, isn't it? So, let's get back to Jack. Based on his income and the property he's looking at, he could potentially borrow up to £180,000. But remember, that's just an estimate. The actual amount will depend on a whole host of factors.
And that's the thing, folks. There's no one-size-fits-all answer to the question "How much can I borrow?" It's all about your individual circumstances. So, if you're thinking about taking the plunge into buy-to-let, do your homework. Crunch the numbers, talk to lenders, and make sure you know what you're getting into.
And as for Jack? Well, he's still crunching those numbers. But he's one step closer to becoming a landlord. And who knows? Maybe one day, he'll be the one giving advice to his mates.
