How Does A Cash Out Refinance Work

Alright, gather 'round, folks. I've got a tale to tell about something called a "cash-out refinance." Now, don't go running off thinking I'm about to bore you with financial j...
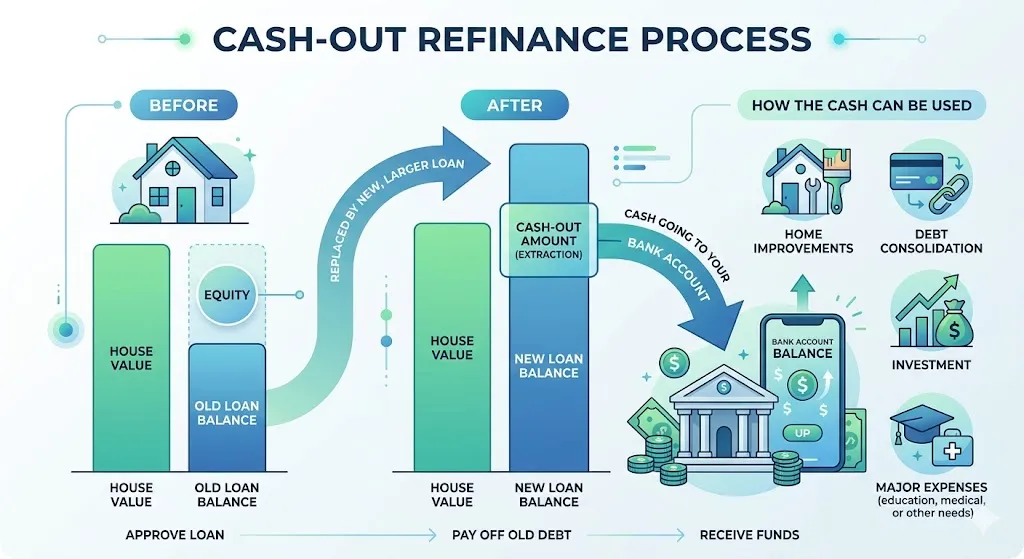
Alright, gather 'round, folks. I've got a tale to tell about something called a "cash-out refinance." Now, don't go running off thinking I'm about to bore you with financial jargon. No, no, this is a story about turning your home into a magical money-box, straight out of a fairy tale. Well, almost.
So, What's the Deal with This Cash-Out Thing?
Imagine you've got a house, a lovely little abode you've been paying off for years. Now, you're thinking, "Hey, I've built up some equity here. I could use some of that cash for, I don't know, a fancy vacation, a new car, or maybe even starting a business." Enter the cash-out refinance, the fairy godmother of home loans.
In simple terms, a cash-out refinance replaces your current mortgage with a new, bigger loan. You get to keep the difference in cash. It's like trading in your old car for a new one, but instead of a car, it's your house, and instead of driving off the lot, you're driving off to the bank with a wad of cash.
Must Read
But Wait, There's More!
Now, here's where it gets a bit like one of those infomercials you see at 3 AM. "But how much can I get?" you ask. Well, that depends on how much equity you've built up. Typically, you can borrow up to 80% of your home's value. So, if your home is worth $300,000 and you've paid off $150,000, you could potentially walk away with $90,000.
But remember, folks, this isn't a get-rich-quick scheme. You're turning long-term wealth (your home equity) into short-term cash. It's like trading in your retirement fund for a new TV. Sure, you get to enjoy it now, but you've got to think about the future too.
Now, Let's Talk About Rates and Fees
You might be thinking, "This sounds too good to be true!" Well, hold onto your hats because here comes the fine print. Cash-out refis usually come with higher interest rates than regular refinances. Why? Because lenders see them as riskier. After all, you're borrowing more money and using it for, well, who knows what?
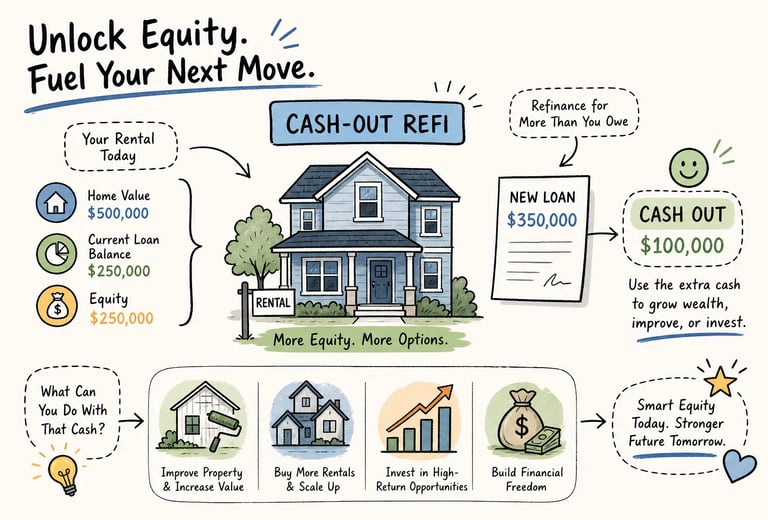 Rental Property Cash-Out Refi: Rules, Math & Strategy | Cape Henry Capital
And then there are the fees. You've got closing costs to consider, just like when you first bought your house. These can run you anywhere from 2% to 5% of the loan amount. So, if you're borrowing $100,000, that's $2,000 to $5,000 right off the top.
But What If I Don't Pay Back?
Here's where the story takes a bit of a dark turn. If you can't make your payments, you could lose your home. It's like that scene in "The Wolf of Wall Street" where Jordan Belfort loses his mansion. Except, you know, without the dramatic music and Leonardo DiCaprio's charming smile.
So, before you dive in, make sure you've got a solid plan for that cash. And remember, a cash-out refinance is a tool, not a magic wand. It can help you achieve your goals, but it's up to you to wave it responsibly.
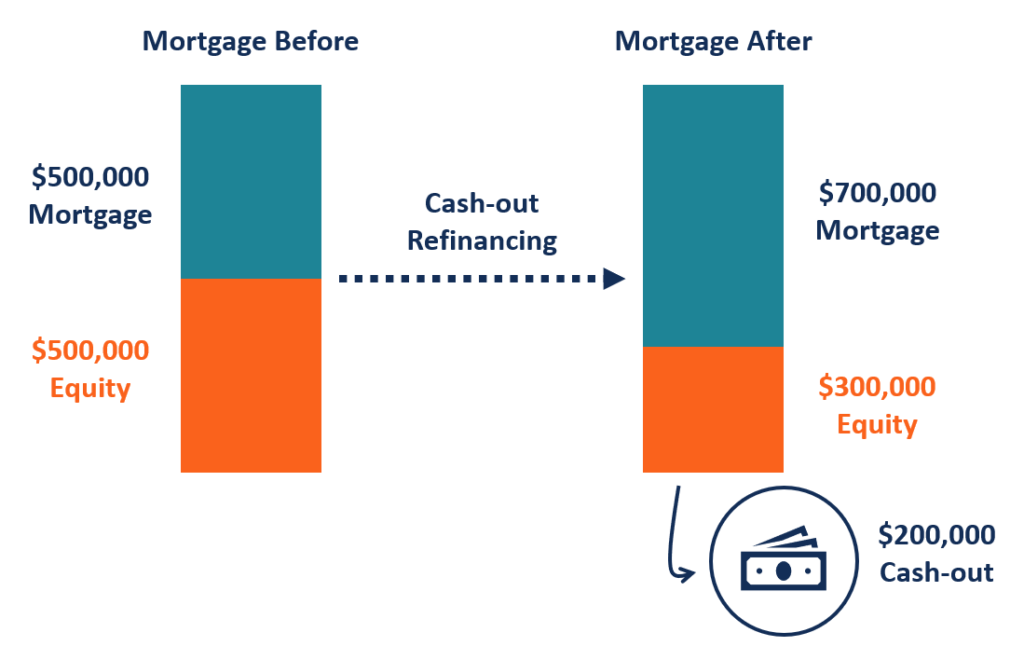 Cash-Out Refinance - Overview, How It Works, Example
So, Should You Do It?
Well, that depends. Are you looking to consolidate high-interest debt? Maybe you're planning to use the cash to make home improvements that will increase your home's value. Or perhaps you're looking to invest in a business or real estate. If you've got a solid plan and you're comfortable with the risks, a cash-out refinance could be just the ticket.
But if you're thinking, "I could really use some extra cash to fund my pyramid scheme/jet-ski habit/collection of vintage rubber ducks," well, maybe it's time to reevaluate your priorities.
And there you have it, folks. The cash-out refinance, explained. It's not as exciting as a real-life fairy tale, but it's a whole lot more practical. Just remember, when it comes to your home and your money, it's always best to keep your wits about you. Now, who's ready for another round of coffee?
