How Do Student Loans Impact Credit Score

Alright, gather 'round, folks. I've got a tale to tell about student loans and credit scores. Now, I know what you're thinking, "This guy's about to bore us to tears with fina...
Alright, gather 'round, folks. I've got a tale to tell about student loans and credit scores. Now, I know what you're thinking, "This guy's about to bore us to tears with financial jargon." But fear not, dear listeners, for I come bearing humor, exaggeration, and even a surprising fact or two. Let's dive in, shall we?
First things first: What's a credit score?
Imagine your credit score is like your financial Tinder profile. It's a number that tells lenders, "Hey, I'm responsible with money, swipe right!" or "Uh-oh, I've got some explaining to do, left swipe." Now, you might be thinking, "But I'm a student, I haven't even had time to mess up my credit yet!" Well, hold onto your hats, because student loans are about to change that.
Enter: Student Loans
Student loans are like that annoying friend who crashes on your couch for months, eats all your food, and never helps with rent. You didn't ask for them, but here they are, and now you've got to figure out how to make it work. The difference? These loans actually expect you to pay them back. With interest. Ugh, interest. But more on that later.
Must Read
Now, you might be wondering, "How do these pesky loans affect my shiny new credit score?" Well, grab a snack, because it's story time.
Late payments: The original party foul
Picture this: You're at a party, having a great time, when suddenly, you realize you've missed your student loan payment. Oops. Now, your lender is like that one friend who's always on your case about being responsible. They report your late payment to the credit bureaus, and bam! Your credit score takes a hit. It's like showing up to the party with spinach in your teeth - nobody wants that.
But don't despair, young grasshopper. Late payments aren't the end of the world. They just stay on your report for seven years. Seven years! That's like the entire lifespan of a mayfly, but for your credit score. Cheery thought, huh?
Credit utilization: The mysterious dance
Now, let's talk about credit utilization. It's like trying to figure out the mysterious dance moves of your weird cousin at a wedding. You know, the one who's always doing the macarena when nobody else is. In this case, your weird cousin is your credit limit, and the macarena is the amount you've borrowed.
Here's the thing: Lenders like to see that you're using less than 30% of your available credit. So, if you've got a $10,000 credit limit, you should aim to borrow less than $3,000 at a time. It's like having a buffet of credit, and you're only allowed to take a small plate. Sad face.
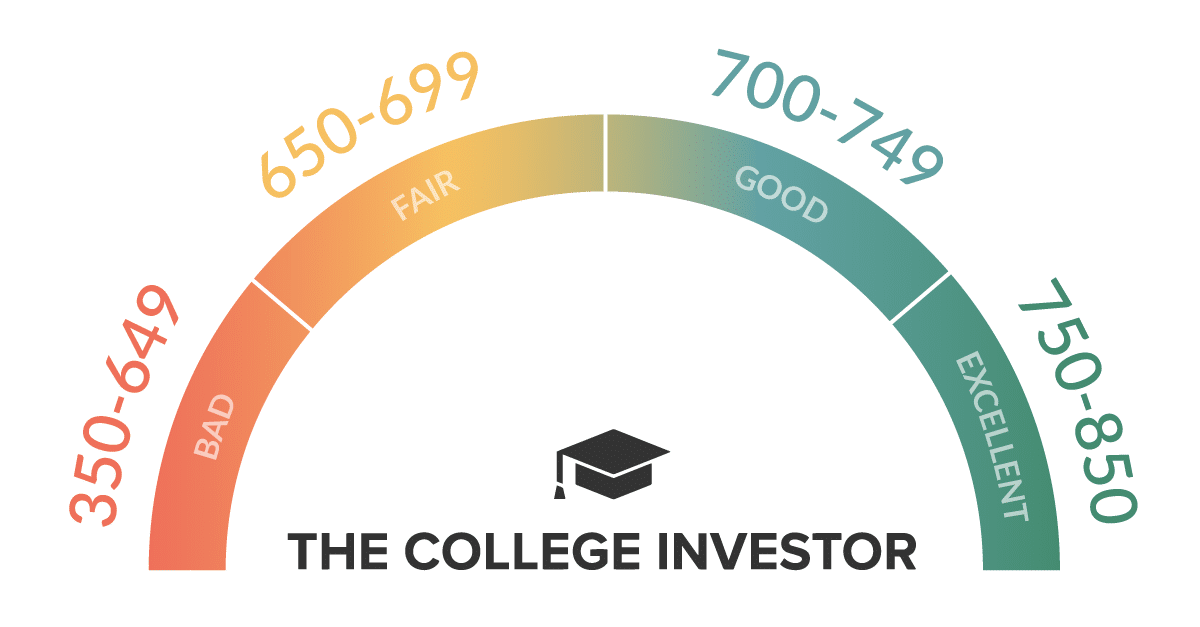 How Do Student Loans Impact Your Credit Score?
Credit history: The longer, the better
Remember when you were a kid, and you'd tell your parents, "But everybody else's parents let them do it!" Well, when it comes to credit scores, lenders are like your parents, and they want to see a long, steady history of responsible borrowing. That's why student loans can actually help your credit score, as long as you're making those payments on time.
Think of it like this: You're at a fancy dinner party, and the host asks, "How long have you been using credit responsibly?" You want to say, "Oh, gosh, like, forever!" The longer your credit history, the more impressed the host will be. And who doesn't want to impress the host at a fancy dinner party?
Interest: The sneaky ex
Alright, let's talk about interest. It's like that sneaky ex who keeps popping up in your life, even though you thought you'd finally moved on. You know, the one who's always like, "Hey, remember me? I'm here to take more of your money." Yeah, that's interest for you.
Here's the thing: Interest can really mess with your credit utilization ratio. Let's say you've borrowed $10,000, and your lender charges 6% interest per year. After a year, you've got $10,600 in debt. Now, if your credit limit is $11,000, you're suddenly using 96% of your available credit. Oops. That's like showing up to the party with spinach in your teeth and a lampshade on your head. Not a good look.
But wait, there's more!
You might be thinking, "Okay, okay, I get it. Student loans can mess with my credit score. But what can I do about it?" Well, grab a pen and paper, because I'm about to drop some knowledge bombs.
 Do Student Loans Affect Credit Scores?
Pay on time, every time
This one's a no-brainer. Set up automatic payments, or at least reminders, to make sure you're paying on time. It's like having a responsible friend who's always there to remind you to do your chores. You know, the friend you never knew you needed.
Keep your balances low
Remember our friend credit utilization? The lower your balances, the better. So, try to pay down your loans as fast as you can. It's like having a buffet of credit, and you're only taking a small plate. Again. Sad face.
Be patient
Building credit takes time. It's like watching a plant grow. You can't rush it, and you can't make it grow faster by staring at it. So, be patient, and keep making those payments. Your credit score will thank you in the long run.
And that, my friends, is the tale of student loans and credit scores
It's not all doom and gloom, though. With a little bit of responsibility and a lot of patience, you can turn those student loans into a credit score that'll make even the most discerning lenders swoon. So, go forth, young grasshoppers, and conquer the world of finance. Just remember to pay your bills on time.
And with that, I've reached the end of my tale. I hope you've learned a thing or two, and maybe even laughed a little. Now, who's ready for another round of drinks? I'm parched.
