How Do I Release Equity In My House

Hey there, homeowner! Ever found yourself daydreaming about that dream vacation, fancy car, or even just a well-deserved shopping spree, but your house seems to be holding ont...
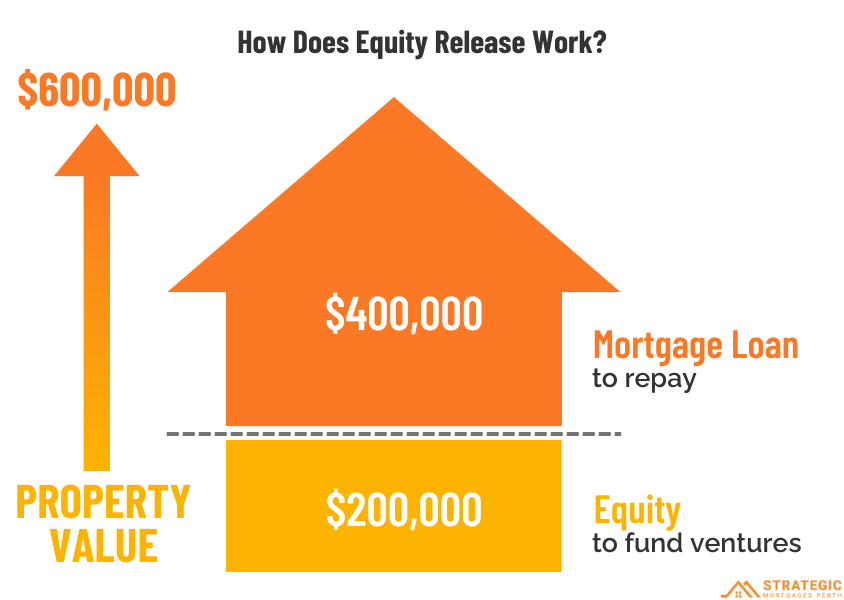
Hey there, homeowner! Ever found yourself daydreaming about that dream vacation, fancy car, or even just a well-deserved shopping spree, but your house seems to be holding onto your cash like a squirrel with a nut? Well, let's chat about how you can release some of that equity and make your home work for you, not the other way around.
First things first, what's this equity business all about?
Alright, imagine you've just bought a house for $200,000, and after a few years, the value has shot up to $300,000. That $100,000 difference is your equity - it's like your home's savings account, growing over time as its value increases or you pay off your mortgage.
Now, how do I get my hands on some of that cash?
There are a couple of ways to tap into your home's equity, and we're going to chat about two popular ones: refinancing and home equity loans.
Must Read
Refinancing: The 'I want a new mortgage' approach
Refinancing is like trading in your old mortgage for a new one. You take out a new loan for the current value of your home, pay off your old mortgage, and voila! You've got some extra cash in your pocket. But remember, you're essentially starting your mortgage journey all over again, so it's important to crunch those numbers and make sure it's worth it in the long run.
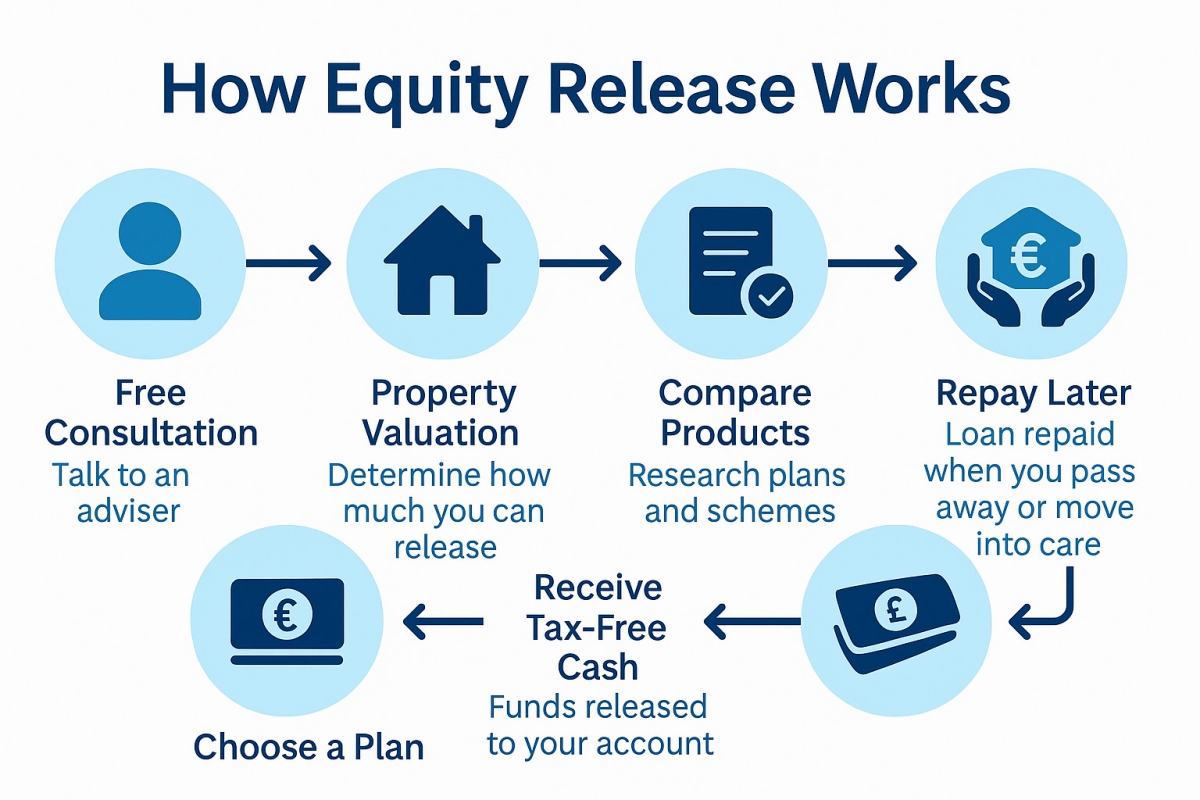 Is Equity Release a Good Idea? | Award-Winning Advice from My Later
Pros of refinancing:
- Access to a lump sum of cash upfront.
- You can consolidate debts or lower your monthly payments.
Cons of refinancing:
- You'll have to pay closing costs again, which can add up.
- You'll be starting your mortgage journey over, which means more time paying interest.
Home Equity Loans: The 'I just want a loan' approach
Home equity loans are like a second mortgage. You borrow against the equity you've built up in your home, and you get a lump sum of cash. The catch? You're adding another mortgage payment to your monthly expenses. But hey, at least you're not refinancing your entire mortgage, right?
Pros of home equity loans:
- You get access to a lump sum of cash without refinancing your entire mortgage.
- Interest rates are usually lower than unsecured loans.
Cons of home equity loans:
- You're adding another mortgage payment to your monthly expenses.
- If you can't make payments, you could lose your home.
So, which one's right for me?
Well, that depends on your personal financial situation. If you're looking to consolidate debts or lower your monthly payments, refinancing might be your best bet. But if you just need a lump sum of cash and don't want to mess with your mortgage, a home equity loan could be the way to go.
 How Much Can You Release With Equity Release in 2025?
Remember, it's always a good idea to talk to a financial advisor before making any big decisions. They can help you crunch those numbers and figure out what's best for you.
And there you have it!
You're now one step closer to turning your home's equity into your very own piggy bank. So go on, dream big, and remember, your home is there to support you, not the other way around. Happy equity releasing!
