How Do I Get A Full Credit Report

Unlocking Your Financial Story: A Chat About Credit Reports Ever wondered what your credit report looks like? It's like your financial fingerprint, a record of your credit his...
Unlocking Your Financial Story: A Chat About Credit Reports
Ever wondered what your credit report looks like? It's like your financial fingerprint, a record of your credit history that paints a picture of how you handle money. It's not as scary as it sounds, promise! Let's dive in and make friends with this often-misunderstood document.
Why Should You Care?
Imagine you're applying for a mortgage to buy your dream home. The lender wants to know if you're a responsible borrower, right? They'll check your credit report to see if you've been paying your bills on time, if you've had any bankruptcies, or if you've maxed out your credit cards. It's like showing your report card to your parents, but for your financial life.
But it's not just about big purchases like houses or cars. Landlords, employers, and even some insurance companies might peek at your credit report. So, it's like having a good credit report is like having a sparkling clean apartment for potential roommates to see - it makes a great first impression!
Must Read
How to Get Your Hands on Your Report
In the U.S., you're entitled to one free credit report per year from each of the three major credit bureaus - Equifax, Experian, and TransUnion. It's like a free sample of your financial story, and you should definitely take advantage of it!
To get your report, head over to AnnualCreditReport.com. It's the only website authorized by the Federal Trade Commission to provide free annual credit reports. It's as easy as filling out an online form with some personal info, like your name, address, and Social Security number.
 How To Download Experian Credit Report PDF | Robots.net
What's in Your Report?
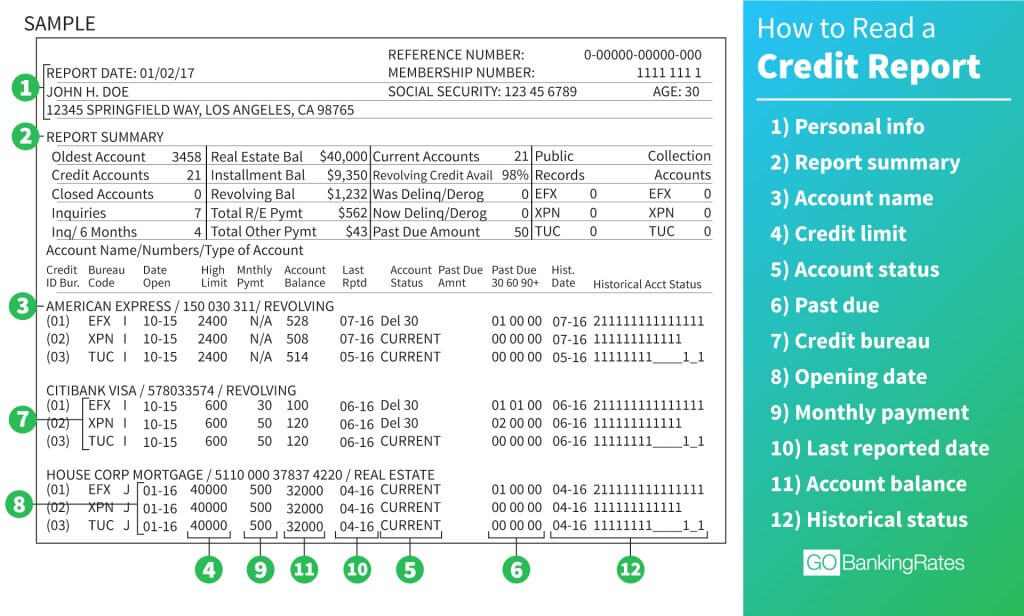
Your credit report is like a detailed résumé of your credit history. Here's what you'll find:
- Identifying Information: This includes your name, address, Social Security number, and date of birth. It's like the header on your résumé.
- Trade Lines: These are your credit accounts, like credit cards, mortgages, and car loans. Each trade line shows the creditor's name, the type of account, the date it was opened, your credit limit or loan amount, and your payment history.
- Credit Inquiries: These are records of when someone - like a lender or employer - has checked your credit report. There are two types: hard inquiries (when you've applied for new credit) and soft inquiries (when you've checked your own report or when a lender wants to send you pre-approved offers).
- Public Records and Collections: This section includes any bankruptcies, foreclosures, or lawsuits, as well as any debts that have been sent to collections. It's like the 'previous employment' section of your résumé, but hopefully, it's blank!
What to Do Once You Have Your Report
Once you've got your report, it's time to give it a good once-over. Make sure all the information is accurate and up-to-date. If you find any errors, don't panic! You can dispute them with the credit bureau. It's like finding a typo on your résumé - you want to fix it ASAP.
 Credit Reports Tutorial | Sophia Learning
After checking for errors, take a look at your payment history. If you've got any late payments or missed payments, it's time to start making amends. The longer you've gone without paying, the more it can hurt your credit score. It's like having a stack of overdue library books - the sooner you return them, the better!
Keeping Your Report in Tip-Top Shape
Now that you know what's in your credit report, you can start taking steps to keep it in great shape. Here are some tips:
- Pay your bills on time. Set up automatic payments or reminders to help you stay on track.
- Keep your credit utilization low. This means using only a small portion of your available credit. For example, if you have a credit limit of $10,000, try to keep your balance below $3,000.
- Don't open too many new credit accounts at once. Each new account can trigger a hard inquiry, which can temporarily lower your credit score.
- Monitor your credit report regularly. You can get a free copy of your credit report from each of the three major credit bureaus once a year. Space them out throughout the year to monitor your credit more frequently.
And there you have it! Your credit report isn't as scary as it seems. It's just a snapshot of your financial history, and with a little TLC, you can keep it in great shape. So go ahead, give it a hug, and let's make friends with our credit reports!
