How Do I Cash In My Savings Bonds

So, you've been sitting on a pile of savings bonds, huh? I get it, you've been waiting for the perfect moment to cash them in. Maybe you're planning a big trip, or perhaps you...
So, you've been sitting on a pile of savings bonds, huh? I get it, you've been waiting for the perfect moment to cash them in. Maybe you're planning a big trip, or perhaps you've got your eye on a shiny new gadget. Whatever your reason, you're here because you're ready to turn those colorful pieces of paper into cold, hard cash. Let's dive in!
First Things First: What Are Savings Bonds?
Alright, let's start with the basics. Savings bonds are a type of debt security issued by the U.S. Department of the Treasury. They're like an IOU from Uncle Sam, promising to pay you back the face value of the bond, plus interest, at a future date. There are two main types: Series EE and Series I bonds. Series EE bonds are tied to the inflation rate, while Series I bonds are indexed to inflation and have a fixed interest rate.
Now, you might be thinking, "Hey, I've got a stack of these things, but I have no idea what they're worth!" Don't worry, we'll get to that. First, let's talk about how to cash them in.
Must Read
Cashing In Your Bonds: The Basics
Before you head to your local bank, there are a few things you should know. Savings bonds are typically cashed in at face value, plus any accrued interest. But here's the catch: you can't cash them in until they reach their first interest accrual date. For Series EE bonds, that's one year from the issue date, and for Series I bonds, it's the first month after the issue date.
Another thing to keep in mind is that there's a waiting period after you cash in your bonds. If you cash in a bond within the first five years, you'll lose the last three months' worth of interest. So, it's best to hold onto them for at least five years if you can.
How to Cash In Your Bonds: Step-by-Step
Alright, let's get down to business. Here's how you can cash in your savings bonds:
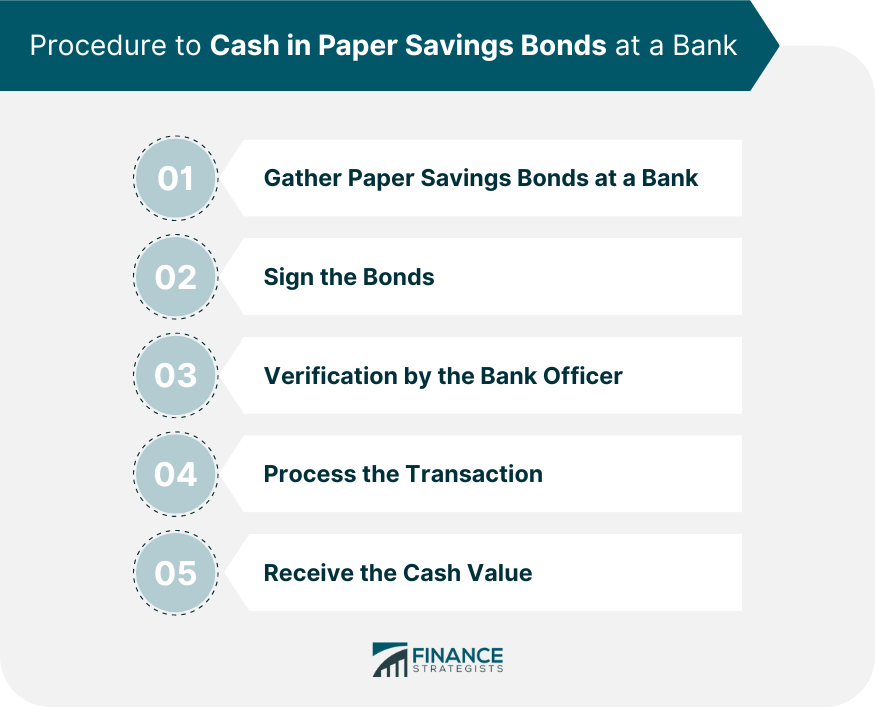
Gather your bonds. Make sure you have all the bonds you want to cash in. Check the issue dates to ensure they've reached their first interest accrual date.
Head to your local bank or credit union. You can also cash in your bonds at most banks and credit unions, even if you didn't buy them there. Just make sure they're a part of the Federal Reserve System.
 How to Cash in Savings Bonds | a Step-By-Step Guide
Fill out a form. The bank will give you a form to fill out. You'll need to provide your Social Security number, the bond's serial number, and the issue date. If the bond is registered to someone else, you'll need to provide their information too.
Show your ID. You'll need to show a valid ID, like a driver's license or passport, to prove you are who you say you are.
Wait for your money. Once the bank has verified your information, they'll give you the face value of the bond, plus any accrued interest. It's as simple as that!
What If I Lost My Bond?
Oh no, you lost your bond? Don't panic! You can still cash it in. The Treasury Department has a process for replacing lost, stolen, or destroyed bonds. You'll need to fill out a form called a Request for Replacement of a Lost, Stolen, or Destroyed Savings Bond. You'll need to provide some information about the bond, like the issue date and the serial number if you have it. There's a small fee for replacing a bond, but it's worth it to get your money back.
How Much Money Will I Get?
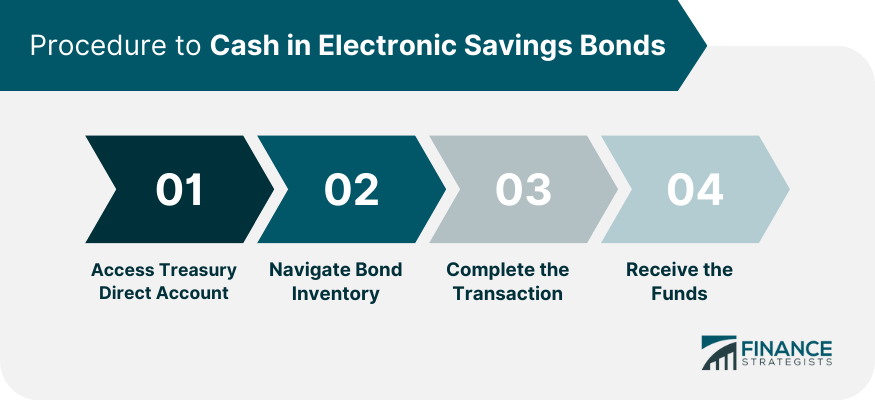
Now, you're probably wondering how much money you'll actually get when you cash in your bonds. The amount depends on the type of bond and when it was issued. You can use the Savings Bond Calculator on the Treasury Department's website to figure out the value of your bonds. Just enter the issue date and the face value, and the calculator will do the rest.
 How to Cash in Series EE Savings Bonds: 12 Steps (with Pictures)
For example, let's say you have a Series I bond with a face value of $500 that was issued in 2010. According to the calculator, that bond would be worth about $650 today. Not bad, huh?
Taxes: The Not-So-Fun Part
Before you start spending your newfound wealth, there's one more thing you need to know: taxes. The interest you earn on savings bonds is subject to federal income tax, but it's not subject to state or local income taxes. You can choose to pay the tax either when you cash in the bond or when the bond stops earning interest.
If you're a student, you might be able to exclude some or all of your bond interest from your taxable income when you use it to pay for qualified education expenses. It's a bit complicated, so you might want to talk to a tax professional if you think this applies to you.
So, What Are You Waiting For?
There you have it, folks! Cashing in your savings bonds is a lot easier than you thought, right? So, what are you waiting for? Get out there and turn those pieces of paper into cold, hard cash. Just remember to hold onto them for at least five years if you can, and keep them in a safe place until you're ready to cash them in.
And hey, if you have any questions or if there's something I missed, just let me know in the comments. I'm always here to help!
