How Can I Build Up My Credit Score

Alright, gather 'round, folks. I've got a tale to tell about credit scores. Now, don't roll your eyes, this isn't going to be some dry, boring lecture. No, no, think of it as...
Alright, gather 'round, folks. I've got a tale to tell about credit scores. Now, don't roll your eyes, this isn't going to be some dry, boring lecture. No, no, think of it as a comedy of errors, a farce of finance, a... well, you get the picture. Let's dive in, shall we?
What's the Big Deal with Credit Scores?
First things first, what's all the fuss about these mysterious three-digit numbers? Well, imagine your credit score is like your personal cheer squad at a financial pep rally. It's the one shouting "You can do it!" when you're trying to get a loan, rent an apartment, or even land a job (yes, some employers check 'em!).
The higher your score, the louder the cheer, the better the deals. But let it slip, and suddenly you're the kid at the pep rally with a megaphone that only plays static. Not cool, not cool at all.
Must Read
So, How Do I Build This Magical Cheer Squad?
Pay Your Bills on Time, You Crazy Diamond
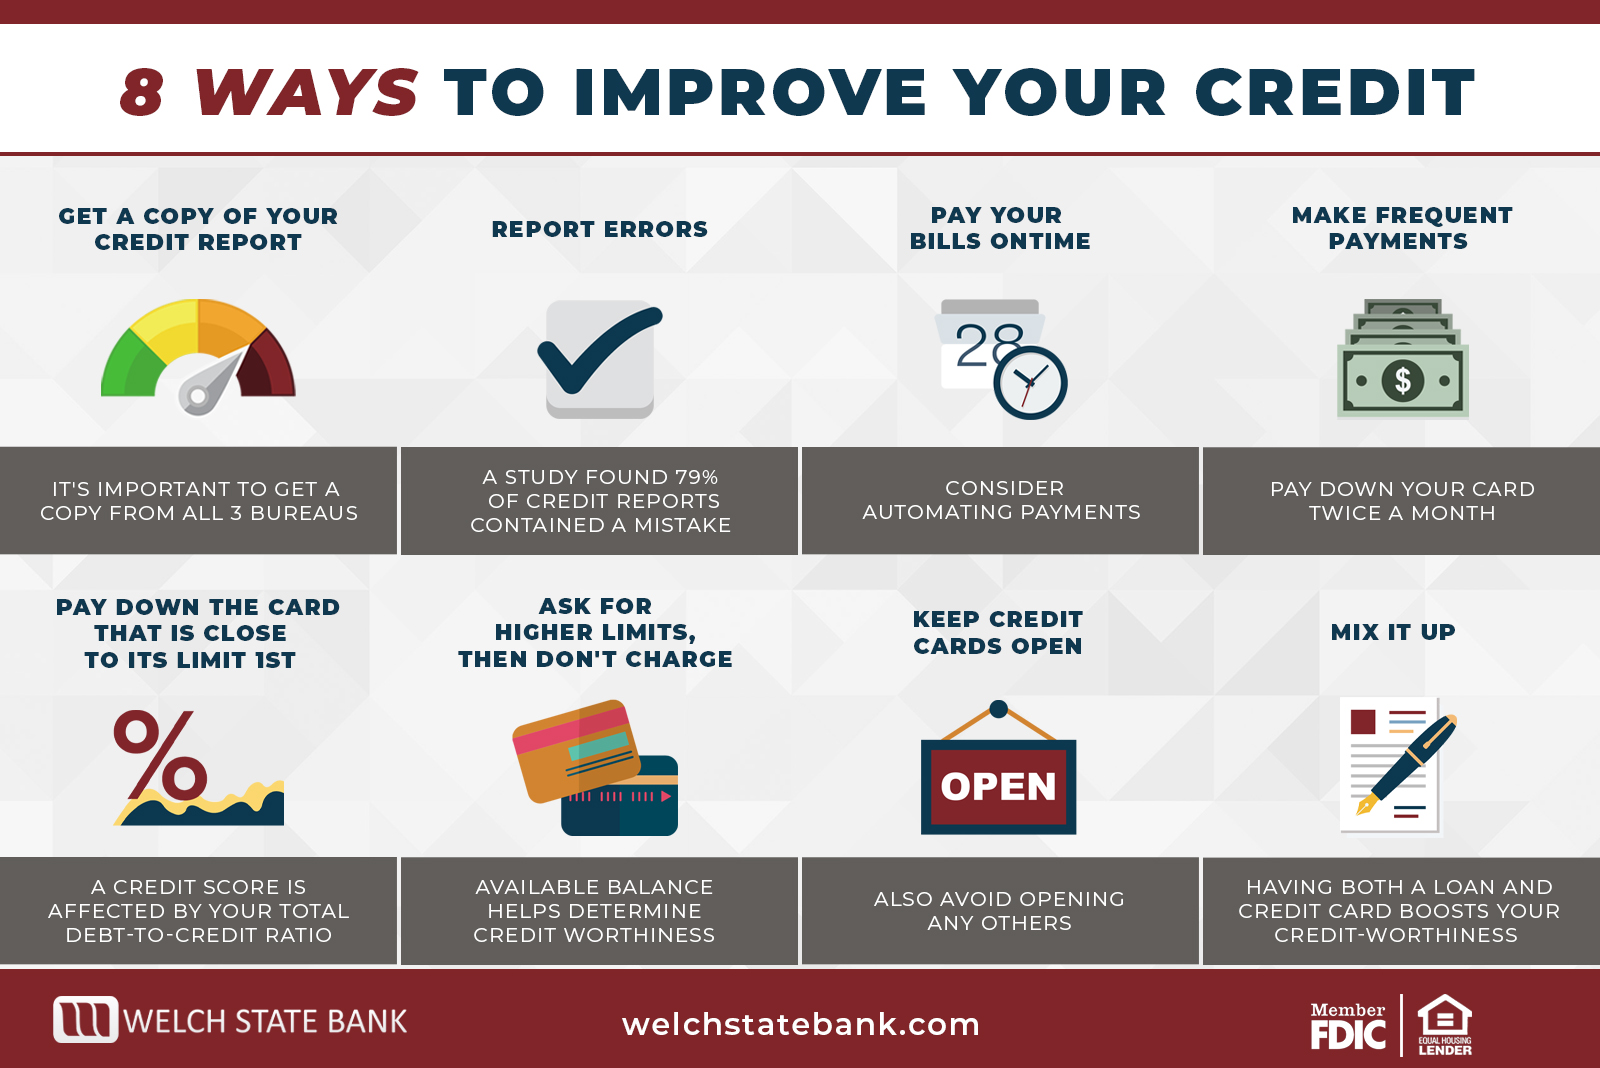
Alright, let's start with the basics. Your credit score is like a plant - it needs water, sunlight, and a little bit of love. In this analogy, water is paying your bills on time. Late payments are like droughts, they wither your score faster than you can say "overdraft fees".
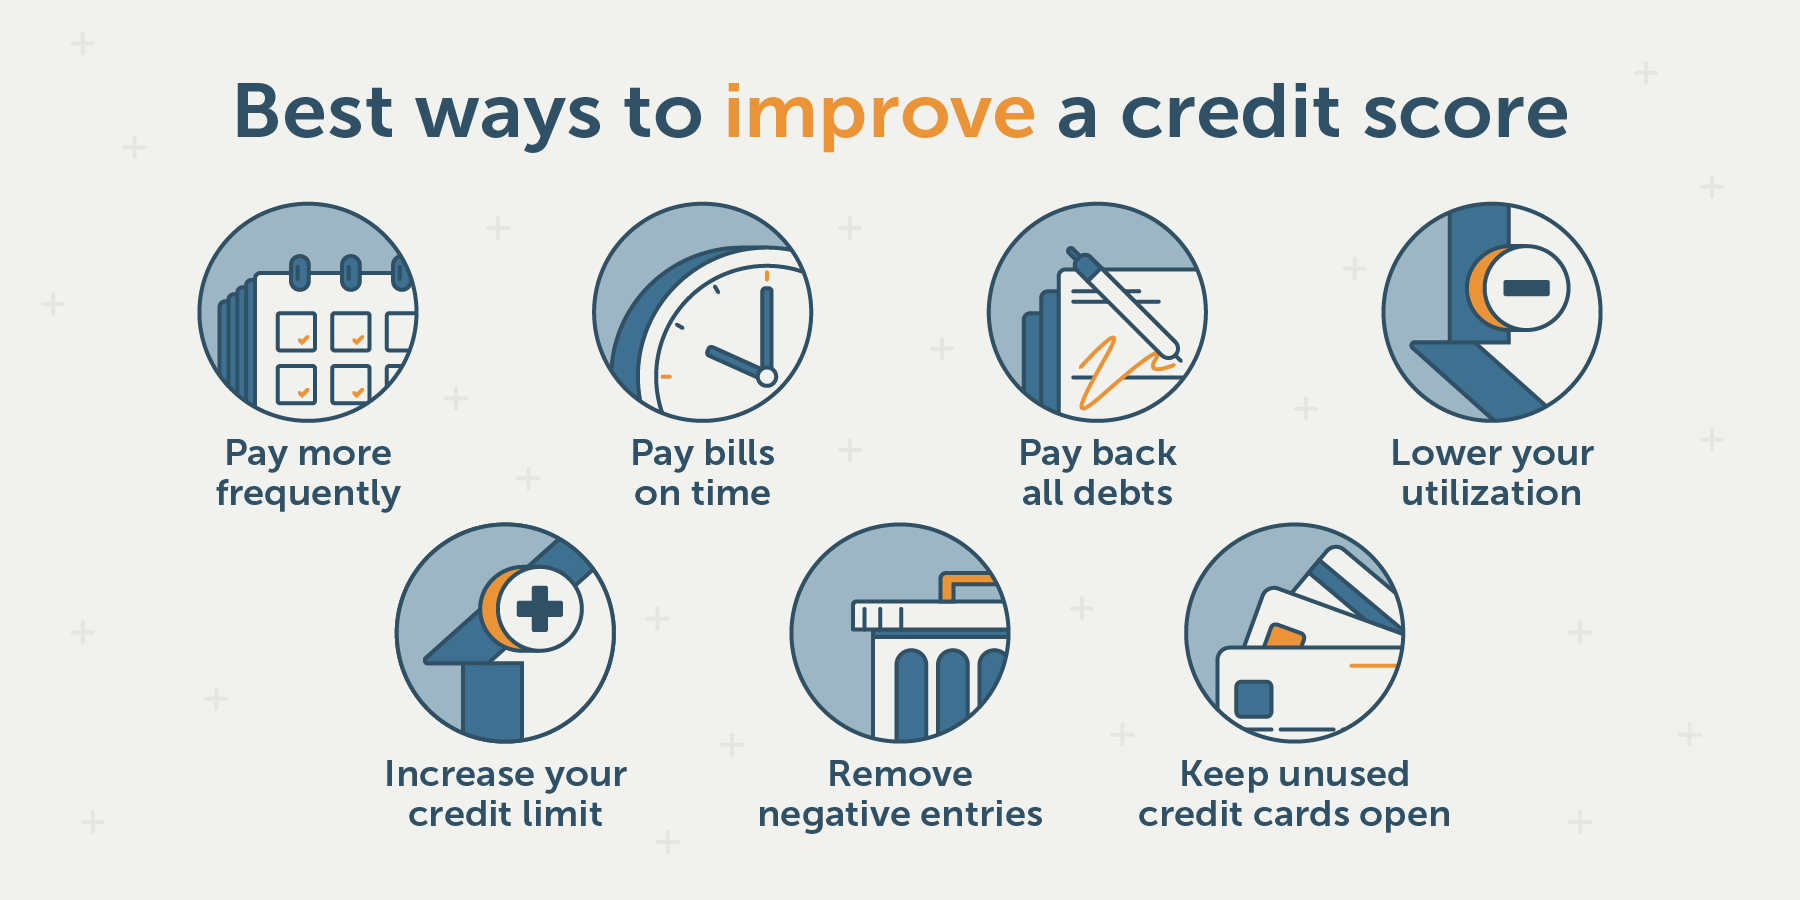
So, set reminders, automate payments, do whatever it takes to keep that cash flowing to the right places. Your future self will thank you (and so will your credit score).
Keep Your Credit Utilization Low, Like Your Calorie Intake on Cheat Day
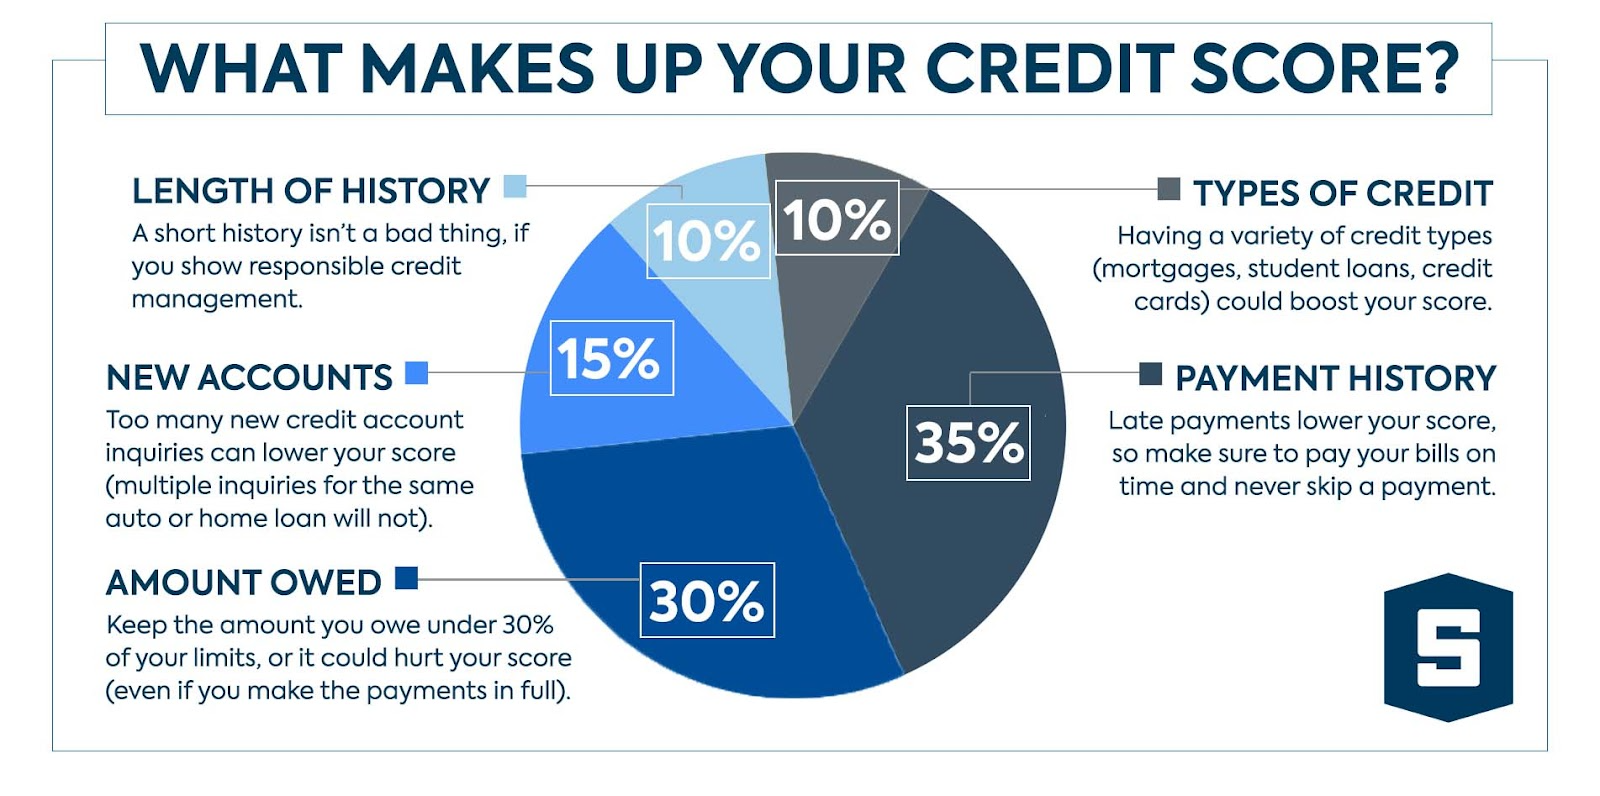
Now, let's talk about credit utilization. This is the fancy term for how much of your available credit you're using. Imagine your credit limit is a giant pizza, and you've eaten half of it. That's 50% utilization. Not great, Bob.
 Z-Guide: The A to Z about Credit Scores
Ideally, you want to keep your utilization below 30%. So, if you've got a $10,000 limit, try not to charge more than $3,000 at a time. It's like dieting, but instead of counting calories, you're counting dollars. Fun, right?
Build Credit History, Like a Time-Traveling Archaeologist
Here's where things get a bit tricky. To have a good credit score, you need a credit history. But to have a credit history, you need to... have a credit history. It's like trying to explain the concept of 'chicken' to someone who's never heard of 'egg'.
If you're new to the credit game, consider getting a secured credit card. It's like a training wheels for adults. You put down a deposit, and that becomes your credit limit. Use it responsibly, pay it off every month, and voila! You're building credit history.
Surprising Fact: Credit Scores Aren't Just About Credit Cards
Did you know that your credit score can be affected by things that don't seem related to credit at all? Like, for instance, your rent. Some landlords report late or missed rent payments to credit bureaus. It's like finding out your mom's been secretly reporting your curfew violations to the principal.
 How to Build Credit
And here's another shocker - some credit scoring models consider utilities in their calculations. Yes, that's right. Your on-time payments (or lack thereof) to your power company could be affecting your score. So, keep those lights on, folks. Not just for ambiance, but for your credit score's sake.
Monitor Your Score, Like a Hawk Monitoring Its Prey
Lastly, keep an eye on your credit score. It's not enough to just check it once a year and call it a day. Things can change quickly, and you want to catch any errors or fraudulent activity as soon as possible.
There are plenty of free tools out there to help you monitor your score. Use them. Your credit score is like a garden - it needs constant tending, weeding, and watering. And yes, I'm still beating that plant analogy to death. But hey, at least it's a fun one, right?
And there you have it, folks. The not-so-secret guide to building your credit score. It's not rocket science, but it does take some effort. So, roll up your sleeves, grab your metaphorical gardening gloves, and let's get growing!
