Do You Pay Capital Gains On A House Sale

Ever wondered what happens to that sweet cash you make when you sell your beloved old home? Does it all go into your pocket, or does Uncle Sam come knocking? Let's dive into t...

Ever wondered what happens to that sweet cash you make when you sell your beloved old home? Does it all go into your pocket, or does Uncle Sam come knocking? Let's dive into the world of capital gains tax, and I promise, it won't be as boring as your high school math class.
What's the Deal with Capital Gains?
Imagine you're at a garage sale. You bought a vintage record player for $50, and now you're selling it for $150. That's a capital gain, my friend! It's the profit you make when you sell something that you've owned and that has increased in value. Now, the IRS wants a piece of that pie, and that's where capital gains tax comes in.
But here's the thing, the IRS isn't interested in your garage sale profits. They're more into the big-ticket items, like your home. So, let's talk about capital gains on house sales.
Must Read
When Do You Pay Capital Gains Tax on a House Sale?
First things first, you're not going to pay capital gains tax every time you sell a house. The IRS gives you a break with something called the primary residence exclusion. If you've lived in your home for two out of the past five years, you can exclude up to $250,000 of your gain from taxes. That's right, up to a quarter of a million dollars!
But what if you're not single? If you're married and file a joint return, the exclusion jumps to $500,000. That's like getting a free pass to a fancy dinner for two! Now, you might be thinking, "That's great, but I've never made $500,000 on a house sale." Well, hold on to your hats, because some people do.
Let's take John and Jane, for example. They bought a little fixer-upper in San Francisco back in the '90s for $200,000. They spent a few years and a small fortune fixing it up, and now they're selling it for $2.5 million. That's a gain of $2.3 million, and even after the $500,000 exclusion, they're still looking at a hefty tax bill.
What About the Tax Rates?
Now, let's talk tax rates. Capital gains are taxed at different rates depending on your income. If you're in the 10% or 12% tax bracket, your capital gains are taxed at 0%. That's right, nothing! But if you're in the 22% bracket or higher, you'll pay 15% on your gains. And if you're in the top bracket, you'll pay 20%.
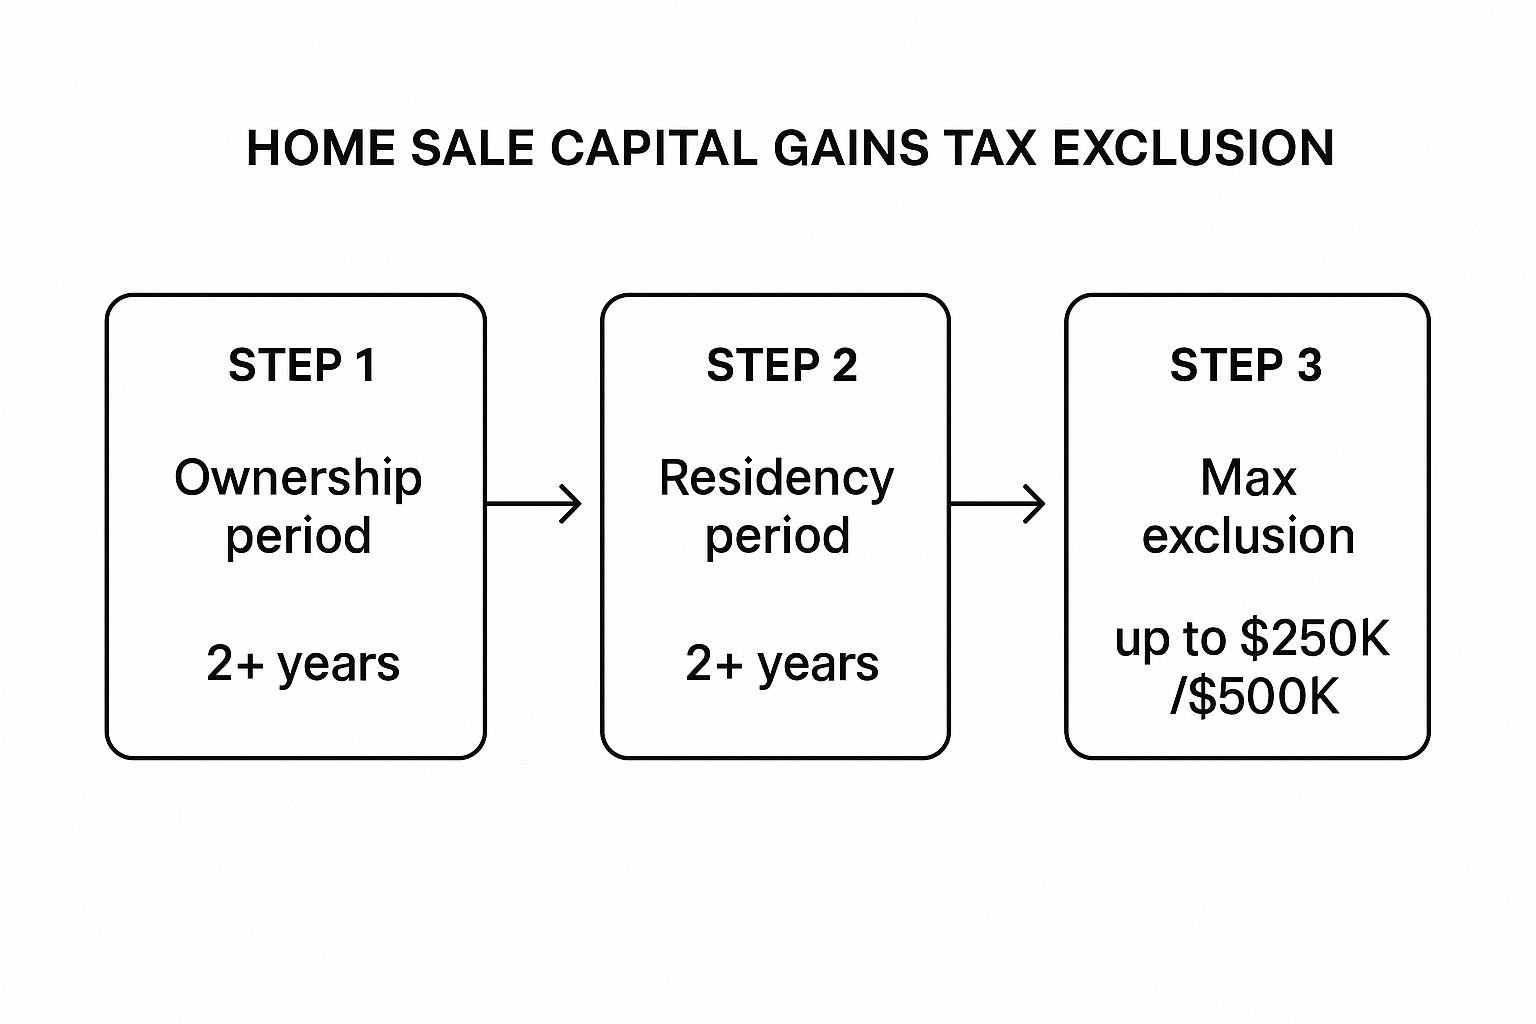 Home Sale Capital Gains Tax: Maximize Your Savings
So, let's go back to John and Jane. They're in the 32% tax bracket, so they'll pay 15% on the $1.8 million that's not excluded. That's a tax bill of $270,000. Ouch!
What If You're Not a Full-Time Resident?
Now, what if you're not a full-time resident? Maybe you're a snowbird, flitting between your home in Florida and your cabin in Minnesota. Well, the IRS still gives you a break, but it's not as generous. You can exclude up to $250,000 if you're single and $500,000 if you're married, but you have to live in the home for at least two years out of the past five.
But here's the kicker. If you sell your home for a gain, you might have to pay a net investment income tax. This is a 3.8% tax on the lesser of your net investment income or the amount by which your modified adjusted gross income exceeds a certain threshold. It's a bit complicated, but it's something to keep in mind.
Why Should You Care?
You might be thinking, "That's all well and good, but I'm never going to sell my house for that much." And you know what? That's okay! But here's why you should still care about capital gains tax.
First, it's important to understand how the tax system works. It's like learning how to drive. You don't need to know how a car engine works to drive a car, but it helps to understand how the pedals and the steering wheel work. The same goes for taxes. The more you understand, the more you can plan and prepare.
 Do You Pay Taxes On Selling A House – GPLMMK
Second, capital gains tax can affect your retirement plans. If you're thinking about selling your home to downsize or move to a retirement community, understanding capital gains tax can help you make the most of your money.
And finally, it's just good to be informed. Knowledge is power, my friends. The more you know about how the world works, the more you can make it work for you.
So, What Should You Do?
If you're thinking about selling your home, it's a good idea to talk to a tax professional. They can help you understand how capital gains tax will affect you and help you plan accordingly. They can also help you understand other taxes, like property taxes and estate taxes.
And if you're not thinking about selling your home, that's okay too! But it's still a good idea to understand capital gains tax. You never know when life might throw you a curveball, and you'll be glad you're prepared.
So, there you have it. Capital gains tax isn't as scary as it sounds. It's just another part of the great big puzzle that is the IRS tax code. And like any puzzle, it's more fun to solve when you have all the pieces.
