Do I Qualify For A Home Loan

So, you've decided to take the plunge and buy a house, huh? Congrats! You're about to join the ranks of the responsible adults who don't have to worry about their landlord sud...

So, you've decided to take the plunge and buy a house, huh? Congrats! You're about to join the ranks of the responsible adults who don't have to worry about their landlord suddenly deciding they want to move in and turn your living room into their personal yoga studio. But before you start picking out paint colors and arguing with your partner about whether the kitchen really needs a second oven (spoiler alert: it doesn't), you've got to figure out if you can even afford this whole homeownership thing.
Enter the home loan, stage left. It's like the fairy godmother of finance, turning your pumpkin of a down payment into a carriage of a dream home. But before you start clicking your heels and saying "there's no place like home," you've got to make sure you're not just some random stranger off the street who wandered into the bank and started making demands. You've got to qualify.
Credit Score: The Fairy Godmother's Magic Wand
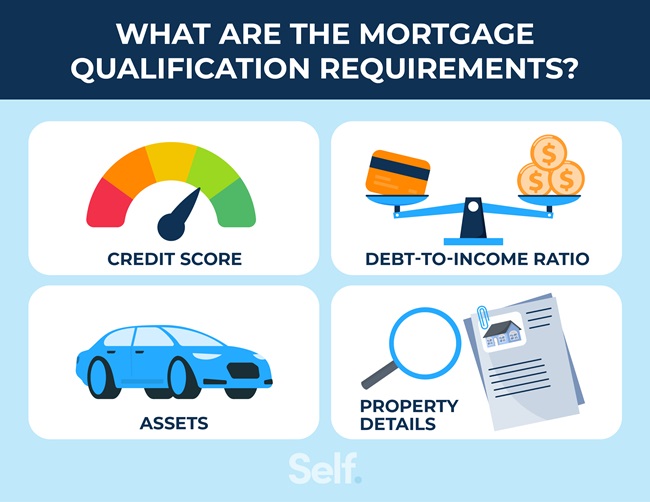
First things first, let's talk about your credit score. This isn't like your GPA in college where a few late-night study sessions with a pizza and a Red Bull could bring your average down a notch. No, no, no. Your credit score is the be-all and end-all of your financial life. It's the difference between getting a home loan with an interest rate that's lower than your great-aunt's blood pressure and one that's higher than the national debt.
Must Read
Now, you might be thinking, "But I've never even had a credit card! How am I supposed to have a credit score?" Well, my friend, it's time to get with the program. Go apply for a credit card, use it to buy a pack of gum, and then pay it off. Rinse and repeat. Before you know it, you'll be well on your way to a credit score that's higher than your future mortgage payment.
Debt-to-Income Ratio: The Goldilocks of Finances
Alright, so you've got a credit score that's higher than your future mortgage payment. Great! Now let's talk about your debt-to-income ratio. This is basically the financial equivalent of Goldilocks trying out different bowls of porridge. You want it to be just right, not too high, not too low, but just right.
Your debt-to-income ratio is the amount of debt you have (think student loans, car payments, credit card debt) divided by your gross monthly income. Lenders like to see a ratio that's around 43% or lower. So, if you make $5,000 a month, your total debt payments shouldn't be more than $2,150. That's like saying, "I can afford to buy this house, but I can't afford to buy the entire neighborhood."
 7 Questions to Ask a Mortgage Lender - Self. Credit Builder.
Down Payment: The Big Kahuna
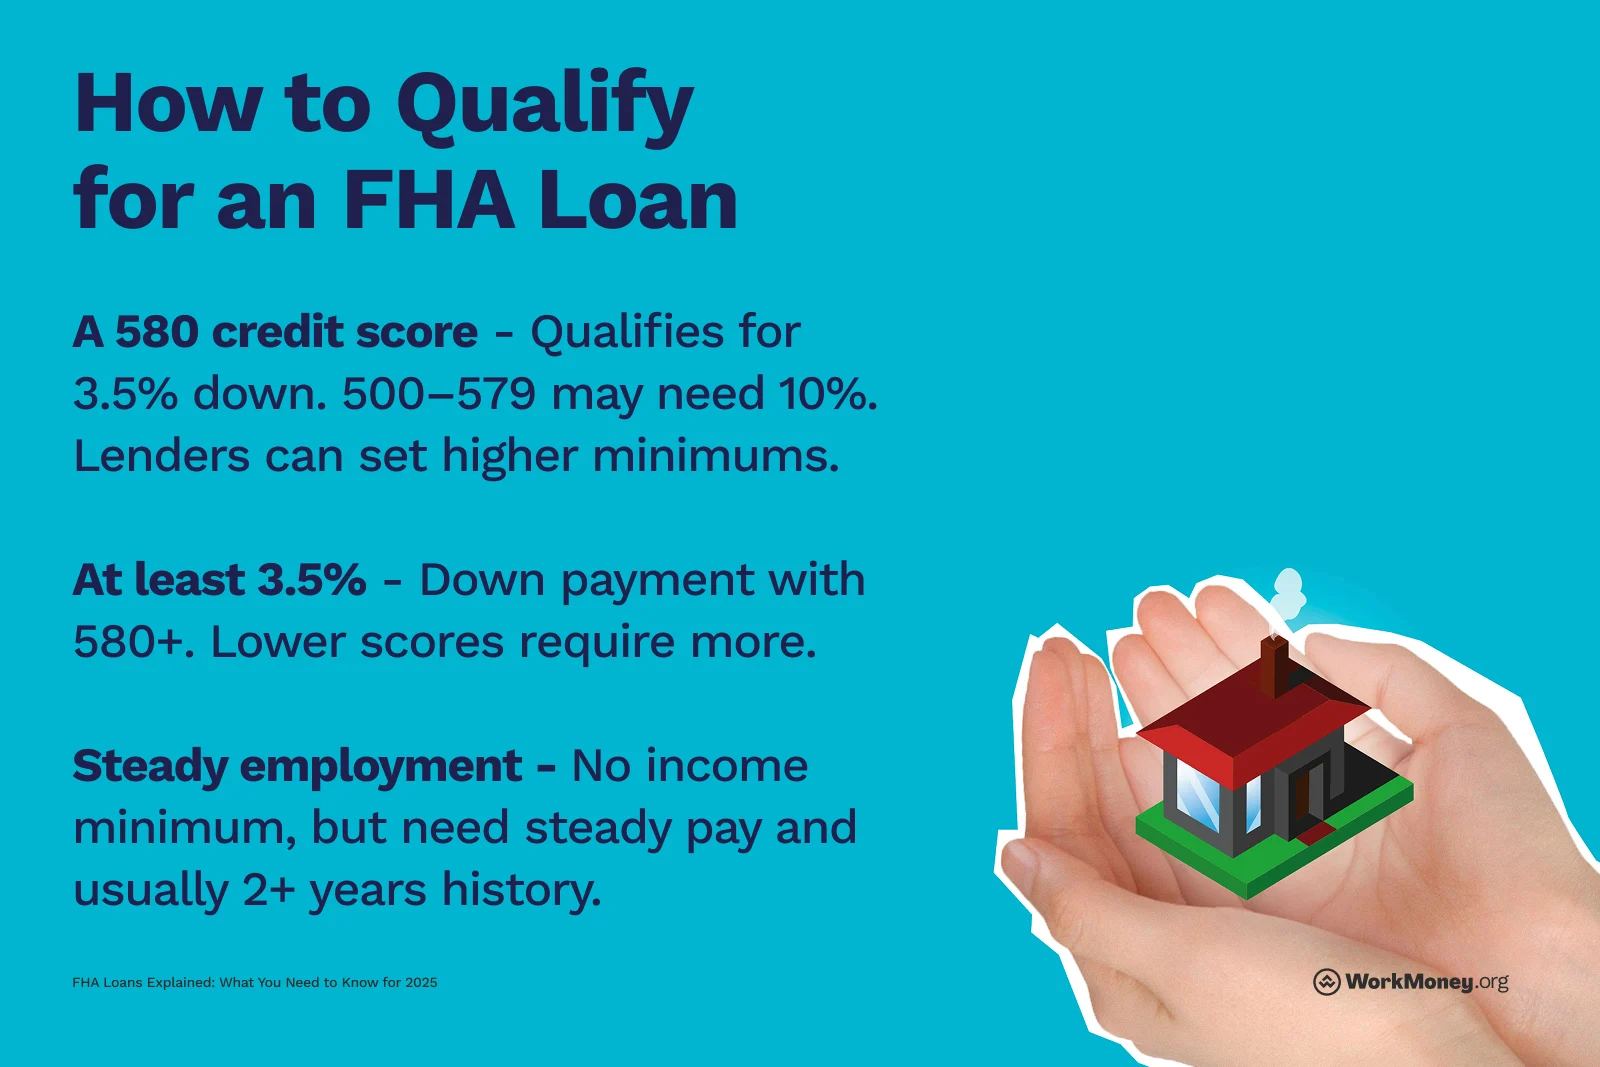
Now, let's talk about the big Kahuna, the elephant in the room, the reason you're even reading this article in the first place: the down payment. You've probably heard that you need to put down 20% of the home's purchase price to avoid private mortgage insurance (PMI). And while that's true, it's not always the be-all and end-all. Some loans, like FHA loans, only require a down payment of 3.5%.
But here's the thing, the more you put down, the less you'll have to borrow, and the less you'll have to pay in interest over the life of the loan. It's like ordering a large pizza when you're only slightly hungry. Sure, you could have gone with the smaller size, but now you've got leftovers for days. And who doesn't love leftover pizza?
Income: The Cash Cow
Speaking of cash, let's talk about your income. Lenders want to make sure you've got a steady stream of it coming in. They want to know that you're not some starving artist who lives off of ramen noodles and hope. They want to see a solid employment history, a consistent income, and a job that's not likely to disappear tomorrow.
 FHA Loans Explained: What You Need to Know for 2025 | WorkMoney
So, if you're a freelancer or self-employed, you might have to work a little harder to prove your income. That means keeping good records, providing tax returns, and maybe even providing a letter from your accountant (yes, you should have one of those). It's like showing up to a job interview with a reference letter from your mom. It's nice, but it's not going to cut it.
Now What?
Alright, so you've checked all the boxes, you've got a credit score that's higher than your future mortgage payment, a debt-to-income ratio that's just right, a down payment that's bigger than your future mortgage payment (see a pattern here?), and an income that's steady as a rock. Congrats! You're officially qualified for a home loan.
But before you start celebrating, let's talk about the fun part: house hunting. Because let me tell you, finding the perfect home is like finding a needle in a haystack. And then, once you've found it, you've got to make an offer, negotiate with the seller, and then hope to god that the home inspection doesn't turn up any surprises (like a family of squirrels living in the walls). But that's a story for another time.
For now, pat yourself on the back. You've taken the first step towards homeownership. You've proven to the bank that you're not just some random stranger off the street. You're a responsible adult who's ready to take on the challenge of a mortgage. And who knows? Maybe one day you'll even be able to turn that mortgage into a second oven. But let's not get ahead of ourselves.
