Do I Need Life Insurance To Get A Mortgage

So, Do You Really Need Life Insurance to Get a Mortgage? Picture this: You're sitting in your real estate agent's office, papers strewn across the table, and you're about to s...
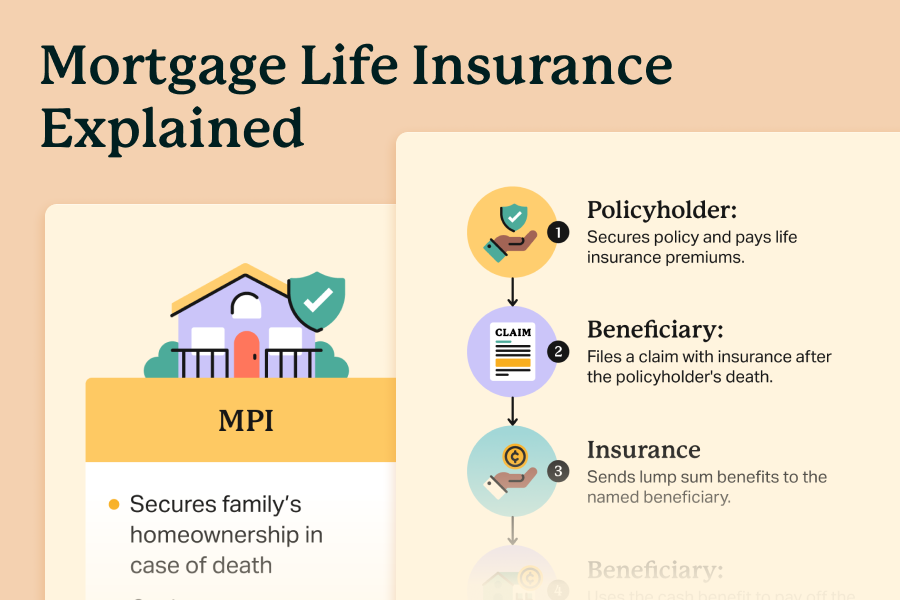
So, Do You Really Need Life Insurance to Get a Mortgage?
Picture this: You're sitting in your real estate agent's office, papers strewn across the table, and you're about to sign on the dotted line for your dream home. Suddenly, the mortgage broker leans in and says, "Oh, by the way, you'll need life insurance." You blink, confused. "I thought I was just buying a house, not planning my funeral," you think. Sound familiar?
Alright, let's rewind a bit. You're here because you're curious about this life insurance thing and mortgages. Great! Let's dive in.
Why the Sudden Interest in Your Mortality?
First things first, why are they asking about life insurance? It's not like they're trying to be morbid (well, not entirely). The thing is, when you take out a mortgage, you're borrowing a large sum of money. Lenders want to protect their investment, and that's where life insurance comes in.
Must Read
Imagine you're the lender. You've loaned someone a fortune, and they're paying you back a little at a time. But what if something happens to them? What if they can't pay back the loan? That's where life insurance can help. If you have it, the lender can be reimbursed if you, well, kick the bucket.
But Do You Really Need It?
Now, here's where it gets interesting. Not all lenders require life insurance. Some may, some may not. It depends on the lender, the type of mortgage, and sometimes, the amount you're borrowing. So, it's not a one-size-fits-all answer.
For instance, if you're taking out a conventional mortgage (the kind most people get), you might not need life insurance. But if you're self-employed or have a high debt-to-income ratio, they might ask for it. And if you're getting a jumbo loan (a mortgage that's more than the conforming loan limit), life insurance is often a requirement.
 Mortgage Life Insurance | Do I Need It?
Now, you might be thinking, "But what if I don't want life insurance?" Well, that's your call. You can refuse, but remember, the lender is taking a risk by lending you money. They might charge you a higher interest rate or ask for a larger down payment to compensate for the risk.
Types of Life Insurance for Mortgages
If you decide to get life insurance, you'll have a few options. The most common are term life insurance and decreasing term life insurance.
Term Life Insurance is like renting life insurance. You pay premiums for a set term (like 10, 20, or 30 years), and if you die during that term, your beneficiaries get a payout. The payout decreases over time, but the premium stays the same.
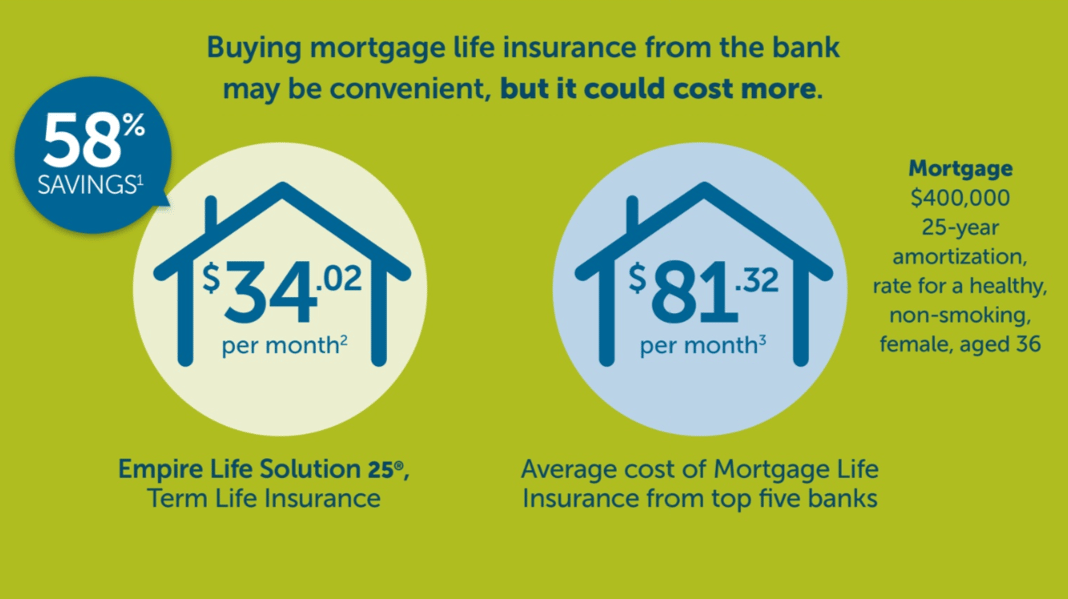 Term Life Insurance Mortgage Protection
Decreasing Term Life Insurance is similar, but the payout decreases each year while the premium stays the same. This type of insurance is often used to cover a mortgage because the amount you owe decreases over time as you pay off your loan.
So, Should You Get Life Insurance?
Only you can answer that. It depends on your financial situation, your risk tolerance, and your peace of mind. If you have dependents or a spouse who relies on your income, it might be a good idea. But if you're single, childless, and not too worried about debt, you might decide it's not worth it.
Here's my advice: Don't make a decision based on fear or panic. Take your time, do your research, and talk to a financial advisor. They can help you understand your options and make an informed decision.
And remember, the world of mortgages and life insurance can be confusing. It's okay to ask questions, to double-check, and to make sure you understand what you're signing. After all, you're not just buying a house, you're making a significant financial commitment. So, take your time, and make sure it's a commitment you're comfortable with.
