Can You Contribute To Tsp After Retirement

So, you've hung up your work boots, kicked back, and said, "That's all, folks!" to your 9-5. Retirement's a blast, right? But hey, ever found yourself wondering, "Can I still...
So, you've hung up your work boots, kicked back, and said, "That's all, folks!" to your 9-5. Retirement's a blast, right? But hey, ever found yourself wondering, "Can I still contribute to my TSP after retirement?" Let's dive in, grab another coffee, and chat about it.
Why Would You Want To?
Well, first off, let's ask ourselves, why would you even consider it? You've earned your rest, after all. But hold your horses, there are a few reasons you might want to keep that TSP train rolling.
Growth, for one. The stock market's a bit like a stubborn mule - it keeps on truckin' even after you've called it a day. So, your TSP could keep growing, even if you're not adding to it.
Must Read
Or maybe you're a snowbird, flitting between your cozy nest and some sunny paradise. You might be thinking, "I've still got some cash flow, why not let it grow in my TSP?" Valid point, my friend. Let's explore.
Can You, Though?
Alright, so can you actually contribute to your TSP after retirement? The short answer? Yes, but...
Here's the thing, once you're retired, you're no longer eligible for the regular contributions. That's the 'but' part. But, and it's a big but (not like a 'whoa, check out that butt' big, more like a 'hold on to your hats' big), you can make catch-up contributions.
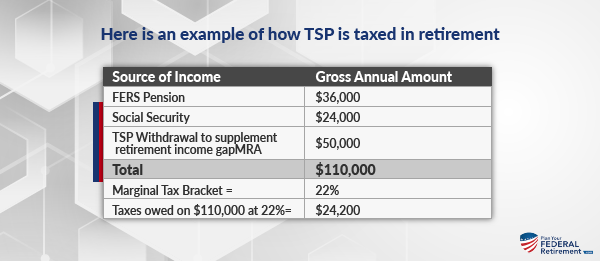 Tsp Withdrawal Options After Retirement – YVCGPD
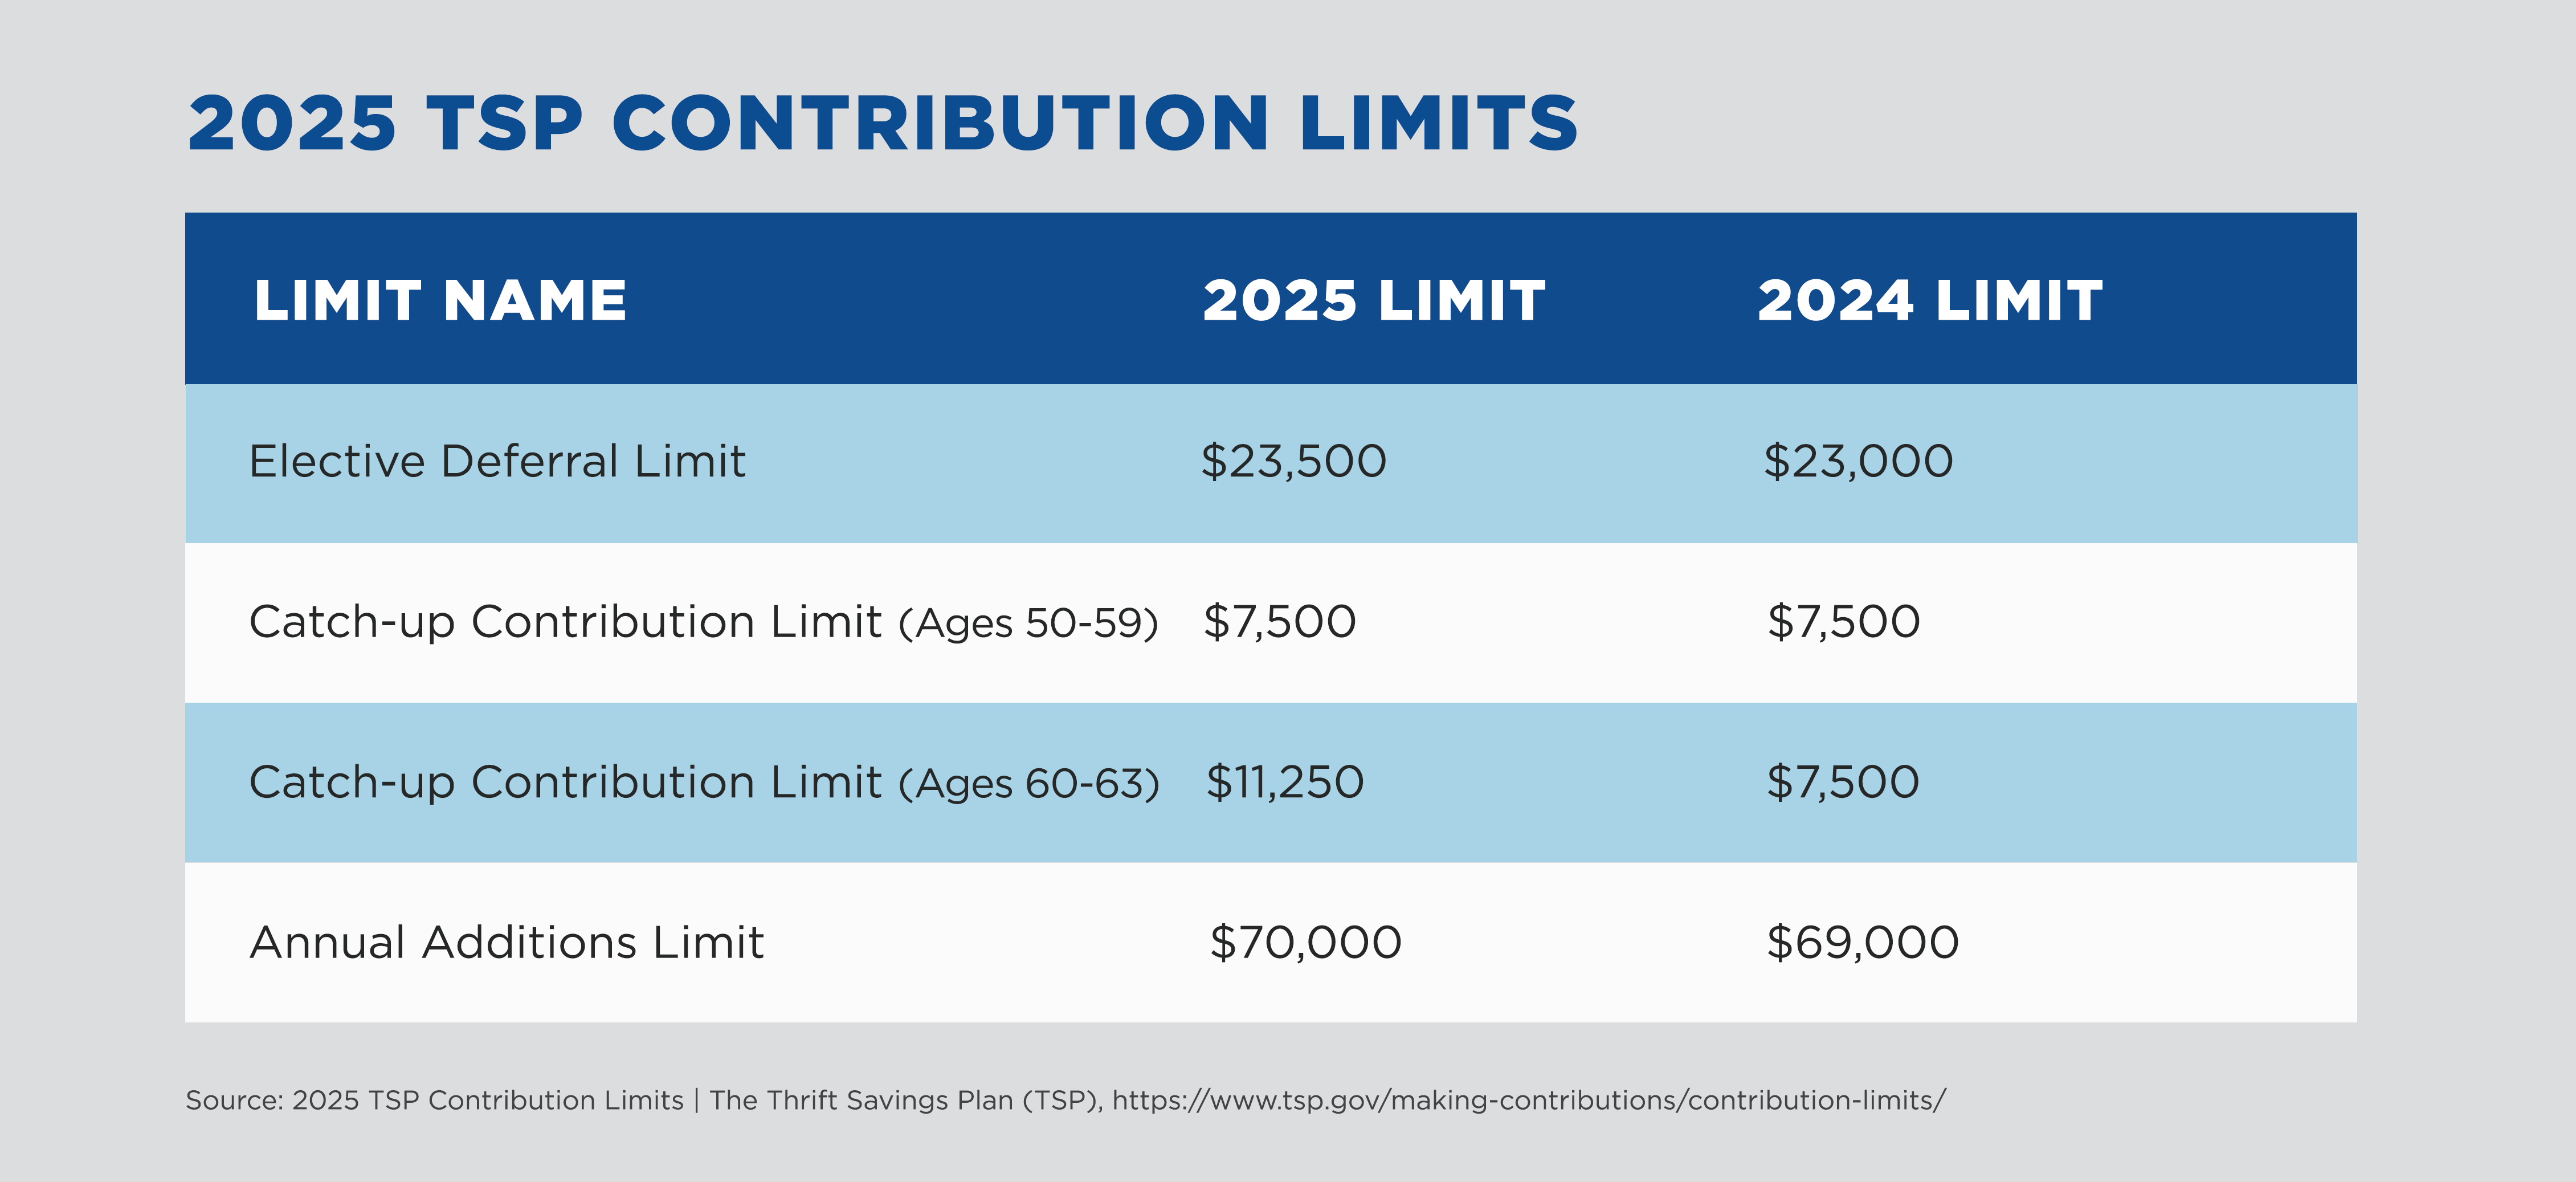
Now, before you go thinking you can just dump a truckload of cash into your TSP, let's talk limits. In 2022, the catch-up limit for TSP is $7,000 on top of the regular contribution limit of $20,500. So, you're looking at a max of $27,500 you can contribute in a year. Not too shabby, huh?
But Wait, There's More!
Now, you might be thinking, "That's all well and good, but what if I've already maxed out my contributions before retiring?" Well, my friend, there's a little something called an IRA - Individual Retirement Account.
You can roll over your TSP into a Traditional IRA or a Roth IRA, depending on your tax situation. Then, you can keep contributing to that bad boy, up to the IRA contribution limits. Just remember, once you've rolled over, you can't roll it back into your TSP.
And hey, if you're feeling really adventurous, you could even consider a lifetime income option. It's like a pension within your TSP. You can start receiving payments as early as age 55 (or 50 if you're a federal employee), and you can't outlive it. Neat, huh?
 Tsp Loan Payment After Retirement at Hunter Hunter blog
So, Should You?
Alright, so can you contribute to your TSP after retirement? Yes. Should you? Well, that's a horse of a different color.
It depends on your financial situation, your goals, and whether you've got a nest egg big enough to keep you comfortable. If you're still working, even part-time, and you've got the cash flow, it might be worth it. But if you're living on a fixed income, you might want to keep that cash for, you know, actually living.
Here's the thing, though. It's your money, your retirement, and your life. So, why not have a chat with a financial advisor? They can give you the lowdown, help you crunch some numbers, and make sure you're making the best decision for you.
And hey, while you're at it, maybe ask them about that time travel thing. I mean, if we're talking about retirement, who knows? Stranger things have happened, right?
