Can I Pay Into A Lisa And An Isa

So, I was chatting with my mate, Jamie, the other day. You know Jamie, right? The one who's always got a side hustle or an investment scheme cooking up. Anyway, he starts tell...
So, I was chatting with my mate, Jamie, the other day. You know Jamie, right? The one who's always got a side hustle or an investment scheme cooking up. Anyway, he starts telling me about these weird acronyms he's been throwing money at - LISAs and ISAs. I mean, who names these things, right? Sounds like a new dance craze or something. But no, turns out they're actually pretty nifty financial tools. Let's dive in, shall we?
First things first, what's a LISA?
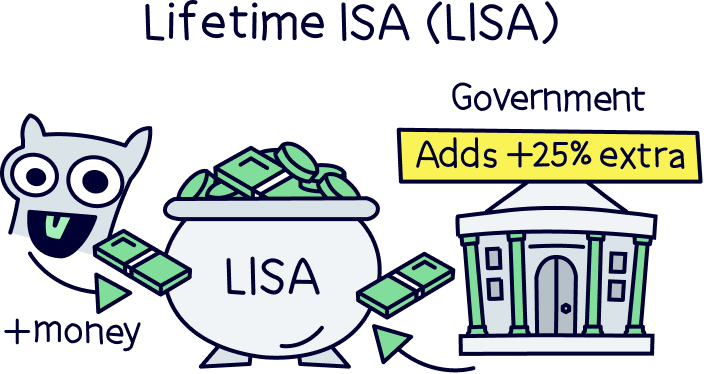
Alright, so LISA stands for Lifetime ISA. It's like a savings account on steroids. You can stick up to £4,000 a year in there, and the government will give you a 25% bonus on that. That's right, free money from the government. But there's a catch - you can only withdraw the money without a penalty if you're buying your first home or you're over 60. Otherwise, you'll pay a 25% charge. Ouch!
Now, you can only open a LISA if you're between 18 and 39. And once you hit 50, you can't pay into it anymore. But you can keep the money in there, growing and growing. It's like a little savings snowball, rolling down the hill of time.
Must Read
And then there's the ISA...
ISAs, on the other hand, are a bit more flexible. They stand for Individual Savings Account. There are different types, but the most common ones are Cash ISAs and Stocks and Shares ISAs. With a Cash ISA, you stick your money in the bank, and it grows a bit each year. It's like a regular savings account, but with a bit more interest.
Stocks and Shares ISAs are a bit more exciting. You're basically investing in the stock market. It's riskier, sure, but if you're in it for the long haul, the potential rewards are much bigger. You can stick up to £20,000 in an ISA each year, and you don't pay any tax on the interest or gains. That's right, no tax. Isn't that nice?
 Lisa Isa Rules at Kristen Loveland blog
So, can you pay into both?
You might be wondering if you can pay into both a LISA and an ISA in the same year. The answer is yes, but there's a catch. You've got an annual allowance of £20,000 for ISAs, and you can pay up to £4,000 into a LISA each year. But remember, the LISA bonus only applies to the first £4,000 you save each year. So, if you're planning on saving more than £4,000, you might want to consider an ISA instead.
But hey, everyone's situation is different. Maybe you're saving for a house, maybe you're saving for retirement, maybe you're just saving for a rainy day. The important thing is to start saving, and these accounts can help you do that. So, what's it gonna be, LISA, ISA, or both? The choice is yours, my friend.

