Can A Civilian Assume A Va Loan

So, you've been eyeing that VA loan, huh? I mean, who can blame you? It's like the cool kid at the lending party. But here's the thing, can you, a civilian, assume one? Let's...
So, you've been eyeing that VA loan, huh? I mean, who can blame you? It's like the cool kid at the lending party. But here's the thing, can you, a civilian, assume one? Let's spill the beans, shall we?
What's a VA Loan, Again?
Alright, let's start at the beginning. VA loans are like the superhero of mortgages, designed by the U.S. Department of Veterans Affairs for, well, veterans, service members, and their families. They're known for their flexible terms, no down payment, and no private mortgage insurance (PMI) requirements. But they're not just handing them out to anyone, okay?
You're Not a Vet, So What Gives?
Now, you might be thinking, "But I see ads everywhere! They're practically begging me to take one!" Well, yes and no. Here's the deal: VA loans are insured by the VA, which means if you default on the loan, the lender isn't left holding the bag. But the VA doesn't lend the money directly. That's where your friendly neighborhood lender comes in.
Must Read
So, those ads you're seeing? They're likely from private lenders who are willing to work with VA loans. But they're not going to just hand one over to anyone who walks in. They've got rules, just like the VA.
Can't I Just Assume One?
Alright, let's talk turkey. You might be wondering if you can just assume a VA loan. You know, like you would a cool nickname or a really great recipe. The answer? It's a little more complicated than that.
Here's the thing: VA loans are tied to the veteran's eligibility. That means the loan is in the veteran's name, and they're the ones responsible for it. Now, if you're buying a home from a veteran who has a VA loan, you might be able to assume the loan. But it's not as simple as just signing some papers and moving in.
 VA Assumable Loan: Making Homebuying More Affordable - AssumeList
Assumable VA Loans: The Fine Print
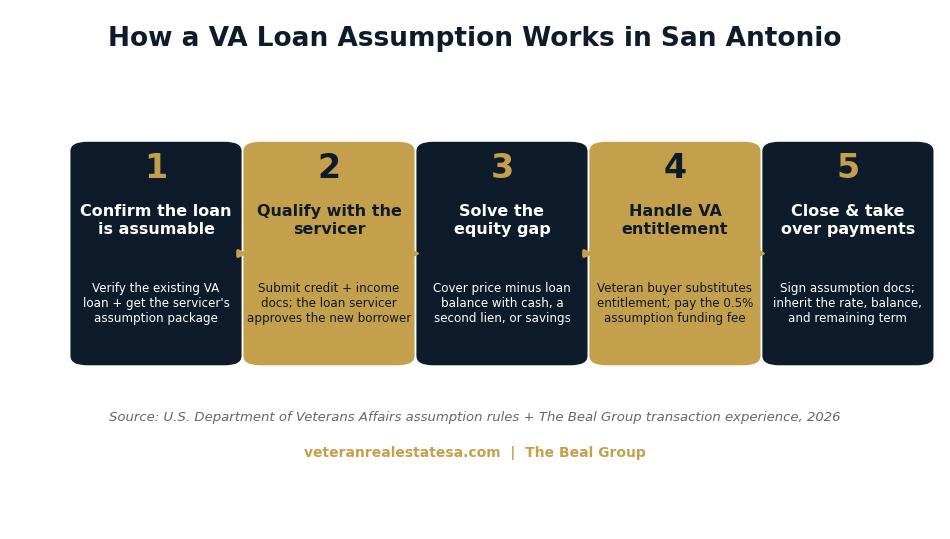
First off, not all VA loans are assumable. It depends on when the loan was originated and the terms of the loan. If the loan is assumable, the veteran has to agree to the assumption, and the lender has to approve it. That's right, the lender gets a say in this too.
Now, here's where it gets interesting. When you assume a VA loan, you're taking on the veteran's interest rate, which might be lower than what you'd get with a new loan. But you're also taking on the remaining term of the loan. So, if the veteran has 20 years left on their 30-year loan, that's what you're signing up for.
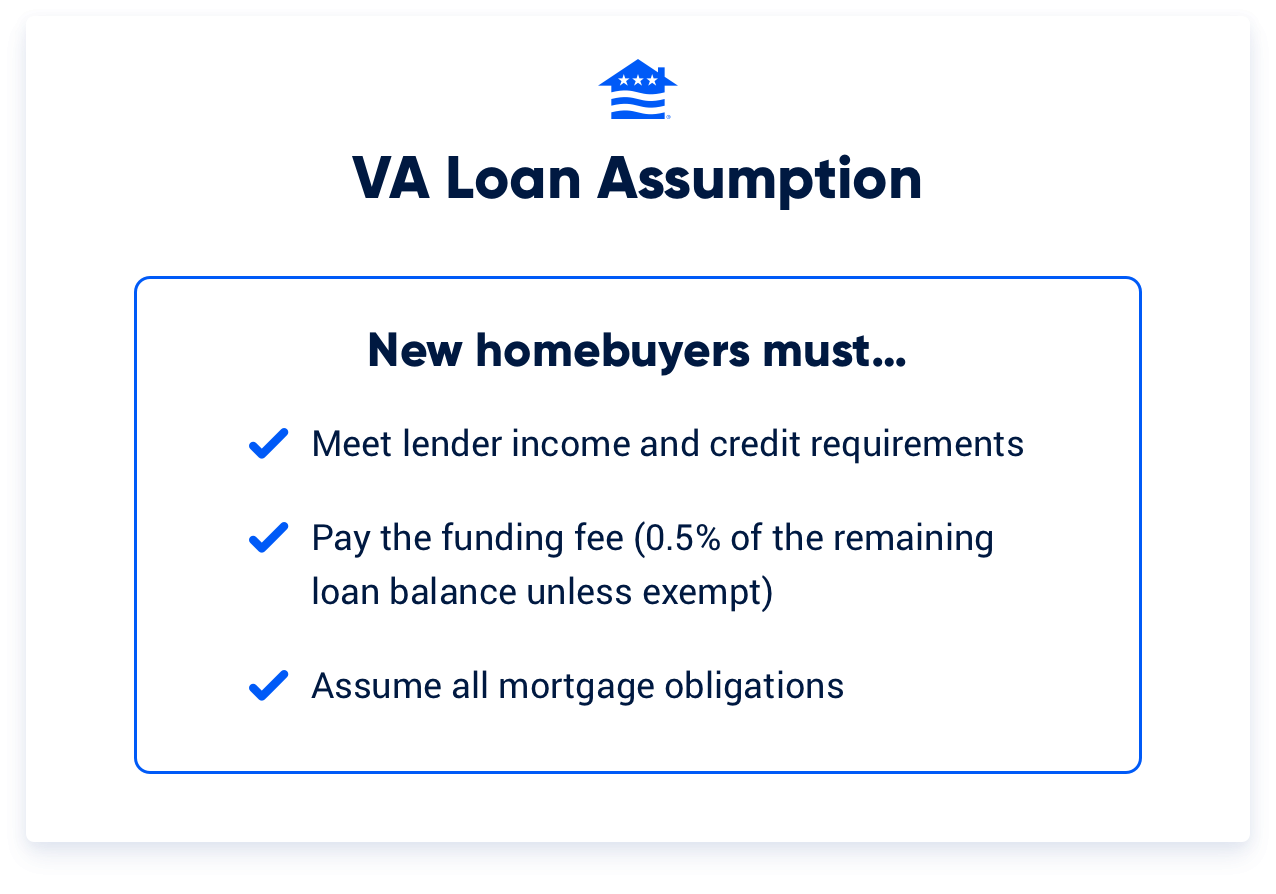
And get this, you might still have to qualify for the loan, even though you're not the one originating it. The lender wants to make sure you can afford the payments, after all. So, you might need to prove your income, credit, and all that fun stuff.
 Assumable VA Loans in San Antonio 2026: A Buyer's Playbook
What If I Can't Assume? What Are My Options?
Alright, so maybe assuming a VA loan isn't in the cards for you. Don't worry, there are other fish in the sea. You could look into other types of loans, like FHA loans or conventional loans. They've got their own perks, you know.
Or, and this is a big 'or', you could wait. Wait for what, you ask? Well, wait until you can qualify for a VA loan. That's right, if you're married to a veteran or the surviving spouse of a veteran, you might be eligible. And if you're an active duty service member or a veteran with a service-connected disability, you might qualify too.
See, I told you it was more complicated than just assuming a cool nickname. But don't worry, there's always a way. You just gotta find the one that works for you.
