What Happens To Pension If You Die

Alright, gather 'round, folks. Today, we're talking about something that's not exactly a barrel of laughs, but it's important nonetheless. We're diving into the world of pensi...
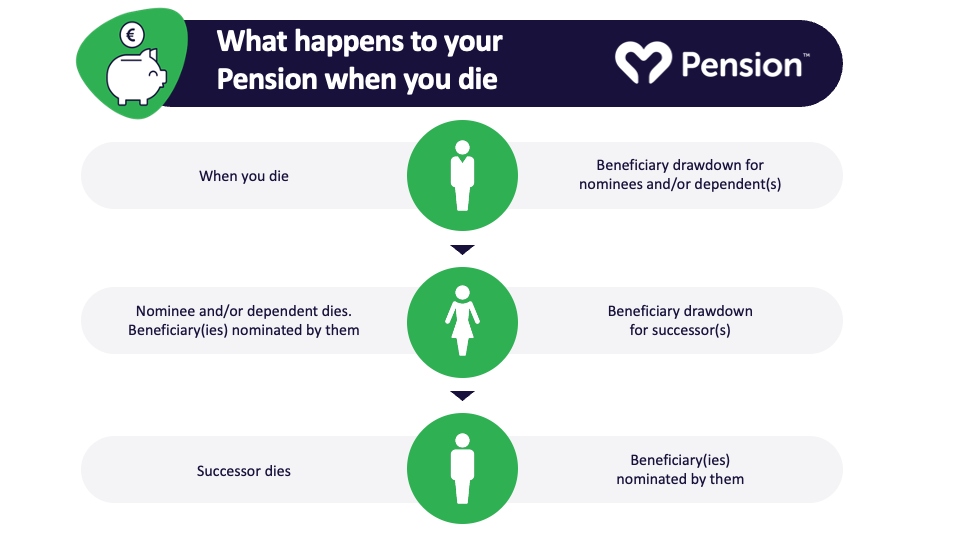
Alright, gather 'round, folks. Today, we're talking about something that's not exactly a barrel of laughs, but it's important nonetheless. We're diving into the world of pensions and what happens to them when you kick the bucket. Don't worry, we'll keep it light and breezy, like a summer's day at the beach. Well, maybe not that breezy, but you get the gist.
So, What's the Deal with Pensions?
Imagine your pension as a big, fat savings account that's been tucked away in the attic of your financial life. You've been chucking money into it for years, and now it's all grown up and ready to support you in your golden years. But what happens if you don't make it to the retirement home? Does your pension just sit there, gathering dust like an old photograph? Not quite.
It's Not All About You, Kiddo
When you set up your pension, you probably had to make some choices about what would happen to it when you're no longer around. Most pensions have a 'beneficiary' option, which is just a fancy word for the person who gets the cash if you shuffle off this mortal coil. This could be your spouse, your kids, your favorite nephew, or even your beloved cat, Mr. Whiskers.
Must Read
Now, if you've chosen someone to inherit your pension, then it's pretty straightforward. When you pop your clogs, the pension provider will usually pay out the cash to your beneficiary. It's like leaving a big, fat inheritance in your will, but without all the drama and family arguments (hopefully).
But What if You Haven't Chosen a Beneficiary?
Alright, so maybe you didn't get around to choosing a beneficiary. Maybe you thought you had all the time in the world, or maybe you just forgot. Don't worry, it happens. In this case, the pension provider will usually have a default option. This could be your spouse, your children, or even your estate. It's like they're saying, "Hey, we know you didn't choose someone, but we've got you covered."
Death Benefits: The Gift That Keeps on Giving
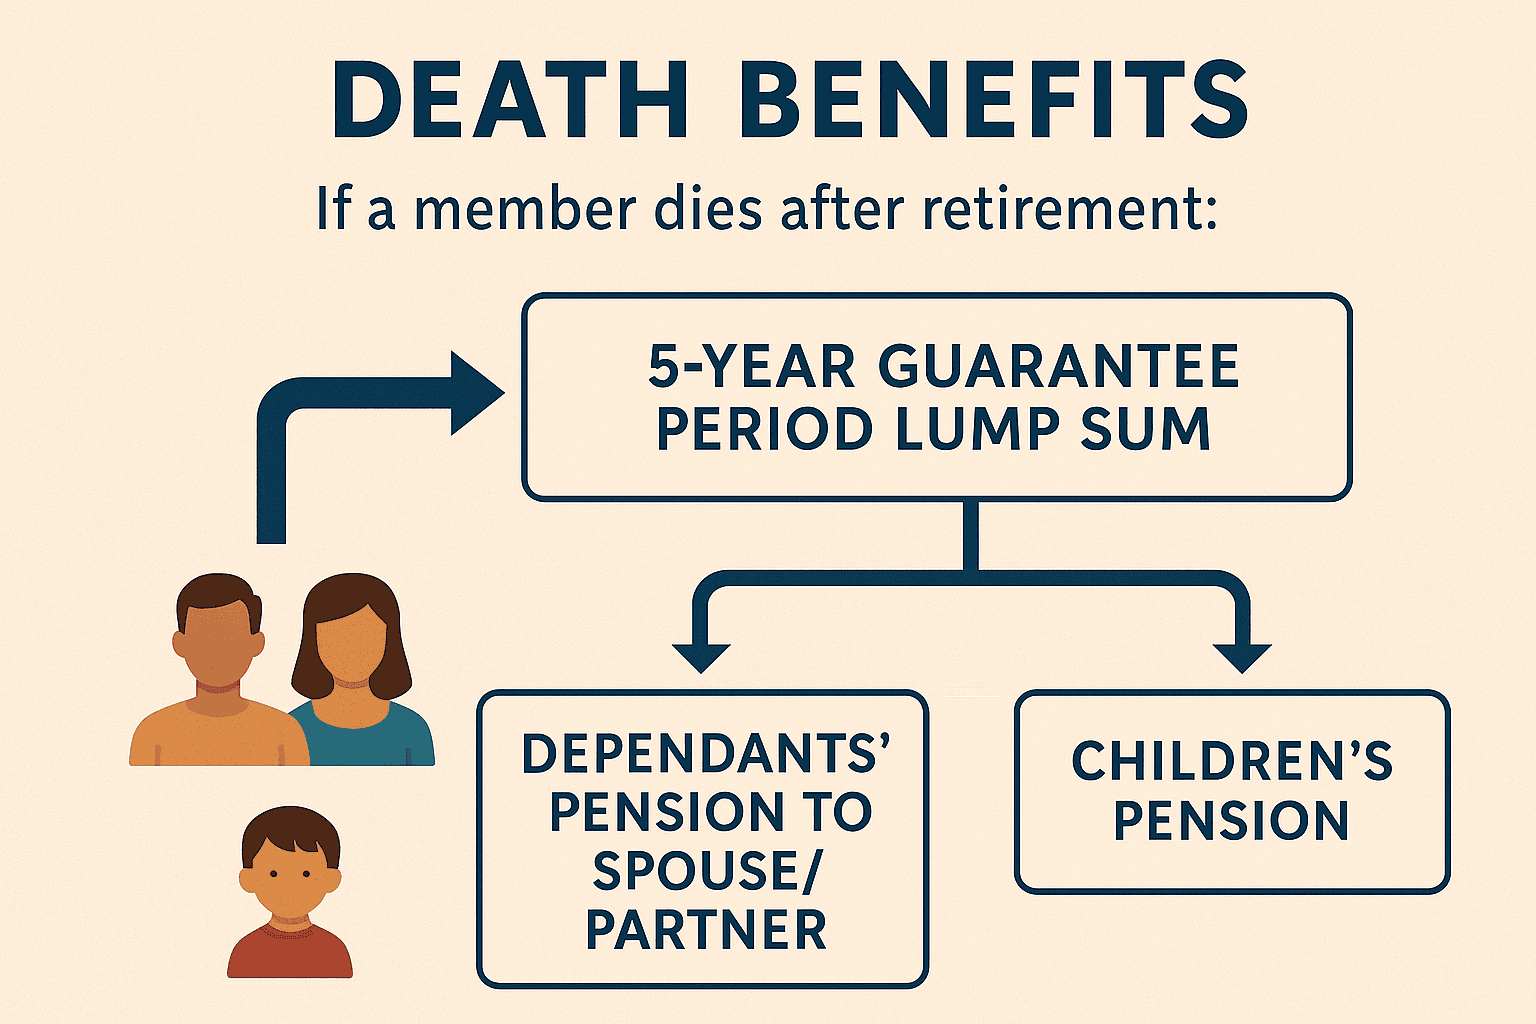
Now, some pensions come with a little something extra called 'death benefits'. These are like the cherry on top of your financial sundae. They can be a lump sum payment, an annuity (that's a regular payment for life), or even a combination of the two. It's like the pension provider is saying, "We're sorry you're gone, but here's some cash to make your loved ones' lives a little easier."
But here's the thing, folks. Death benefits aren't always automatic. Sometimes, you have to choose them when you're setting up your pension. So, if you want to make sure your loved ones are taken care of, you might want to give it some thought. It's like ordering a side of fries with your pension - you might not think you need it, but it sure is nice to have.
Taxes: The Party Pooper
Alright, let's talk about the elephant in the room. Taxes. I know, I know, it's not the most exciting topic, but it's important. When you die, the taxman comes knocking, and he wants his share of your pension. The amount he gets depends on where you live and how your pension is set up. It's like he's saying, "I'm sorry for your loss, but Uncle Sam needs his cut."
Now, some pensions are taxed before they're paid out to your beneficiary. Others are taxed after. It's like the taxman is saying, "I'll take my share now, or I'll take it later. Your choice." Either way, it's important to understand how it all works so you can plan accordingly. Nobody wants to leave their loved ones with a big, fat tax bill.
 NHS Pension Contributions In 2025 : How Much Will I Get?
What About Your Pension Debts?
Now, let's talk about the other side of the coin. What if you've got debts hanging over your head when you kick the bucket? Will your pension have to cover them? The answer is, it depends. If your pension is part of your estate, then yes, it could be used to pay off your debts. But if it's not part of your estate, then it might be safe from the debt collectors.
It's like your pension is a big, fat piggy bank, and your debts are the greedy kids trying to break into it. If the piggy bank is part of the house (your estate), then the kids can get to it. But if it's hidden in the treehouse (not part of your estate), then it's safe from their little hands.
So, What Should You Do?
Alright, folks, we've covered a lot of ground here. We've talked about beneficiaries, death benefits, taxes, and debts. It's enough to make your head spin, I know. But here's the thing - it's all important. Your pension is a big part of your financial life, and it's important to know what happens to it when you're gone.
So, what should you do? Well, first off, you should choose a beneficiary. It's like choosing who gets your favorite chair when you're gone. You want to make sure it goes to someone who'll appreciate it, right? Next, you should think about death benefits. They might not be something you want to think about, but they can make a big difference to your loved ones.
And finally, you should talk to a financial advisor. They can help you understand the ins and outs of your pension and what happens to it when you're gone. It's like having a financial GPS - they can help you navigate the complex world of pensions and make sure you're on the right track.
So, there you have it, folks. We've talked about pensions, death, taxes, and everything in between. It's not the most cheerful topic, I know, but it's an important one. So, do yourself a favor and give it some thought. Your future self (and your loved ones) will thank you.
