How Much Could We Borrow On A Mortgage

Ever wondered how much you could borrow for a mortgage? It's like asking, "How many pizzas can I order without breaking the bank?" Let's dive in, keep it real, and explore thi...

Ever wondered how much you could borrow for a mortgage? It's like asking, "How many pizzas can I order without breaking the bank?" Let's dive in, keep it real, and explore this fascinating topic together.
First Things First: What's a Mortgage?
Alright, let's start with the basics. A mortgage is like a big, long-term loan from a bank to buy a house. You promise to pay them back, with interest, over a set period, usually 15 to 30 years. It's like having a really patient friend who lets you pay them back a little at a time.
So, How Much Can You Borrow?
Now, the big question. How much you can borrow depends on a few things, like your income, debts, and credit score. It's like a magical recipe where you're the main ingredient. Lenders use something called a debt-to-income ratio to figure this out. It's just a fancy way of saying, "How much of your income goes towards paying off debts?"
Must Read
Here's a simple breakdown: Lenders usually want your total debts, including your new mortgage, to be no more than 43% of your gross monthly income. So, if you make $5,000 a month, you could potentially borrow up to $2,150 a month for your mortgage. That's like having a pizza budget of $2,150 every month! Well, not quite, but you get the idea.
But Wait, There's More!
Another factor is the loan-to-value ratio. This is like the bank saying, "We'll lend you this much, but only if the house is worth this much or more." Typically, lenders want the loan amount to be no more than 80% of the home's value. So, if you find a house worth $300,000, you could potentially borrow up to $240,000.
And hey, don't forget about interest rates. They're like the extra toppings on your pizza - they add to the cost. The lower the rate, the less you pay over time. So, it's worth shopping around for the best deal.
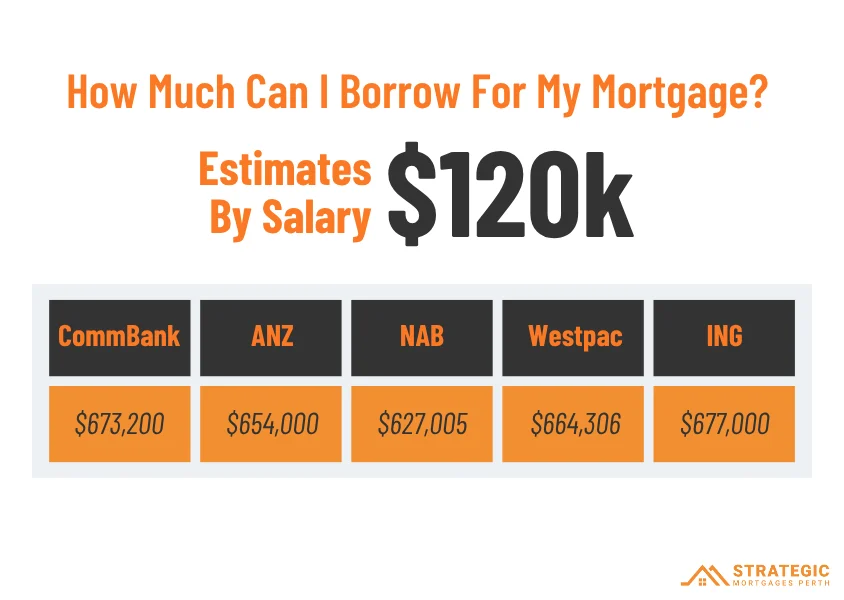 How Much Can I Borrow for My Mortgage at My Salary?
Let's Talk About Down Payments
You might be thinking, "That's all well and good, but I don't have that much cash lying around." That's where down payments come in. It's like putting down a deposit on your pizza to show you're serious about buying it. A bigger down payment means you borrow less, so you pay less in interest over time. Aim for at least 20% if you can. It's like getting extra cheese for free!
So, What's the Magic Number?
There's no one-size-fits-all answer. It depends on your unique financial situation. But here's a fun fact: According to the Federal Housing Finance Agency, the average mortgage loan amount in the U.S. was around $312,500 in the second quarter of 2021. That's like the average pizza order being a large pepperoni!
Remember, it's all about finding what works for you. It's like ordering a pizza - you want to make sure it's something you can afford and enjoy. So, do your research, talk to lenders, and most importantly, have fun with the process. After all, you're on your way to becoming a homeowner!
