How Does Interest Work On A Credit Card

Alright, buddy, let's dive into this credit card interest thing, yeah? Don't worry, I promise it's not as boring as it sounds. We'll keep it real, and I'll throw in some laugh...

Alright, buddy, let's dive into this credit card interest thing, yeah? Don't worry, I promise it's not as boring as it sounds. We'll keep it real, and I'll throw in some laughs, 'cause who wants to read a dry textbook, right?
First things first: What's this interest fella?
Imagine you're at a restaurant, and you order a fancy dish. The waiter says, "It's $20, but if you can't pay now, it's $22 tomorrow." That extra $2 is interest, my friend. It's the price you pay for not paying right away. In the credit card world, it's like that, but instead of a fancy dish, it's your balance.
Simple Interest: The OG
Let's start with the basics. Simple interest is like your old friend who always pays back what they borrow. It's calculated on the original amount (your balance), and it's pretty straightforward. If your interest rate is 15% and you have a $1,000 balance, you'll pay $150 in interest each year.
Must Read
Compound Interest: The Party Crasher
Now, compound interest is like that uninvited guest who shows up and starts adding to the mess. It's calculated on the current balance, including the previous interest. So, if you have a $1,000 balance with a 15% annual interest rate, you'll pay $150 the first year, $172.50 the second year, and so on. It's like a snowball rolling downhill, picking up more snow as it goes.
Scary, right? But don't worry, we'll get to how to avoid this party crasher in a bit.
How do they calculate this stuff?
Credit card companies use something called the daily balance method to calculate interest. It's like they're keeping track of your balance every single day. At the end of each billing cycle, they take the average daily balance, multiply it by the daily interest rate (which is your annual interest rate divided by 365), and then multiply that by the number of days in the billing cycle. Phew!
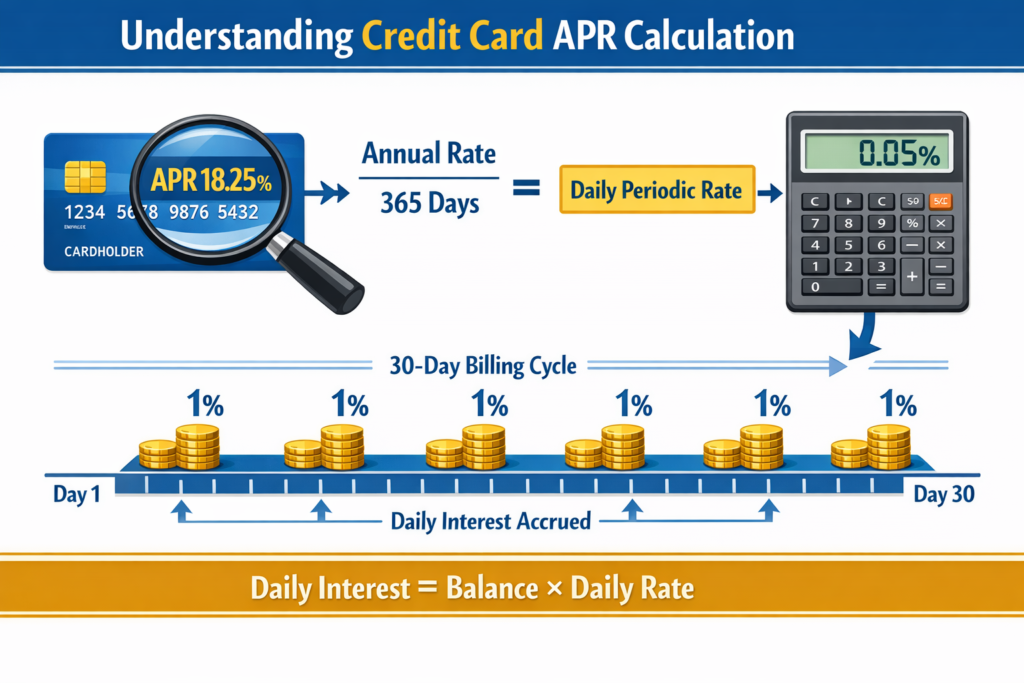 Credit Card APR Explained: How Interest Really Works 2026 - The Rich
But how do I avoid this interest beast?
Easy peasy, lemon squeezy! All you gotta do is pay off your balance in full every month. That's right, no interest charges for you! If you can't pay it all off, at least pay more than the minimum. The more you pay, the less interest you'll owe. It's like giving the interest monster a tiny snack instead of a big feast.
What's this annual percentage rate (APR) thingy?
The APR is like the interest monster's strength level. It's the yearly interest rate they'll charge you. You'll see it on your credit card statement, and it's usually around 15% to 25%. The higher the APR, the more interest you'll pay if you don't pay off your balance.
So, what's the moral of the story?
Interest is like a sneaky little gremlin that loves to hide in your credit card balance. But you don't have to feed it! Pay off your balance in full, and that gremlin will starve. And hey, if you can't pay it all off, at least give it a small snack. Your future self will thank you!
And there you have it, folks! We've tackled the credit card interest beast, and we're all still smiling. Now go forth and use your newfound knowledge wisely. And remember, if you ever feel lost, just think of that fancy restaurant dish and the extra $2. You got this!
