Formula Of Coefficient Of Determination

So, there I was, standing in front of a whiteboard, staring at a bunch of equations that looked like they were written in some ancient language. My friend, let's call him 'Sta...

So, there I was, standing in front of a whiteboard, staring at a bunch of equations that looked like they were written in some ancient language. My friend, let's call him 'Stat', was trying to explain something called the 'coefficient of determination'. I must have looked like a deer in headlights because he laughed and said, "Don't worry, it's not as scary as it sounds." And you know what? He was right. Once I got the hang of it, it was actually pretty useful. Let me tell you all about it.
What's the Big Deal with R²?
Alright, so let's start with the basics. The coefficient of determination, or R², is a statistical measure that represents the proportion of the variance for a dependent variable that's explained by an independent variable or variables in a regression model. In other words, it's a way to measure how well your model fits the data. Sounds fancy, right? But don't worry, we'll keep it real.
Imagine you're trying to predict someone's salary based on their years of education. You'd expect that more education usually means a higher salary, right? But how much of the variation in salaries can you actually explain with just education? That's where R² comes in.
Must Read
Understanding the Scale
R² values range from 0 to 1, or 0% to 100%. A value of 0 means your model explains none of the variation in the dependent variable. A value of 1 means your model explains all of it. Now, you might be thinking, "Wow, I want a 1!" But hold on, it's not that simple.
In reality, you'll rarely, if ever, see an R² of 1. That's because there are always other factors at play that your model can't account for. Think about our salary example. Even if you know someone's education level, you can't predict their salary perfectly because there are other factors involved, like their job, their skills, the economy, and so on.
Interpreting R²
So, how do you interpret R²? Well, it depends on your field and your context. In some fields, an R² of 0.5 might be considered excellent. In others, it might be seen as barely adequate. The important thing is to compare your R² to what's typically seen in your field. You can usually find this information in research papers or by asking other professionals.
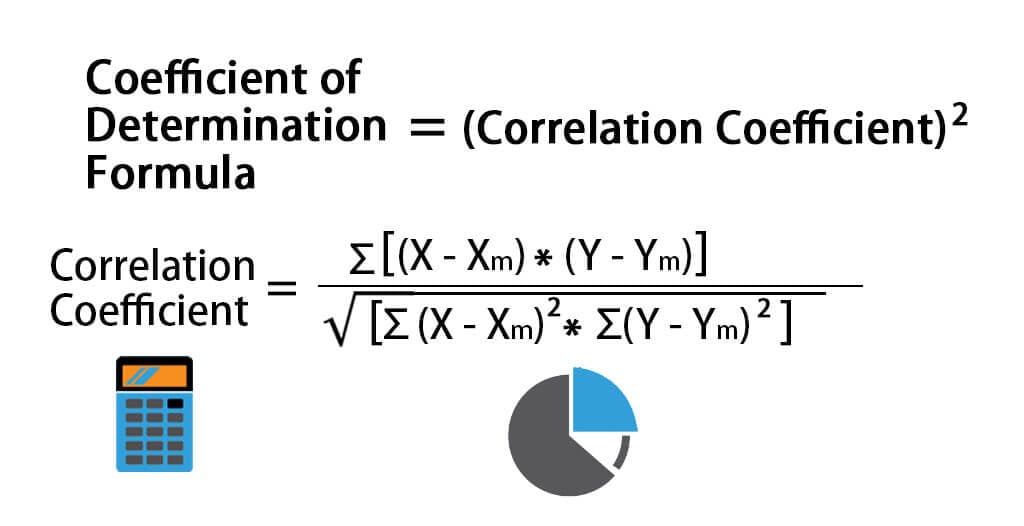 Frm Coefficient Of Determination Rsquared Youtube
Here's a little tip: R² is sensitive to the number of predictors in your model. The more predictors you add, the higher your R² will be, even if those predictors don't actually improve your model's fit. So, it's important to use other metrics, like adjusted R² or Akaike information criterion (AIC), to get a more complete picture.
But What About Negative R²?
Yes, you read that right. It's possible to get a negative R². This happens when the mean of the observed values is a better predictor than the model. In other words, your model is actually worse than just predicting the average value. If you ever see a negative R², it's a sign that something's seriously wrong with your model. It's time to go back to the drawing board.
So, Should You Use R²?
R² can be a useful tool, but it's not the be-all and end-all. It's just one piece of the puzzle. It's important to use it alongside other metrics and to interpret it in the context of your specific field and model. And remember, the goal of any model is to make predictions, not to maximize R².
Now, don't you feel a little bit smarter? I know I did after Stat explained it all to me. And hey, if you ever find yourself staring at a whiteboard full of equations, just remember: it's not as scary as it sounds. You've got this!
