Can You Get A Mortgage While On Benefits

Benefits & Mortgages: Can They Coexist? Ever wondered if you can snag a mortgage while living on benefits? You're not alone. With the cost of living skyrocketing, it's a...
Benefits & Mortgages: Can They Coexist?
Ever wondered if you can snag a mortgage while living on benefits? You're not alone. With the cost of living skyrocketing, it's a question on many minds. Let's dive in, shall we?
First Things First: What Are Benefits?
Benefits, or welfare as it's often called, is financial support from the government for those in need. It could be due to unemployment, disability, or caring for someone. Think of it as a helping hand when life throws a curveball.
So, Can You Get a Mortgage on Benefits?
In short, yes, it's possible. But it's not a one-size-fits-all situation. It depends on various factors, like the type of benefit you're receiving and your personal circumstances.
Must Read
For instance, if you're on Universal Credit, you might be able to get a mortgage. However, you'll need to prove you can afford the repayments. This is where it gets tricky. Lenders look at your income, outgoings, and credit history. If you're on benefits, your income might not be high enough, or your credit score might not be great.
But Wait, There's More: Shared Ownership & Help to Buy
Don't lose hope just yet. There are schemes like Shared Ownership and Help to Buy that can make homeownership a reality. Shared Ownership lets you buy a share of a home (between 25% and 75%) and pay rent on the rest. Help to Buy, on the other hand, is an equity loan where the government lends you up to 20% of the cost of a newly built home, so you only need a 5% cash deposit and a 75% mortgage.
Fun fact: The average age of a first-time buyer in the UK is now 33. That's 10 years older than it was in the 1960s. So, you're not alone if you're thinking about buying a home later in life.
Let's Talk Credit: Building & Improving Yours
If your credit score is holding you back, don't panic. You can improve it. Here are some tips:
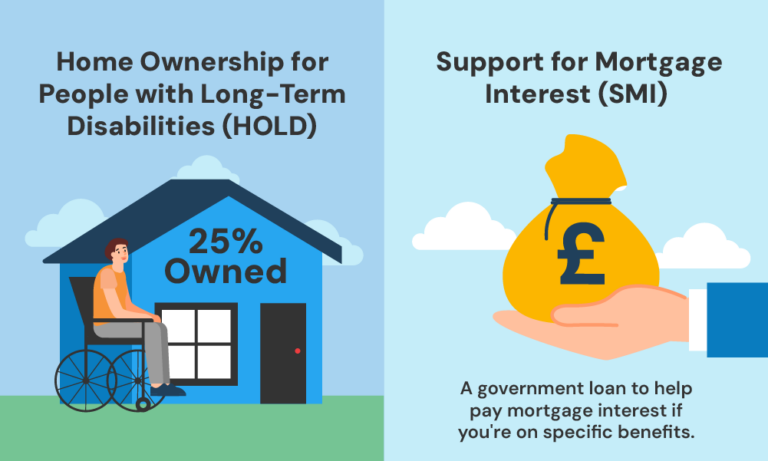 Getting Mortgages For Disabled On Benefits In The UK
- Pay your bills on time. This includes council tax, utilities, and any existing credit agreements.
- Keep your credit utilization low. This means using only a small portion of your available credit each month.
- Register to vote. It might seem odd, but lenders like to see that you're on the electoral roll.
Pro tip: Check your credit report regularly. You can do this for free with services like ClearScore or Experian. It's like checking your bank balance - you need to know where you stand.
Mortgage Advisors: Your Secret Weapon
Don't navigate this alone. Mortgage advisors are your friends. They know the ins and outs of mortgages and can guide you through the process. They can also help you find the best deal for your circumstances. And the best part? They're usually free to use.
Reflection: It's a Marathon, Not a Sprint
Buying a home is a big deal. It's not something that happens overnight. It takes time, planning, and patience. So, if you're on benefits and dreaming of homeownership, don't be disheartened. It might take longer than you thought, but it's not impossible.
Think of it like training for a marathon. You don't start by running 26 miles. You start with small steps, build your stamina, and gradually work your way up. The same goes for buying a home. Start small, build your financial fitness, and before you know it, you'll be crossing that finish line.
