Uk Basic Rate Income Tax

So, there I was, sitting at my kitchen table, coffee in hand, staring at my payslip like it was written in ancient Greek. I mean, I've seen the words 'Basic Rate Income Tax' b...

So, there I was, sitting at my kitchen table, coffee in hand, staring at my payslip like it was written in ancient Greek. I mean, I've seen the words 'Basic Rate Income Tax' before, but today, it was like they were glowing. I thought to myself, "Self, it's high time you understood what this tax lark is all about." And so, dear reader, I'm going to share my little journey of discovery with you.
What's the Deal with Basic Rate Income Tax?
Alright, let's start at the beginning. You know how you earn money, right? Well, our good old friend HMRC (that's Her Majesty's Revenue and Customs to you and me) thinks that some of that money should go towards running the country. Now, I'm not saying I disagree, but I do think it's fair to understand where my hard-earned cash is going.
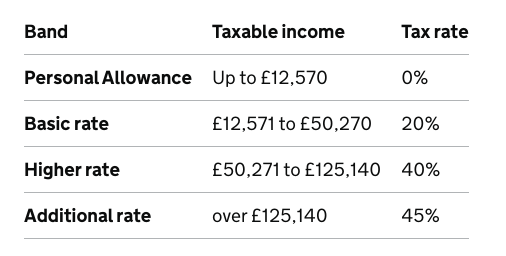
So, let's talk Income Tax. It's a tax on your earnings, plain and simple. The Basic Rate is the lowest rate of tax you pay, and it's currently 20%. Now, before you start doing the math in your head, let me stop you. You don't pay 20% on every pound you earn. It's a progressive tax system, which means you only pay the Basic Rate on the amount you earn above the Personal Allowance.
Must Read
What's the Personal Allowance?
Ah, the Personal Allowance. It's the amount of money you can earn each tax year without paying any Income Tax. For the 2021/22 tax year, it's £12,570. So, if you earn less than that, you won't pay a penny in Income Tax. But if you earn more, that's where the Basic Rate comes in.
Let's say you earn £20,000 a year. You wouldn't pay tax on the first £12,570. But on the remaining £7,430, you'd pay the Basic Rate of 20%. So, you'd pay £1,486 in Income Tax. Not too shabby, huh?
But Why the Basic Rate?
You might be wondering, "Why 20%? Why not 15% or 25%?" Well, the Basic Rate is set by the government and can change from year to year. It's designed to be a fair tax rate that doesn't break the bank for most people. After all, they want us to have enough money to enjoy life (and maybe even pay some taxes with it).
 Smart saving: How to minimise your interest tax bill
Now, if you earn more than £50,270, you'll start paying a higher rate of tax, known as the Higher Rate. But that's a story for another day. For now, let's stick with the Basic Rate. It's like the tax equivalent of a comfy pair of slippers - it might not be exciting, but it's reliable and does the job.
How Do I Pay My Basic Rate Income Tax?
Great question! If you're an employee, your employer will automatically take the tax out of your pay before you even see it. They'll do this through the Pay As You Earn (PAYE) system. It's like they're doing you a favor, but really, it's just the law.
If you're self-employed, it's a bit more complicated. You'll need to fill out a Self Assessment tax return each year and pay your tax in installments. But don't worry, HMRC will send you reminders. They're like your own personal tax nagging service.
 Current UK Tax Brackets 2026: Bands and Rates for 2026/27 | Sleek UK
Can I Reduce My Basic Rate Income Tax?
Now, here's where things get interesting. Yes, there are ways to reduce your tax bill. You can claim tax relief on certain expenses, like working from home or buying tools for your job. You can also invest in Individual Savings Accounts (ISAs) or pensions to save tax. But remember, these are complex areas, so it's always a good idea to seek professional advice.
And there you have it, folks. The Basic Rate Income Tax in all its glory. It's not the most exciting topic in the world, but understanding it can help you keep more of your hard-earned cash. So, the next time you see those words on your payslip, you can smile knowing you've got a handle on your taxes.
Now, who's ready for another coffee?
