How To Look At Your Credit Report

Alright, gather 'round, folks. I've got a tale to tell, a tale of numbers, dates, and mysterious inquiries. It's the thrilling saga of your credit report, the most fascinating...
Alright, gather 'round, folks. I've got a tale to tell, a tale of numbers, dates, and mysterious inquiries. It's the thrilling saga of your credit report, the most fascinating document you've never read. Let's dive in, shall we?
First things first: What's a credit report?
Imagine your credit report as a giant, invisible backpack you carry around. It's filled with all the financial stuff you've ever done - loans, credit cards, even that time you borrowed a dollar from your best friend in kindergarten (kidding, hopefully). It's like a financial CV, but instead of skills, it's got debt.
Now, you might be thinking, "Why on earth would I want to look at that?" Well, my friend, it's like checking your backpack before a big hike. You wouldn't want to find out you've been carrying around a leaky water bottle for the past 10 miles, would you? Same goes for your credit report. You need to know what's in there.
Must Read
Now, where's this mystical backpack hiding?
Your credit report is tucked away with three major credit bureaus: Equifax, Experian, and TransUnion. They're like the librarians of your financial past, and they keep their records locked up tight. But don't worry, you can access them with a simple request. In the US, you're entitled to one free report per year from each bureau. It's like a birthday present, but instead of cake, you get a detailed account of your debt history. Exciting, right?
To get your hands on it, head over to AnnualCreditReport.com. It's the official site, so it's safe and free. Don't be tempted by other sites that might charge you. They're like the used car salesmen of the credit report world - avoid 'em.
Alright, I've got my report. Now what?
First, pour yourself a cup of coffee. Or tea. Or something stronger, if you're feeling brave. Then, find a quiet spot. You're about to have a date with your financial past, and it's best to be alone for this.
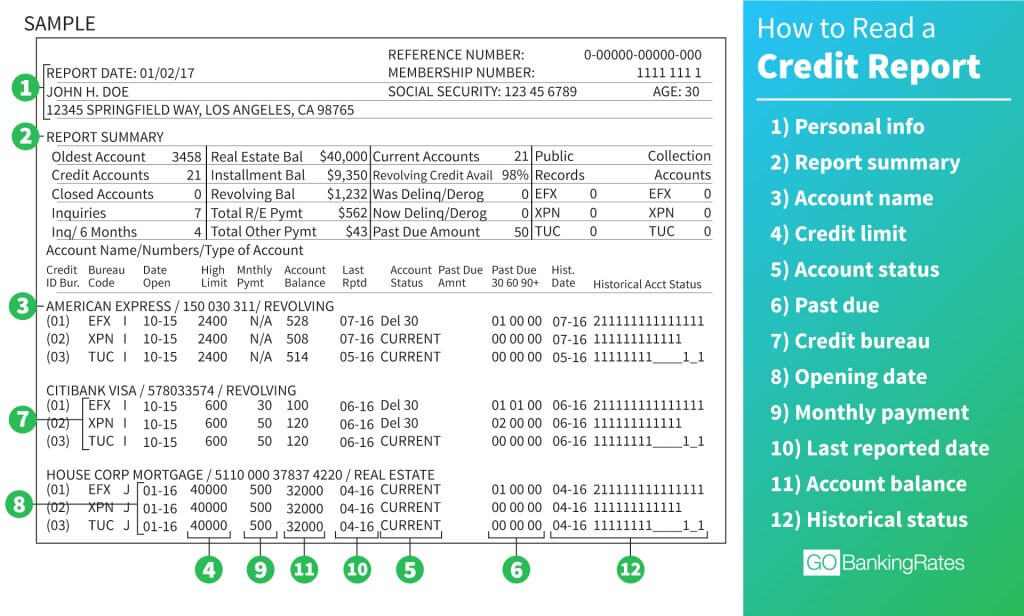
Now, let's talk about what you're looking for. Your report is divided into sections: personal information, credit history, credit inquiries, and public records. It's like a choose-your-own-adventure book, but instead of dragons, you've got debt collectors.
 How To Read Your Credit Report
Personal info: Is that really you?
First stop: personal information. Here, you'll find your name, address, Social Security number, and other details. If something's not quite right, it could be a sign of identity theft. So, keep an eye out. If you spot a mistake, you can dispute it with the credit bureau.
Credit history: The good, the bad, and the ugly
Next up: credit history. This is where you'll find all your accounts - credit cards, loans, mortgages, even that student loan you've been avoiding. Each one has its own section with details like the credit limit, balance, payment history, and more. It's like a financial yearbook, but instead of 'Best Smile,' you've got 'On-Time Payments.'
Now, here's where things get interesting. Each account has a credit utilization ratio, which is just a fancy way of saying 'how much debt you've racked up.' It's calculated as the balance divided by the credit limit. For example, if you've got a $10,000 credit limit and a $5,000 balance, your utilization ratio is 50%. The lower this number, the better. So, if you're carrying a balance close to your limit, it's time to start paying down that debt.
While you're here, check the payment history too. Missed payments can stay on your report for up to seven years. It's like that time you forgot your friend's birthday - it's going to haunt you for a while.
Credit inquiries: Who's been snooping?
Credit inquiries are like the guestbook of your financial life. Every time someone checks your credit - like when you apply for a loan or a new credit card - it gets logged here. Too many inquiries can hurt your score, so keep an eye out for any mysterious ones. If you spot something fishy, dispute it with the credit bureau.
 Credit Reports Tutorial | Sophia Learning
Public records: The big stuff
Last stop: public records. This is where you'll find big financial events like bankruptcies, foreclosures, and tax liens. These can stay on your report for up to 10 years, so if you've got one, it's a good idea to start planning how you're going to deal with it.
What if I find something wrong?
If you spot a mistake, don't panic. You can dispute it with the credit bureau. They're required by law to investigate and correct any errors. Just gather your evidence, write a letter explaining the mistake, and send it off. It's like writing a letter to Santa, but instead of toys, you're asking for better credit.
Now what?
Congratulations, you've just had a date with your financial past. It's not always pretty, but it's important. So, make a habit of checking your credit report regularly. It's like going to the dentist - you don't want to go, but it's necessary for your financial health.
And remember, your credit report is just one part of your financial life. It's like a book - it's important, but it's not the only thing you should be reading. So, go forth, keep learning, and keep improving that credit score.
And if all else fails, just remember: if you can't beat 'em, join 'em. Start a credit union, become a billionaire, and then you won't have to worry about credit reports anymore. Now, who's with me?
