How To Compute Monthly Interest

Ever wondered how banks calculate the interest on your monthly loan or credit card payment? It's like they've got some secret math club going on, right? Well, today we're gonn...

Ever wondered how banks calculate the interest on your monthly loan or credit card payment? It's like they've got some secret math club going on, right? Well, today we're gonna crack that code and make it as chill as a Sunday afternoon barbecue. Let's dive in!
First things first, what's this monthly interest all about?
Imagine you've got a loan of $10,000, and your bank says you've gotta pay 6% interest per year. Now, you might think, "Hey, that's not so bad!" But here's the thing: banks don't wait until the end of the year to collect their interest. They want their money now! So, they break it down into tiny, monthly chunks. It's like they're saying, "Give us a little bit each month, and we'll call it even at the end of the year."
Alright, so how do they calculate this monthly interest?
It's actually pretty simple, once you get the hang of it. The formula they use is:
Must Read
Monthly Interest = (Annual Interest Rate / 12) * (Loan Balance)
Let's break that down. The Annual Interest Rate is that 6% we talked about earlier. The Loan Balance is how much you've still got to pay back. And the 12 is just there to divide the annual interest into monthly slices.
Let's give it a whirl with an example, yeah?
So, you've got that $10,000 loan, and your bank wants 6% interest per year. Let's find out how much you'll owe each month.
 Monthly Compound Interest - What Is It, Formula & Examples
Monthly Interest = (0.06 / 12) * $10,000
First, divide the annual interest rate by 12: 0.06 / 12 = 0.005. Then, multiply that by your loan balance: 0.005 * $10,000 = $50.
So, each month, you'll owe the bank an extra $50 on top of your principal payment. Not too shabby, huh?
But wait, there's more!
Here's where things get a little more interesting. If you're only making the minimum payment each month, your loan balance won't go down as fast as you might think. That means you'll be paying interest on a bigger balance for longer. It's like you're stuck in a never-ending game of whack-a-mole, and the moles are your interest payments!
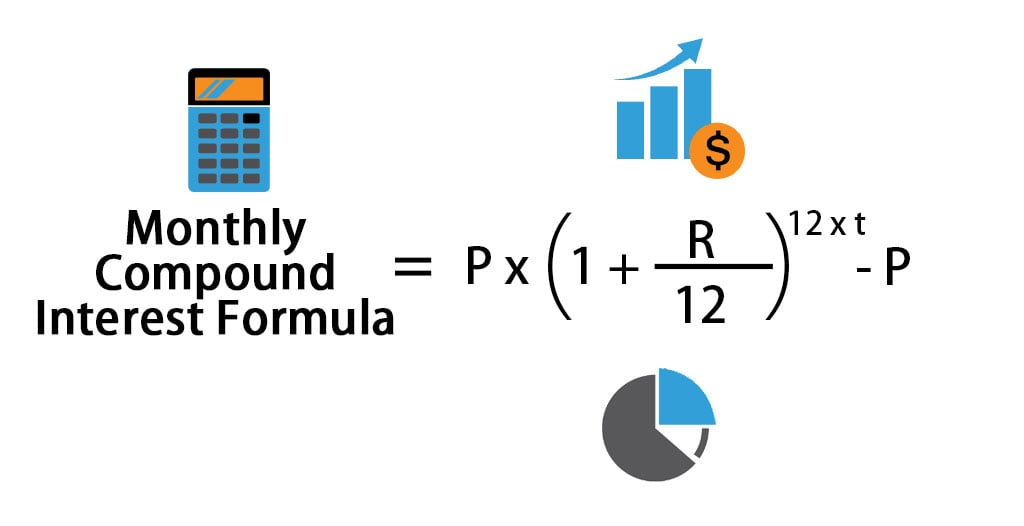 Exercicios Misturas Homogeneas E Heterogeneas Compound - Printables
But don't worry, you can beat this game! If you make extra payments, you'll reduce your loan balance faster, and you'll pay less interest in the long run. It's like you're finally getting the upper hand on those moles!
So, why does all this matter?
Well, understanding how monthly interest works can help you make better decisions about your money. You can figure out how much you'll really be paying for that new car or that dream vacation. And who knows, maybe you'll even start saving more, just to avoid those pesky interest charges!
Plus, it's always cool to learn something new, right? So next time you're at a party, and someone starts talking about interest rates, you can be like, "Yeah, I know how that works. It's like breaking down an annual interest rate into monthly slices. No big deal." And then you can casually walk away, leaving them in awe of your newfound financial wisdom.
So there you have it, folks! Monthly interest isn't so scary after all. It's just a simple formula that helps banks (and you) keep track of how much money is changing hands. Now go forth and conquer those interest rates!
