How Much Interest Is Student Loans

So, there I was, fresh out of college, diploma in hand, and a mountain of student loans waiting for me. I remember thinking, "Great, now I've got a degree and a debt that coul...

So, there I was, fresh out of college, diploma in hand, and a mountain of student loans waiting for me. I remember thinking, "Great, now I've got a degree and a debt that could fund a small country. What have I gotten myself into?"
If you're in a similar boat, you're probably wondering, "How much interest am I actually paying on these student loans?" Well, grab a coffee, let's dive into this together.
First Things First: What's the Interest Rate?
Before we get into the nitty-gritty, let's talk about interest rates. These are the percentages that determine how much extra you'll pay on top of your original loan amount. They're typically fixed or variable, meaning they stay the same or change over time.
Must Read
In the U.S., federal student loans have fixed interest rates, set by Congress each year. For instance, as of 2021, undergraduate loans have a 3.73% interest rate. Private loans, on the other hand, can have both fixed and variable rates, which are usually higher and can change based on market conditions.
So, How Much Interest Are We Talking About?
Now, let's crunch some numbers. Say you've taken out a $20,000 federal student loan at a 3.73% interest rate. If you're on a 10-year repayment plan and make all your payments on time, you'd pay about $2,500 in interest over the life of the loan.
But wait, what if you're not done with school? Graduate or professional degrees can tack on another $100,000 or more in loans. Suddenly, that interest adds up fast. And if you're on an income-driven repayment plan or take longer to pay off your loans, interest can really start to pile up.
 Subsidized vs. Unsubsidzed Student Loans: Know the Difference for 2026
Let's Not Forget About Capitalization
Here's where things get a bit tricky. If you're not careful, unpaid interest can capitalize, or get added to your principal balance. This means you'll pay interest on that interest, making your debt grow even faster. Yikes!
For example, if you don't pay the interest on your subsidized federal loans while you're in school, it will capitalize when you graduate. Suddenly, that $20,000 loan is now $20,760, and you'll pay interest on that higher amount.
Can I Do Anything to Reduce Interest?
Absolutely! Here are a few tips:
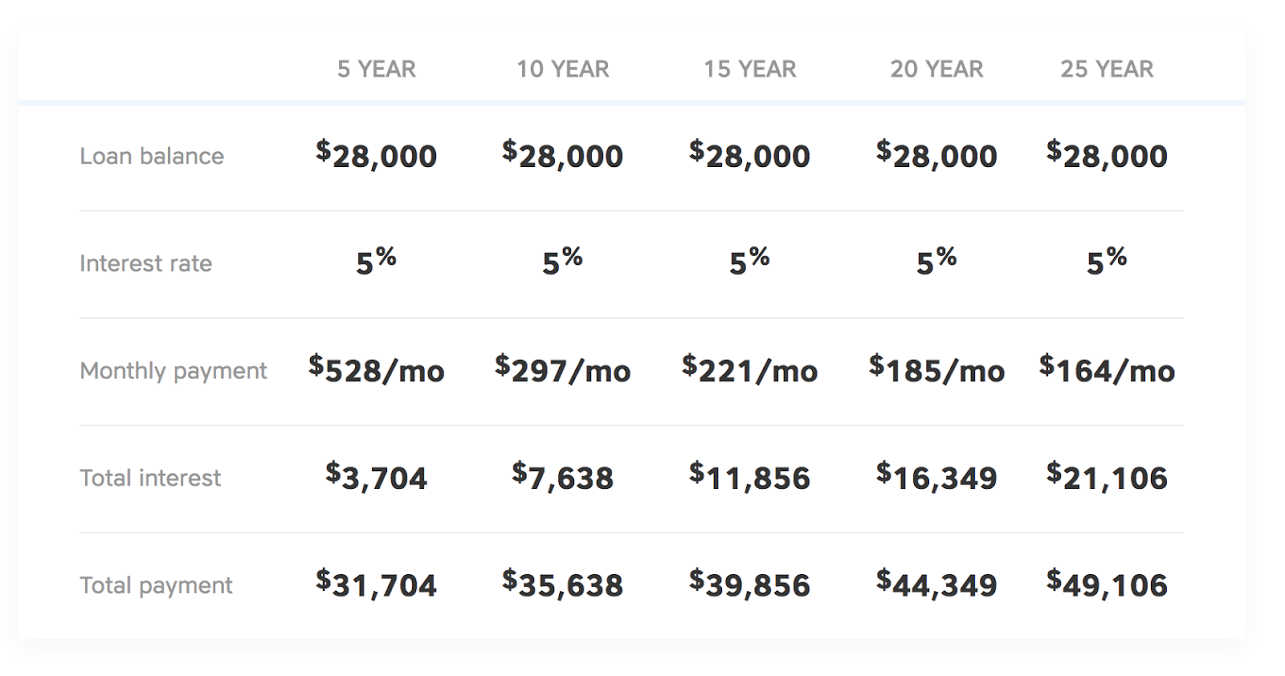 Everything You Need To Know About Student Loan Interest Rates
- Pay as much as you can while in school. Even small payments can help keep interest from piling up.
- Consider refinancing. If you have good credit and a stable job, refinancing can help you get a lower interest rate on your private loans.
- Make extra payments. Even an extra $20 a month can save you hundreds in interest over the life of your loan.
Remember, every little bit helps. And hey, you're not alone. We're all in this together, navigating the wild world of student loans.
Stay Informed, Stay Sane
Lastly, keep an eye on your loan servicer's website. They should provide tools to help you understand your interest and how much you'll pay over time. And if you're feeling overwhelmed, don't hesitate to reach out to them or a trusted financial advisor.
So, there you have it. Now you know a bit more about how much interest you're paying on your student loans. It's not the most exciting topic, but it's a crucial one. After all, knowledge is power, and understanding your loans can help you take control of your financial future.
Now, go forth, make those loan payments, and let's conquer this debt together!
